2019 Bitcoin Whale Moved $378M for Just $1

Bitcoin Wallet Moves About $378 Million in BTC for Roughly $1.10 Fee

A Bitcoin wallet that had remained largely inactive since 2019 moved approximately 4,500 BTC in a single transaction early Friday, transferring an estimated $378 million onchain while paying a network fee of about $1.10.

Long-Dormant Wallet Empties Its Balance

The address had not sent bitcoin since April 2022, according to blockchain data. Its holdings had been accumulated in August 2019 and remained untouched for several years before the latest transaction.

The transfer moved essentially the wallet’s entire balance in one transaction. Based on the reported market value, the coins were worth roughly $378 million at the time of the movement.

Low-Cost Bitcoin Settlement

The transaction incurred a fee of approximately $1.10, highlighting the ability to transfer large amounts of bitcoin without fees being directly tied to the value of the assets moved. Bitcoin transaction fees are generally determined by factors such as data size and network demand rather than the dollar value of the transfer.

The movement does not, by itself, identify the wallet owner or explain the reason for the transfer. Onchain data can show the movement of funds between addresses, but it does not reveal whether the transaction involved an exchange deposit, internal wallet restructuring, custody arrangements or a sale.

Market Significance

Large transfers from long-dormant wallets are closely monitored because they can provide insight into potential changes in ownership or the movement of older bitcoin holdings. However, a wallet transfer alone does not confirm that the bitcoin has been sold or is being prepared for sale.
MEXC Returns to TOKEN2049 Singapore as Platinum Sponsor for Crypto Innovation

MEXC to Return as Platinum Sponsor of TOKEN2049 Singapore

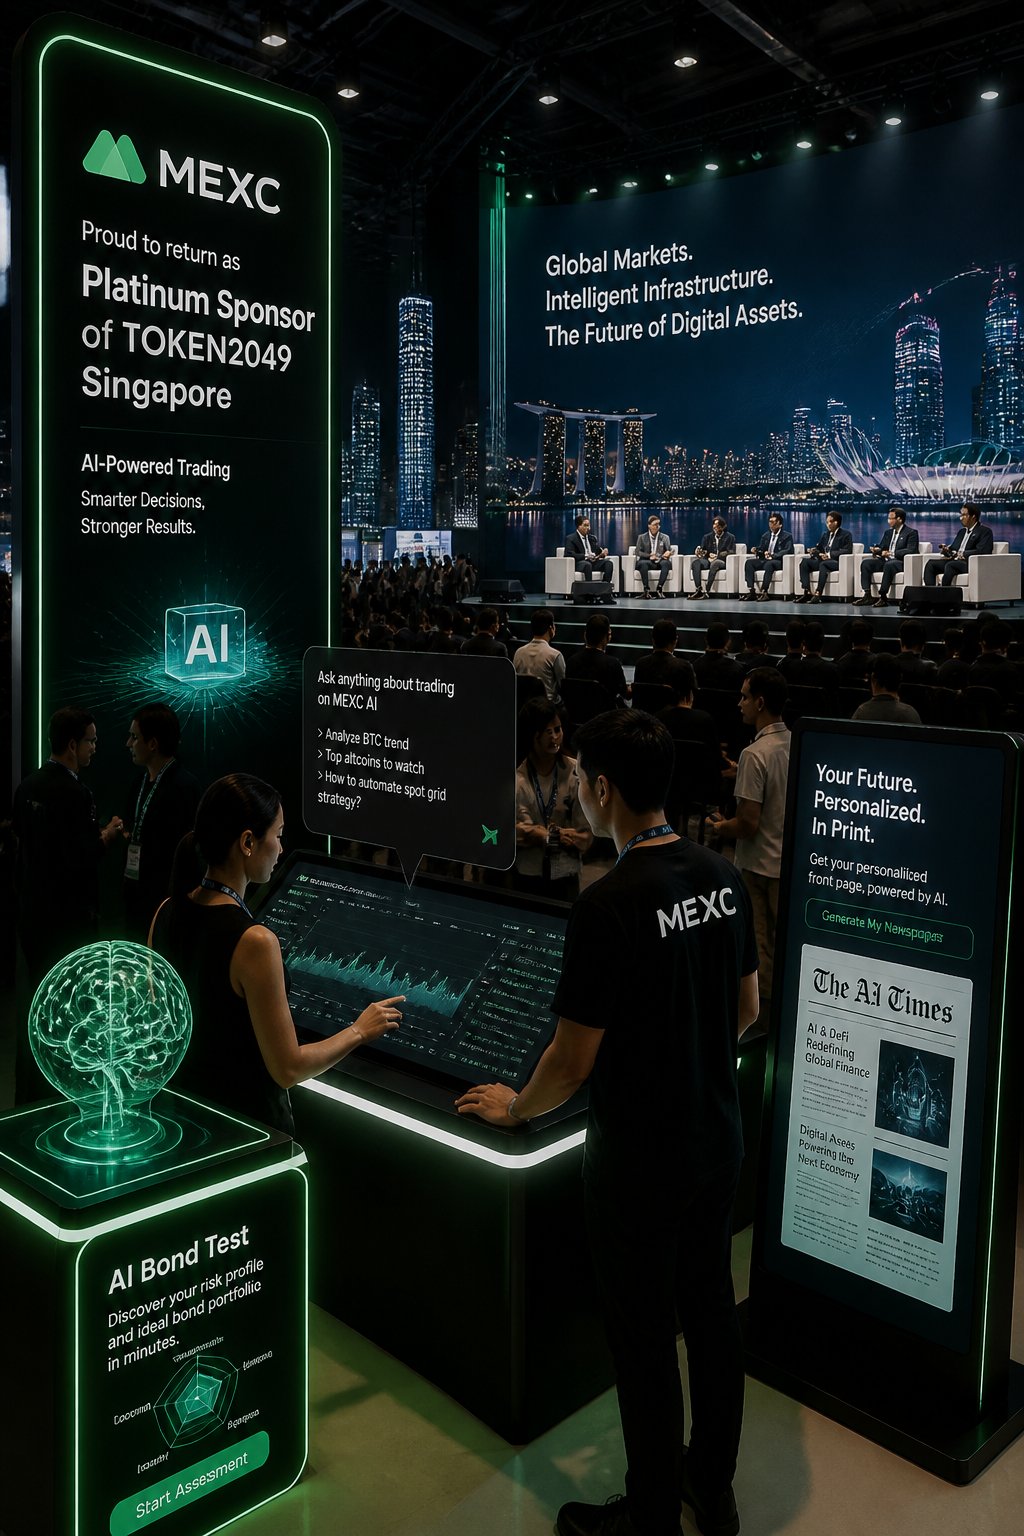
MEXC will return to TOKEN2049 Singapore as a Platinum Sponsor on September 25, 2026, with an expanded presence focused on artificial intelligence, trading tools and the evolving structure of global digital-asset markets.

AI Trading Experiences at the MEXC Booth

Visitors to booth PB1-36 will be able to explore MEXC’s AI-focused trading experiences, including the MEXC AI Trading Challenge. The demonstration is designed to show how users can describe trading intentions in natural language and connect those instructions with MEXC’s trading capabilities through AI agents supported by MEXC CLI.

The company said the experience reflects a broader shift in AI applications, from analyzing market data to supporting execution. MEXC is presenting these tools as a way to make advanced trading functionality more accessible to retail users.

The booth’s AI Zone will also feature the AI Bond Test, an interactive activity focused on how people understand and engage with AI in everyday settings. Another installation, called The NEXT Newspaper, will draw on findings from MEXC’s AI trading research. Visitors will be able to personalize a newspaper with their photographs and predictions about the future of AI and trading.

MEXC Stage to Examine Trading Market Developments

MEXC will host a dedicated stage at the event featuring discussions on developments affecting trading platforms and market infrastructure.

One panel will include MEXC Chief Executive Officer Vugar Usi Zade and other industry participants. The discussion is expected to cover changing user behavior, broader market access, new trading experiences, infrastructure development and collaboration between trading platforms.

The sessions will examine how exchanges are responding to shifts in market structure and the growing use of automated and AI-supported tools in digital-asset trading.

Company Overview

Founded in 2018, MEXC describes itself as a global multi-asset trading platform serving users across more than 170 markets. The platform offers access to cryptocurrencies, derivatives and other digital assets, as well as stocks, tokenized assets and products linked to traditional finance, according to the company.

MEXC also promotes zero trading fees on eligible products, deep liquidity and a range of trading tools. Fee structures and product availability may vary by market, account type and transaction.

Through its booth, stage programming and interactive installations, MEXC said it aims to engage users, partners and industry participants during TOKEN2049 Singapore and gather perspectives on the development of trading platforms and global markets.

Bitcoin News: Bond Yields Hit 24-Year High as Crypto Titans Clash

U.S. Treasury yields have climbed to levels not seen in decades, drawing contrasting interpretations from prominent investors and cryptocurrency industry figures. The 30-year Treasury yield closed at 5.47% on Sept. 24, its highest level since February 2002, according to data from the U.S. Treasury.

Long-term Treasury yields reach multidecade highs

The Treasury’s daily yield-curve data showed the 10-year note closing at 5.18% and the 30-year bond at 5.47%. Rising yields indicate that investors are demanding higher returns to hold government debt, particularly at longer maturities.

Long-term yields can be influenced by several factors, including expectations for inflation, economic growth, federal borrowing and future interest-rate policy. Higher yields also increase borrowing costs across the economy and can affect valuations for risk assets, including stocks and cryptocurrencies.

Market participants offer different interpretations

The move has prompted public commentary from figures including economist Peter Schiff, investor Bill Ackman, Coinbase co-founder and CEO Brian Armstrong, and BitMEX co-founder Arthur Hayes. Their assessments differ on what the rise in yields signals for inflation, government finances, monetary policy and broader markets.

Schiff has frequently linked higher bond yields to concerns about inflation and fiscal policy, while Ackman has highlighted the potential implications of rising long-term borrowing costs. Armstrong and Hayes have discussed the potential impact of macroeconomic conditions on digital assets and the financial system.

Why the yield move matters for cryptocurrency markets

Higher Treasury yields can make government bonds more attractive relative to assets such as Bitcoin and other cryptocurrencies, particularly when investors reduce exposure to riskier markets. They can also tighten financial conditions by raising the cost of borrowing for businesses, consumers and governments.

At the same time, some market participants view persistent fiscal deficits, inflation risks or declining confidence in fiat currencies as factors that may support interest in Bitcoin as an alternative asset. The competing interpretations reflect uncertainty over whether the yield increase is primarily a sign of stronger growth, renewed inflation pressure or concern about the government’s borrowing requirements.

For cryptocurrency markets, the direction of yields, inflation expectations and central-bank policy will remain important variables. A sustained increase in long-term borrowing costs could continue to influence investor appetite for digital assets and other speculative investments.

Hut 8 Secures $140M Bid for Poolin’s Texas Data Centers

Hut 8 Wins $140 Million Bid for Two Poolin Data Centers in Texas

Hut 8 has been named the winning bidder for two Texas data-center sites owned by bankrupt cryptocurrency mining company Poolin, offering $140 million in cash and other consideration. The bid is nearly three times the combined $52 million stalking-horse offer that launched the bankruptcy auction. The transaction still requires approval from the U.S. Bankruptcy Court for the District of New Jersey.

Auction Bids Rose Sharply

The winning bid covers Poolin’s Pyote and Tarbush facilities in Texas. The auction began with stalking-horse bids totaling $52 million: Thor CALAP offered $15 million for the Pyote campus and $37 million for Tarbush.

Competition drove the final offer substantially higher. Other bidders included DigiPower X and Pecos Industrial Development, which participated as a designee of artificial-intelligence infrastructure company Fluidstack.

Hut 8 ultimately secured the top bid at $140 million, marking a significant increase from the initial offers.

Bankruptcy-Court Approval Remains Pending

Hut 8’s successful auction bid does not mean the acquisition has closed. The proposed sale remains subject to approval by the U.S. Bankruptcy Court for the District of New Jersey at a hearing scheduled for September 29.

Until the court approves the transaction and the remaining closing conditions are satisfied, Hut 8 should be considered the winning bidder rather than the completed owner of the facilities.

Data Centers Could Support More Than Bitcoin Mining

Poolin entered Chapter 11 bankruptcy in July with approximately $173 million in obligations. A significant portion of that debt was linked to IOUs owed to Poolin Wallet users after withdrawals were suspended in 2022.

For Hut 8, the Texas sites could support its broader strategy of expanding beyond traditional Bitcoin mining. The company has increasingly focused on large-scale data-center and artificial-intelligence infrastructure, where reliable electricity and grid access are key assets.

The auction’s outcome also highlights the potential value of cryptocurrency mining facilities beyond their current use. The increase from a combined $52 million opening bid to a $140 million winning offer suggests that buyers may be placing greater importance on the sites’ power capacity, location and potential to support broader computing operations.

Privy Expands TRON Support as Stablecoin Payments Infrastructure Scales

Privy Expands TRON Integration With New Wallet, Transfer and Monitoring Tools

Privy has expanded its integration with the TRON blockchain, adding transaction, transfer, policy and monitoring tools for developers building wallets and stablecoin-powered financial products. The Stripe-owned wallet infrastructure provider said the expanded offering is designed to support payments, treasury management and other business applications.

Expanded Controls for TRON Wallets

The integration allows developers to programmatically construct, sign and broadcast supported TRON transactions. Privy has also added webhooks for monitoring wallet balances and on-chain activity, giving businesses more visibility into asset movements and account events.

New policy tools can be used to enforce spending limits, restrict transfers to approved recipients and require designated approvals before transactions are completed. Privy’s Transfer APIs allow supported assets to be moved programmatically between wallets.

The tools are primarily aimed at businesses embedding stablecoin functionality into financial products rather than individual users making manual transfers. Potential applications include treasury management, cross-border payments and embedded application wallets.

Privy says more than 2,000 developers and businesses use its infrastructure to support over 160 million accounts.

TRON’s Role in USDT Settlement

The expanded integration comes as TRON remains one of the largest settlement networks for Tether’s USDT stablecoin. According to data published by the network in September, more than $94 billion in USDT was circulating on TRON, with the blockchain processing hundreds of billions of dollars in stablecoin activity each month.

That scale has increased demand for infrastructure that allows companies to use stablecoins without operating blockchain nodes, developing key-management systems or building transaction-policy tools from the ground up.

Privy’s platform is designed to abstract those technical requirements through application programming interfaces and managed wallet infrastructure. According to the announcement, companies including Onafriq and Paystack are using Privy and TRON for treasury and wallet applications.

Stablecoins Move Further Into Embedded Finance

The integration reflects a broader shift in stablecoin adoption, with blockchain networks increasingly operating behind the scenes of payment applications and financial services. In these products, users may interact with familiar interfaces without directly choosing or managing the underlying network.

TRON provides substantial USDT liquidity, while infrastructure providers such as Privy are seeking to make that liquidity easier for businesses to integrate into payments, treasury systems and other financial products.

By News Desk
Edited by Samuel Rae

Visa Study: Bank-Style Protections Could Supercharge Stablecoin Adoption

Visa Study Finds Consumer Protection Could Drive Stablecoin Adoption in the U.S.

Summary: U.S. willingness to use stablecoins rises from 36% to 56% when hypothetical bank-level fraud protection and deposit insurance are added, according to Visa’s Money Travels 2026 study. The findings suggest that trust and consumer safeguards may be a greater barrier to mainstream adoption than the technology itself.

Stablecoins have made payments faster, cheaper and easier to conduct across borders. However, new research from Visa indicates that the next major challenge for wider adoption may be consumer confidence rather than the underlying payment infrastructure.

The study found that 36% of U.S. respondents would consider using stablecoins under a base scenario. That figure increased to 45% when the stablecoin product was offered through an existing financial provider and rose to 56% when hypothetical bank-level fraud protection and deposit insurance were included.

Familiar safeguards influence consumer interest

Stablecoins are digital assets designed to maintain a relatively stable value, often by tracking fiat currencies such as the U.S. dollar. They are frequently promoted for their potential to reduce payment costs and settlement times.

Visa’s findings suggest that consumers also place significant importance on what happens when a transaction goes wrong. Many respondents indicated that they would accept slower transfers if doing so provided stronger protections against fraud.

In the United States, 45% of those surveyed said they would accept a 24-hour delay in exchange for enhanced fraud protection. The result highlights a potential trade-off between speed and security for mainstream users.

Fraud concerns remain widespread

The research found that 36% of Americans surveyed had encountered scams involving cross-border payments. In addition, 44% expressed concern about fraud enabled by artificial intelligence, including deepfakes.

Those concerns may help explain why a payment product can offer technical advantages over traditional systems while still facing resistance from everyday consumers. For many users, confidence in dispute resolution, fraud reimbursement and institutional backing may be as important as transaction speed or cost.

Deposit insurance remains hypothetical

Visa’s survey included bank-style fraud protection and deposit insurance as hypothetical product features. Stablecoins are not automatically covered by protections such as Federal Deposit Insurance Corporation insurance simply because they are designed to track the value of the U.S. dollar.

As a result, the findings measure how consumers say they might respond if stronger safeguards were available. They do not indicate that all stablecoin holders currently receive those protections.

The U.S. portion of the study was conducted by Morning Consult among 2,192 adults. Globally, Visa surveyed more than 45,000 people across 20 markets.

The results suggest that stablecoin adoption may depend not only on improving the movement of money, but also on making the protections surrounding that money clear, familiar and dependable to consumers.

By News Desk
Edited by Samuel Rae

Blockchain.com and NYSE Unveil 24/7 Tokenized Stock Trading Plans

Blockchain.com and NYSE Group Explore Tokenized Stocks and ETFs

Blockchain.com and NYSE Group have signed an agreement to explore offering tokenized U.S.-listed stocks and exchange-traded funds through a planned digital trading venue. The proposed service could support around-the-clock trading for eligible users in certain jurisdictions, but it is not yet live and remains subject to regulatory approval.

Proposed Access to Tokenized Securities

The agreement covers product development and market-data sharing, with the longer-term goal of giving Blockchain.com users access to tokenized versions of securities listed on the New York Stock Exchange.

Tokenized securities represent ownership or economic exposure to traditional financial assets through blockchain-based infrastructure. If the initiative proceeds, eligible users could potentially access tokenized stocks and ETFs through Blockchain.com’s crypto-focused platform.

The proposed model could also introduce features more commonly associated with digital-asset markets, including fractional ownership, stablecoin funding and onchain settlement.

Trading Beyond Traditional Market Hours

NYSE has outlined plans for a digital alternative trading system, or ATS, designed to support trading in tokenized securities. The venue could enable access outside the standard hours of traditional U.S. equity markets, including potentially around-the-clock trading.

Blockchain.com would serve as a potential distribution partner if the digital ATS launches. The arrangement could give the platform’s global customer base access to tokenized versions of eligible exchange-listed shares and ETFs from within the broader Blockchain.com ecosystem.

Planned Two-Way Market-Data Integration

The companies also plan to explore the exchange of market data. Intercontinental Exchange, NYSE’s parent company, could distribute Blockchain.com’s crypto-market data, while Blockchain.com could integrate ICE and NYSE equity data into its products.

The proposed data-sharing arrangement would connect traditional equity-market information with crypto-market infrastructure, potentially giving users access to both asset classes through related products.

Project Remains Subject to Regulatory Approval

The agreement is a memorandum of understanding and does not represent the launch of a live trading service. Tokenized NYSE securities are not currently available for unrestricted 24-hour trading through Blockchain.com.

The project depends on the launch of NYSE’s planned digital ATS, as well as the regulatory approvals required for tokenized securities and related trading services. Availability would also vary by jurisdiction.

Tokenization does not remove securities-law requirements. Any offering would still need to comply with applicable rules governing the issuance, trading and custody of securities.

The proposed partnership brings together Blockchain.com’s crypto users and digital-asset infrastructure with NYSE’s regulated market structure and listed-securities ecosystem. If approved and implemented, it could provide a link between traditional equity markets and blockchain-based settlement systems.

Bitcoin News: Gold’s 50-Year Wealth Trick Goes Onchain

Paxos Labs Launches PAXGy Token to Bring Gold-Leasing Exposure Onchain

Paxos Labs has launched PAXGy, a token designed to give eligible market participants access to institutional gold-leasing economics through a digital asset backed by Pax Gold (PAXG).

Token Links Gold Leasing and Blockchain Infrastructure

The product was introduced on Sept. 24 and is structured around PAXG, Paxos’ tokenized gold asset. PAXG represents ownership of physical gold held in custody, allowing holders to gain digital exposure to the metal without directly storing bullion.

According to the announcement, PAXGy is intended to package elements of the institutional gold-leasing market into a blockchain-based token. Gold lending rates have been quoted on working days for decades, but access to those markets has traditionally been concentrated among financial institutions and other professional participants.

Institutional Gold Markets

Gold leasing generally involves one party lending gold to another in exchange for a fee or interest payment. The arrangement can support liquidity and financing across the precious-metals market, while the lending terms are influenced by supply and demand for physical gold.

Paxos Labs said PAXGy is designed to broaden access to this market structure by using tokenized gold as its underlying asset. The company’s description indicates that the reserves associated with the product are intended for institutional deployment.

Role of PAXG

PAXG serves as the foundation for the product’s gold exposure. Each PAXG token is linked to a specified amount of physical gold held by Paxos, providing the asset with a blockchain-based representation of bullion ownership.

The launch reflects the broader effort to bring traditionally illiquid or institutionally controlled financial markets onto blockchain networks. As with other tokenized assets, PAXGy’s availability, transferability and economic terms will depend on its official product documentation and applicable market restrictions.

Regal Commodities v. Tauber: NY Court Applies Commodity Laws to Crypto Margin Trades

Wellermen Image Regal Commodities v Tauber — Court Clears Path for Commodity Suits Over Crypto
A New York appellate court just handed commodity brokers a powerful new weapon: the ability to sue crypto traders under old-school commodity laws that treat digital assets like corn futures. The March 27 ruling in Regal Commodities v Tauber expands legal exposure for traders who use leverage or margin, potentially dragging DeFi participants and exchange users into state-court battles that were once reserved for professional futures desks.

The case started when Regal, a licensed commodity broker, claimed Tauber racked up massive losses on leveraged crypto trades and then refused to pay. Tauber argued crypto wasn’t a “commodity” under New York’s General Business Law, so the brokerage couldn’t use that statute to collect. The appellate panel disagreed, holding that the economic reality of margin trading—not the underlying asset—determines whether a transaction falls under commodity rules. Once leverage and margin enter the picture, the court said, the deal looks and acts like a regulated futures contract, crypto or not.

Judges ruled that Regal can pursue its claim under the commodity statute, giving brokers a faster collection tool and exposing traders to personal liability even if the exchange or protocol itself collapses. Tauber loses the ability to hide behind the “it’s just crypto” defense; Regal gains a green light to treat unpaid margin calls like traditional commodity debts. The decision doesn’t ban crypto trading, but it strips away one layer of insulation traders thought they had when dealing with U.S.-based brokers.

In plain terms, the court decided that if you trade crypto with borrowed money through a licensed intermediary, you’re playing under the same legal roof as soybean speculators. That means standard anti-fraud and collection rules apply, regardless of how decentralized the token claims to be.

For markets, the ruling tightens the noose around U.S.-facing exchanges and DeFi front-ends that offer margin products. The SEC and CFTC already fight over classification; now state courts have joined the fray, giving regulators another hook to pressure platforms into registration or geo-blocking. Traders who assumed offshore protocols would shield them from U.S. margin rules may find themselves named in state lawsuits, while DEX liquidity providers could see reduced U.S. volume as risk premiums rise. Stablecoin issuers aren’t directly touched, but any protocol promising leveraged exposure now carries hidden legal overhead.

Bottom line: leverage just got more expensive in ways lawyers, not smart contracts, will price.

CFTC Wins Mandamus, Kraft Keeps Secrets: Regulators Move Faster While Trade Secrets Stay Sealed

Wellermen Image **CFTC WINS MANDAMUS, BUT KRAFT KEEPS ITS SECRETS**
The Seventh Circuit just ordered a district judge to stop sitting on a CFTC enforcement file, yet simultaneously let Kraft Foods keep sensitive documents under seal. The ruling matters because it shows how regulators can speed up their own cases while companies still shield internal pricing data from the public and rivals.

Kraft and its sister company Mondelēz were accused by the CFTC of manipulating the wheat-futures market in 2011. When the agency asked the district court to unseal portions of its investigative record, the judge stalled for more than a year. The CFTC responded with an extraordinary writ of mandamus, arguing that endless delay was itself a form of obstruction. The appeals court agreed that the lower court had a “clear duty” to rule, but it refused to force the actual release of the documents, leaving that fight for another day.

The immediate winner is the CFTC, which now has a green light to push its manipulation case forward without waiting on a reluctant judge. Kraft and Mondelēz, however, preserve their ability to argue that customer contracts, hedging strategies, and internal risk memos deserve trade-secret protection. The decision does not settle whether those records will ever become public.

In plain terms, the court told the district judge to do his job, but it did not rewrite the rules on what counts as confidential commercial information. Regulators gain speed; private firms keep leverage over disclosure.

For crypto markets, the ruling is a reminder that enforcement tempo and evidentiary secrecy are two different levers. A faster CFTC could bring cases against DeFi protocols or stablecoin issuers, yet those same firms might still wall off code, wallet addresses, or treasury strategies behind the same “trade secrets” shield. Traders should expect quicker subpoenas, not necessarily clearer disclosure.

The lesson: procedural wins for regulators do not automatically translate into transparency wins for the market.

Chicago MDL Consolidates 3 Crypto Suits, Tests Howey and Dealer Status

Wellermen Image Judges Centralize Crypto Platform Suits in Chicago
Three separate lawsuits against the same crypto trading platform have been consolidated into a single proceeding in the Northern District of Illinois, giving one federal judge control over claims that could redefine how U.S. courts treat digital-asset exchanges. The decision accelerates litigation risk for platforms and token issuers while handing plaintiffs a stronger negotiating hand.

The suits accuse the exchange of selling unregistered securities, operating without broker-dealer licenses, and mishandling customer funds. Plaintiffs in each case asked the Judicial Panel on Multidistrict Litigation to gather the cases so discovery, expert testimony, and settlement talks could proceed under one roof. The panel agreed, rejecting arguments that differences in state law and procedural posture made a single forum inefficient. Chicago now becomes ground zero for the first major test of whether tokens listed on the exchange qualify as investment contracts under the Howey test and whether the platform itself is a dealer under federal securities law.

The ruling hands the Northern District of Illinois early influence over precedent that other circuits may follow. Because the court sits in the Seventh Circuit, any summary-judgment or class-certification decision will carry persuasive weight in future crypto disputes nationwide. Defense counsel will face coordinated document production and unified deposition schedules, raising litigation costs and the odds of a sizable settlement before trial. Plaintiffs, by contrast, gain economies of scale that could pressure the platform to disclose internal communications, token-listing criteria, and treasury-wallet flows—information that often moves markets when made public.

For the broader industry, the transfer underscores the SEC’s litigation-first strategy: rather than wait for new statutes, the agency is steering cases into sympathetic districts to lock in favorable interpretations of “investment contract” and “dealer.” A loss on the securities question would ripple through token classification, forcing exchanges to decide whether to delist assets or register as broker-dealers. Stablecoin issuers that route liquidity through the platform could also face secondary-liability theories if judges accept an expansive view of what constitutes an offer or sale of securities.

Traders should watch early motion practice closely. Rulings on personal jurisdiction, extraterritorial reach, and the economic realities test will telegraph whether the bench views crypto trading as ordinary commerce or as a regulated securities business. Volatility in the exchange’s native token and correlated altcoins is likely each time a filing hits the docket.

The consolidation order signals that crypto litigation is entering its institutional phase—defendants can no longer count on fragmented cases and forum-shopping to blunt enforcement risk.

Bitcoin Steadies as ONDO Surges Amid US Treasury Yield Spike

Bitcoin Holds Near $84,000 as Treasury Yields Reach 19-Year High

U.S. Treasury yields rose to their highest level in 19 years on Thursday, increasing pressure on risk-sensitive assets. Bitcoin remained relatively steady near $84,000, while ONDO emerged as the strongest performer among major altcoins.

Higher Yields Pressure Risk Assets

The rise in Treasury yields has added to market pressure across risk assets, including cryptocurrencies. Higher government bond yields can reduce the appeal of speculative investments by offering investors comparatively stronger returns in traditional fixed-income markets.

Bitcoin Holds Steady

Despite the broader market pressure, Bitcoin continued to trade near the $84,000 level. The cryptocurrency’s stability contrasted with the stronger moves seen in parts of the altcoin market.

ONDO Leads Altcoin Performance

ONDO, the token associated with Ondo Finance, was the top-performing altcoin during the session. The move came as the wider crypto market responded to changing macroeconomic conditions and elevated Treasury yields.

Fifth Circuit Blocks Tornado Cash Sanctions, Says Code Isn’t a Person

Wellermen Image COURT SLAPS SEC: FIFTH CIRCUIT GIVES TORNADO CASH NEW LIFE
The Fifth Circuit just handed the Treasury Department and the SEC a rare loss on crypto sanctions. By restoring Tornado Cash’s access to U.S. financial rails, the court signaled that regulators can’t simply label code “a sanctioned entity” and expect courts to rubber-stamp the move. The ruling lands at the exact moment stablecoin issuers and DeFi protocols are watching every enforcement precedent for clues on how far Washington’s reach extends.

The case began when Tornado Cash, a decentralized mixer built on Ethereum, was placed on OFAC’s sanctions list after Treasury accused it of laundering more than $7 billion tied to North Korean hackers and ransomware crews. The mixer’s smart contracts were coded to be unstoppable once deployed, yet Treasury treated the contracts themselves as “property” belonging to a sanctioned foreign adversary. Tornado Cash’s developers and users sued, arguing that immutable code is not a person, not an entity, and therefore cannot be sanctioned under existing statutes. The district court sided with Treasury, but the Fifth Circuit reversed.

Judges held that OFAC exceeded its statutory authority by sanctioning open-source software rather than the people who might use it. The panel found no evidence that the immutable contracts themselves were “owned” by any sanctioned party, and therefore the agency lacked the power to block Americans from interacting with them. The decision does not bless money laundering; it simply says regulators must target actual humans or companies, not autonomous lines of code. Treasury can still prosecute individual users or developers who break the law, but the contracts themselves stay live.

In plain English, the ruling draws a hard line between software and the people who run it. If code cannot be owned, it cannot be sanctioned, and agencies cannot shortcut due process by pretending otherwise. The logic echoes earlier fights over whether social-media algorithms or bitcoin nodes can be treated as “persons” under the law. For now, the Fifth Circuit says no.

The market read the opinion as a shot across the SEC’s bow. While the case involved Treasury sanctions rather than securities law, the precedent weakens the notion that any government body can simply declare a protocol off-limits without naming a flesh-and-blood defendant. That matters for stablecoin issuers who route transactions through Tornado Cash-like privacy tools, for exchanges weighing whether to delist privacy coins, and for DeFi founders who fear their immutable contracts could be next. CFTC oversight of decentralized exchanges could also face new friction if judges keep insisting on identifiable counterparties before enforcement can bite. Traders, meanwhile, will test the edges—expect a short-term bump in on-chain mixing volume and privacy-token prices until the next regulatory salvo lands.

Bottom line: the Fifth Circuit just reminded Washington that code is not a citizen, and until Congress rewrites the statutes, regulators will have to aim at people, not protocols.

Delivery Not Required: Ninth Circuit Expands CFTC Reach with Monex Leverage Scheme

Wellermen Image Judge Hands CFTC Key Win Over Monex Leverage Scheme
The Ninth Circuit just handed the CFTC its first major appellate victory on retail leverage contracts, ruling that Monex’s financed metals trades fall squarely under the agency’s anti-fraud jurisdiction. The decision reverses a district-court dismissal and keeps alive a $290-million enforcement action against the California bullion dealer accused of hiding massive mark-ups and steering clients into losing bets.

Monex sold investors leveraged precious-metals positions with 20-to-1 financing. Customers never took delivery; instead, Monex held the metals in pooled accounts and charged undisclosed spreads that could exceed 15 percent. The CFTC sued in 2017, claiming the firm operated an unregistered retail commodity pool and misled customers about costs and risks. The lower court tossed the case, saying the trades were “actual delivery” contracts outside the agency’s reach. On appeal, a three-judge panel rejected that view, holding that because investors never received possession or control of specific metals, the transactions stayed within the CFTC’s statutory net.

The panel’s opinion is narrow but decisive: it defines “actual delivery” to require more than book-entry credits and concludes that Monex’s structure amounted to financed futures-like bets. The ruling does not declare Monex guilty; it simply reinstates the lawsuit and lets the CFTC pursue claims that Monex defrauded retail customers by burying costs and risk disclosures. Monex can still argue at trial that its customers understood the terms, but the procedural shield the company once enjoyed is gone.

In plain English, the court told leveraged-platform operators that if customers never get the actual asset in hand, the deal looks like a derivative and the CFTC can police it. That means any platform offering margin metals, crypto, or forex without true custody transfer now faces the same threat of enforcement and registration.

For crypto markets the precedent is immediate. Exchanges and DeFi protocols that let retail traders post small collateral for large notional exposure can no longer assume they sit outside CFTC oversight simply because the underlying asset is digital. Expect registration filings, tighter margin rules, and fresh scrutiny of “delivery versus settlement” claims. Stablecoin issuers and lending desks that finance token purchases will also face questions about whether they are, in effect, offering leveraged futures. Traders should read the opinion as a yellow light: leverage products just became more expensive to offer and slightly riskier to use.

The ruling tightens the noose on off-exchange leverage and signals that regulators, not platforms, will decide where the line between spot and derivative is drawn.

D.C. Circuit Rules CFTC Lacks Authority Over Non-Custodial Crypto Wallets

Wellermen Image Court Knocks CFTC Power Over Crypto Wallets

In a sharp rebuke to federal regulators, the D.C. Circuit ruled Thursday that the CFTC cannot force a non-custodial crypto wallet developer to register as a futures commission merchant simply because the software lets users trade derivatives. The 3–0 decision hands a clear victory to privacy-focused builders and sets new guardrails on how far the agency can stretch its oversight of decentralized tools.

The case began when Trevor Kitchen, creator of an open-source wallet, received a CFTC enforcement order claiming his code functioned like a brokerage because it routed users to perpetual-swap platforms. Kitchen argued the wallet never held customer funds or executed trades; it merely signed transactions the user chose. After the CFTC demanded registration and fines, Kitchen appealed. The three-judge panel agreed, finding that merely publishing software that interacts with blockchain protocols does not transform a coder into a regulated intermediary.

Writing for the court, Judge Wilkins held that the Commodity Exchange Act’s registration requirements hinge on “custody or control” of customer assets, not on the distribution of code. Because Kitchen’s wallet left private keys solely with users, the agency lacked statutory authority to treat him as a futures commission merchant. The ruling vacates the CFTC’s order and bars the agency from pursuing similar claims against other non-custodial developers unless Congress expands the statute.

In plain English, the decision draws a bright line: if you never touch customer money, you cannot be forced into the same regulatory box as Coinbase or Binance. That clarity reduces legal risk for wallet teams and DeFi front-ends that route trades without holding assets, but it leaves centralized exchanges and any firm promising “managed keys” fully exposed.

For markets, the ruling tilts power toward builders and away from the CFTC, at least until lawmakers weigh in. Stablecoin issuers and DEX aggregators that merely provide routing code gain breathing room, while traders may see more wallet options and fewer forced KYC flows. Yet the victory is narrow; the court left open the possibility that future facts—such as revenue-sharing with trading venues—could still trigger oversight.

Watch for copy-cat lawsuits testing the custody line, and expect the CFTC to lobby Congress for broader language; until then, code is still not brokerage.

×