Fifth Circuit Slams SEC Overreach, Crypto Wins Ground

Wellermen Image Court Slams SEC Overreach, Crypto Wins Ground

The Fifth Circuit just handed the SEC a sharp rebuke in a crypto enforcement case, ruling that the agency overstepped its authority by treating certain digital assets as securities without proving they met the legal test. The decision sends an immediate signal that regulators cannot simply label tokens as securities to expand their power — they must actually prove it in court.

The case began when the SEC brought enforcement actions against multiple crypto projects, claiming unregistered securities offerings. Defendants pushed back, arguing the tokens were commodities or utilities, not investment contracts under the Howey test. On appeal, the Fifth Circuit zeroed in on whether the SEC had met its burden to show that buyers reasonably expected profits derived primarily from the efforts of others — the critical prong of the securities test.

Judges ruled that the SEC’s evidence fell short, reversing key parts of the lower court’s findings. The agency cannot rely on vague marketing language or general industry hype to prove the “efforts of others” element. The decision shifts the advantage to defendants, requiring the SEC to present concrete, case-specific proof rather than blanket assertions. Exchanges, token issuers, and traders gain breathing room; the SEC’s enforcement hammer just got lighter.

In plain English, the court told the SEC it cannot treat “crypto” as a magic word that triggers securities law. Without clear evidence that investors were counting on company promoters for profits, tokens stay outside the agency’s reach. This raises the bar for enforcement and forces regulators to build stronger factual records before swinging.

For markets, the ruling tilts power toward decentralization. Projects that structure tokens as true utilities or commodities now carry less regulatory overhang, potentially unlocking liquidity and listings that had been frozen by enforcement fears. Stablecoin issuers and DeFi protocols gain indirect relief, as the decision narrows the gray zone where the SEC might claim jurisdiction. Traders should watch for a short-term sentiment bump, but remember the CFTC still holds sway over commodities — one agency’s loss is not a regulatory free-for-all.

The SEC will likely appeal or pivot tactics, but for now the gavel favors code over bureaucracy.
Appeals Court Rules Crypto Margin Like Oil Futures, Tauber Loses $4.2M Claim

Wellermen Image Regal Commodities Wins Appeal, Tauber’s $4.2 Million Crypto Claim Crushed
A New York appeals court just handed crypto trader Michael Tauber a stinging defeat, throwing out his bid to force Regal Commodities to pay $4.2 million in damages after a wild 2021 Bitcoin trade went south. The ruling matters because it shows courts are still treating crypto like any other commodity—subject to strict margin rules, not some Wild West free-for-all.

The lawsuit started when Tauber, trading through Regal, bought a massive Bitcoin futures position on a 10-to-1 margin. When the price plunged, Regal liquidated his account in a matter of minutes. Tauber sued, claiming the broker moved too fast and cost him millions. The trial court let the case proceed, but the Appellate Division reversed, ruling that Regal followed industry standards and had no duty to wait for a better price. The judges said Tauber knew the risks when he signed the margin agreement, and the law doesn’t protect traders from their own leverage bets.

Who wins? Regal and every broker who liquidates first and answers questions later. Who loses? Traders who think courts will second-guess fast-moving markets. The decision also sends a clear message: if you trade crypto on margin, your contract—not your feelings—sets the rules.

In plain English, the court told Tauber that once you agree to margin trading, you can’t sue when the broker protects itself. New York law treats crypto the same as oil or wheat futures. The ruling tightens the noose around any argument that crypto deserves special treatment or extra time before forced sales.

For markets, this strengthens exchange and broker hand, reduces litigation risk for platforms, and makes it harder for traders to claim foul when algorithms liquidate positions. It also pushes the SEC’s commodity classification of crypto one step deeper into precedent. Expect tighter margin agreements, faster liquidations, and fewer sympathetic ears for traders burned by leverage.

Bottom line: if you’re trading crypto on margin, the court just reminded you that speed kills—and the house always moves first.

Seventh Circuit Slams CFTC’s Broad Discovery in Kraft Wheat-Futures Probe

Wellermen Image Court Slams Brakes on CFTC’s “Fishing Expedition” Against Kraft
The Seventh Circuit just told the Commodity Futures Trading Commission it cannot subpoena every internal email, chat, and spreadsheet from Kraft Foods just because the agency smells manipulation. The ruling stops an unusually aggressive CFTC discovery push in its tracks and sends a blunt message: regulators must show they actually have a case before they get to ransack a company’s files.

The dispute started when the CFTC tried to prove that Kraft had squeezed the wheat futures market back in 2011. Instead of filing a normal enforcement action, the agency asked the district court for a sweeping subpoena covering years of trading records, internal communications, and even the personal notes of former employees. Kraft fought back, arguing the request was a fishing expedition designed to build a case from scratch rather than pursue one already formed. The district judge sided with the CFTC, but the Seventh Circuit reversed, holding that the agency’s statutory power to investigate does not grant it a blank check to rummage through corporate archives without credible evidence of wrongdoing.

Judges ruled that the CFTC must first establish a “reasonable basis” for believing Kraft violated the Commodity Exchange Act before demanding such extensive discovery. That standard is higher than the agency wanted, effectively forcing it to show its cards earlier in an investigation. Kraft and its parent Mondelēz win breathing room and a precedent that could slow similar broad subpoenas aimed at commodity traders and hedgers. The CFTC loses a procedural weapon it has used to pressure targets into settlement before formal charges are filed.

In plain English, the court is telling the agency it cannot treat every large trader as a suspect and demand a digital strip-search on a hunch. Companies now have stronger grounds to push back against open-ended document requests, and the CFTC will need tighter internal discipline before launching future fishing trips.

For crypto markets the ruling lands as a quiet but important check on CFTC reach. Enforcement staff at both the CFTC and the SEC have grown used to demanding mountains of Slack logs and wallet data from exchanges and DeFi protocols under the banner of “preliminary inquiries.” After this decision, those requests will face harder scrutiny if they rest on thin factual predicates. Token issuers, market makers, and trading desks now have a precedent to cite when regulators ask for everything without first spelling out a plausible theory of manipulation or fraud. Expect defense counsel to wave the Kraft opinion at agencies that treat broad discovery as the opening move rather than the endgame.

The case also highlights an old tension that is now front-and-center in digital-asset regulation: the line between legitimate oversight and fishing with a dragnet. If agencies want courts to keep granting expansive subpoenas, they will have to bring more than regulatory instinct to the table.

SEC Faces Fragmented Crypto Suits Across Three Districts as Consolidation Is Denied

Wellermen Image SEC Sued Over Multi-State Crypto Cases
Three investors have sued the SEC in separate federal courts, claiming the agency overstepped its authority when it pursued enforcement actions against unregistered digital-asset offerings. The lawsuits, filed in Illinois, California, and Pennsylvania, all challenge the same core question: whether the SEC can treat certain tokens as securities without first proving each token meets the Howey test. Because the cases raise identical legal issues, the plaintiffs asked a judicial panel to combine them into a single proceeding in Chicago.

The multidistrict litigation panel declined to consolidate. Writing for the panel, Judge Sarah Vance found that the three complaints, though similar in theory, rest on different facts, different tokens, and different stages of SEC investigations. Centralization, she ruled, would force judges to manage mismatched records and conflicting procedural schedules, outweighing any gain in efficiency. The panel left open the possibility that later overlap could justify limited coordination, but for now each case will proceed on its own docket.

The decision keeps three separate fronts open against the Commission at a moment when crypto issuers are testing every enforcement theory in court. Plaintiffs in each district can now press distinct arguments about fair notice, the reach of the agency’s rulemaking, and whether certain tokens function more like commodities than securities. For the SEC, the分散d docket means additional legal spend and the risk that one adverse ruling could ripple across the others through persuasive precedent rather than binding consolidation.

Exchanges and DeFi protocols gain breathing room. With no single nationwide order on the horizon, trading platforms can continue to list tokens whose status remains under litigation without an immediate threat of uniform liability. Issuers eyeing new offerings will watch each district’s discovery orders closely; an early win on the Howey question in Chicago or Philadelphia could chill further SEC enforcement and shift the balance of power toward industry self-regulation. Stablecoin sponsors, whose regulatory status often hinges on the same legal tests, will treat each case as a live stress test of enforcement reach.

The market should expect continued jurisdictional arbitrage until one appellate court or the Supreme Court steps in.

Grayscale Cuts ZCSH Price With 3-for-1 Split for Zcash ETF

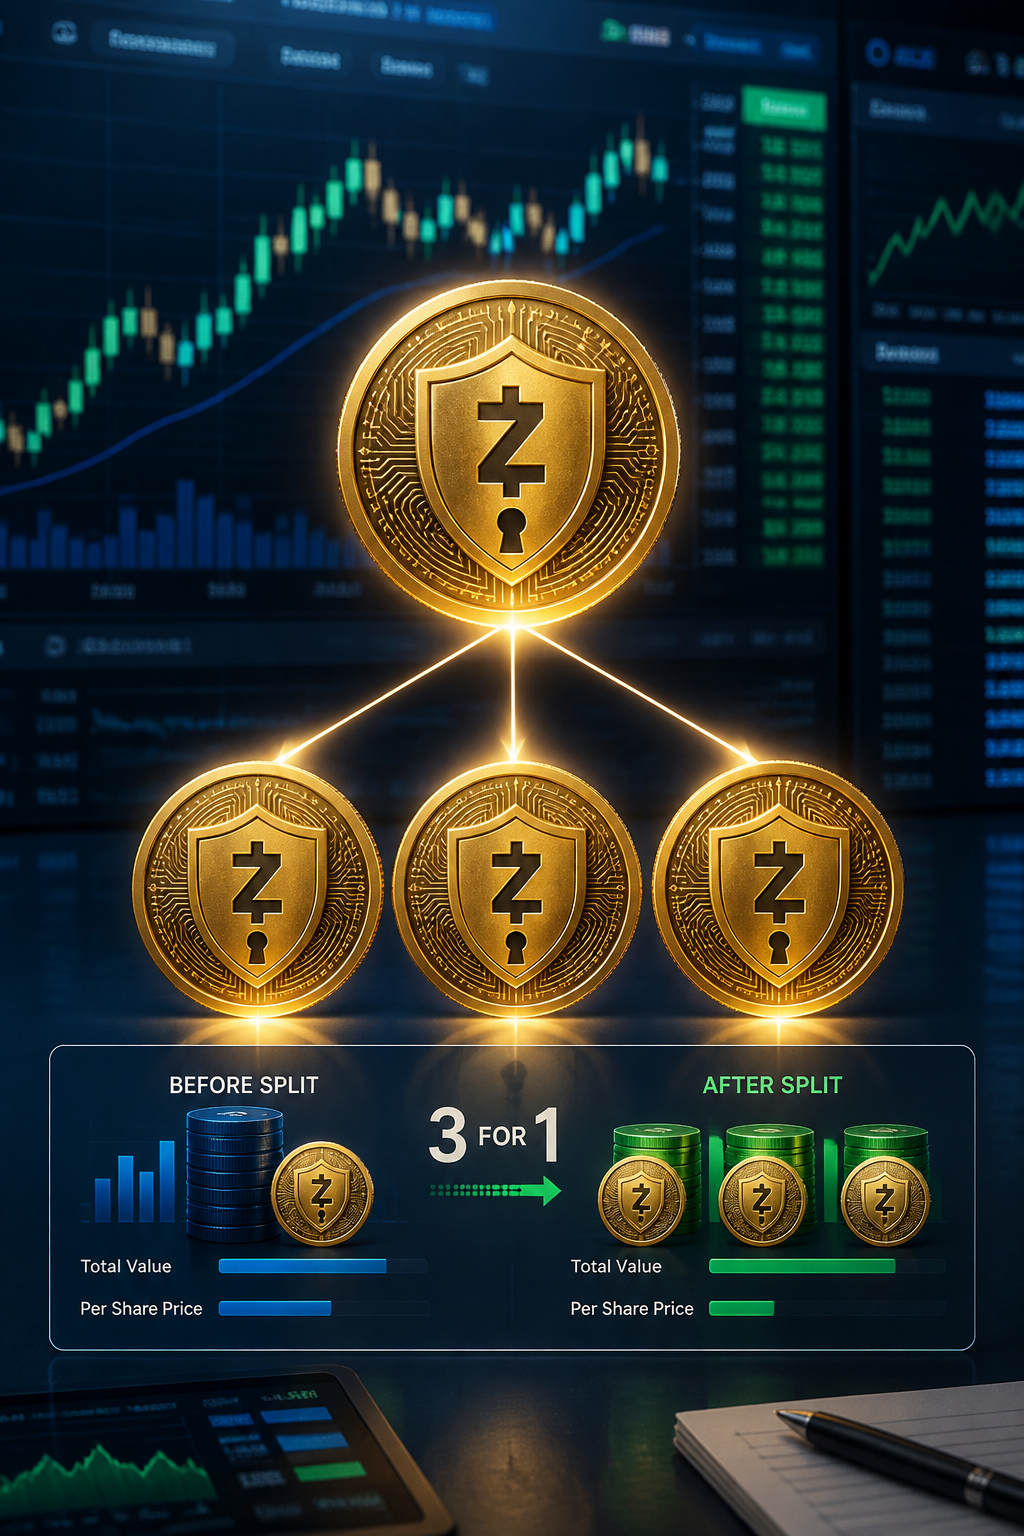
Grayscale’s Zcash exchange-traded fund is preparing a 3-for-1 forward share split less than two months after launching as the first Zcash exchange-traded product, according to the company. The split will reduce the fund’s per-share price while leaving the total value of investors’ holdings unchanged.

Share count to increase, value unchanged

Under a 3-for-1 forward split, each existing share will be converted into three shares. The market price of each share is expected to adjust proportionally, while the value of an investor’s overall position remains the same, excluding market movements.

For example, an investor holding one share before the split would hold three shares afterward. If the fund’s price were adjusted from $30 to approximately $10 per share, the value of the position would remain $30 at the time of the adjustment.

Lower price could improve access

The lower per-share price may make the Grayscale Zcash ETF, which provides brokerage-account exposure to Zcash (ZEC), more accessible to investors who prefer to purchase whole shares. The split does not change the fund’s underlying exposure to ZEC or alter the value of the assets represented by each investor’s position.

Zcash is a cryptocurrency designed to support privacy-preserving transactions. Through an exchange-traded product, investors can obtain exposure to the asset through traditional brokerage infrastructure rather than holding ZEC directly.

Grayscale’s move comes shortly after the product entered the market, highlighting the issuer’s effort to adjust the fund’s share structure as trading develops. The split itself does not represent a change in the fund’s investment strategy or the value of its underlying holdings.

Fifth Circuit Slams SEC’s Regulation-by-Enforcement in Major Crypto Win

Wellermen Image Judge Slams SEC’s “Regulation-by-Enforcement” Playbook in Major Crypto Win
The Fifth Circuit just handed the crypto industry its clearest rebuke yet of the SEC’s scattershot enforcement strategy, ruling that the agency cannot punish firms for violating rules that do not yet exist. In a blistering opinion that could reshape how digital assets are policed, the court said the SEC’s attempt to treat most tokens as unregistered securities fails basic fairness tests and chills innovation.

The case began when the Commission brought charges against a crypto exchange for allegedly selling unregistered securities without first spelling out what counted as a security. The lower court sided with the agency, but the appeals panel reversed, holding that the SEC must give fair notice before it can impose billion-dollar penalties. Judges wrote that “regulation by prosecution” violates due-process principles when the rules are as murky as the ones governing tokens today.

At the heart of the fight was the agency’s claim that once a token passes the Howey test it becomes a security—no matter how decentralized the network has become. The Fifth Circuit rejected that view, saying the SEC cannot simply declare something a security after the fact and then fine people for not guessing correctly. The decision gives exchanges and developers a stronger shield: if the agency has not issued clear guidance, it cannot punish later.

Plain-English translation: the court told the SEC it must write actual rules, not just sue first and explain later. That raises the bar for enforcement actions and makes it harder for the Commission to brand every token sale a securities violation without showing investors were misled.

For markets, the ruling weakens the SEC’s chokehold and boosts the CFTC’s hand in claiming oversight of non-security digital commodities. Stablecoin issuers gain breathing room, since the opinion signals courts will scrutinize broad enforcement theories. Exchanges now have precedent to push back against open-ended subpoenas, while DeFi protocols can argue their code alone does not equal an investment contract. Traders may interpret the decision as a green light for risk-on sentiment, though any relief rally will likely fade until the SEC either appeals or writes new rules.

Bottom line: the SEC’s favorite weapon—sue now, define later—just got blunted, and that changes the entire risk calculus for crypto firms and investors alike.

Ninth Circuit Revives CFTC Fraud Case Against Monex, Narrow Delivery Rule Expands Oversight of Leveraged Trading

Wellermen Image CFTC Wins Key Victory Over Monex in Ninth Circuit
The Ninth Circuit just handed the CFTC a major enforcement win by reversing a lower-court dismissal and allowing the agency to pursue fraud claims against Monex Credit Company and its affiliates. The ruling confirms that leveraged retail metals contracts fall squarely under the Commodity Exchange Act, giving the CFTC broad authority to police unregistered platforms that offer margin trading in gold and silver.

The dispute began when the CFTC sued Monex in 2017, accusing the firm of running an illegal off-exchange retail commodity operation and misleading customers about their ability to take physical delivery of metals. Monex argued that its “Atlas” program qualified for the CEA’s retail-customer exception because customers could technically request delivery. The district court agreed and dismissed the case, but the appeals court found that the exception applies only when delivery is “actually made,” not when the firm merely offers the theoretical possibility of delivery. Because 99 percent of Monex customers rolled their positions instead of taking metal, the court held that the exception was unavailable and the CFTC’s claims could proceed.

Judges next tackled the fraud allegations. They concluded that the complaint adequately pleaded that Monex knowingly made false statements about margin requirements and risk of loss, and that these statements were material to customers deciding whether to trade on leverage. With those claims revived, Monex now faces the prospect of injunctions, restitution orders, and civil penalties that could run into tens of millions of dollars.

In plain English, the decision closes a loophole that platforms have used to argue that any mention of “delivery” removes them from CFTC oversight. If a firm’s business model depends on customers never taking delivery, the Ninth Circuit says regulators can treat the contracts as futures or leveraged transactions subject to federal rules.

For crypto markets the ruling is a warning shot. Exchanges that let retail users trade digital assets with leverage but rarely see coins leave the platform now sit on similar legal ground. The decision broadens the CFTC’s reach over any token or commodity sold on margin where actual delivery is the exception, not the rule. Expect platforms to tighten delivery policies or restructure margin products, while stablecoin issuers watch closely—any arrangement that looks like leveraged exposure without routine redemption could invite parallel enforcement.

Traders should assume that the CFTC’s definition of “actual delivery” just got narrower, raising the odds that unregistered leverage desks will either register or shut down.

Court Expands CFTC’s Global Reach Over Offshore Crypto Spoofing

Wellermen Image Court Sides with CFTC in Kitchen Appeal, Tightens Derivatives Oversight
A divided D.C. Circuit just handed the Commodity Futures Trading Commission a sweeping victory in Trevor Kitchen’s appeal, confirming that the agency can reach beyond U.S. borders to discipline traders who manipulate global crypto-linked futures. The ruling tightens the regulatory net around offshore platforms and signals that courts will back the CFTC’s broad view of its own power.

The case began when the CFTC fined Kitchen $3 million and banned him from trading after alleging he spoofed order books on the Singapore-based exchange DFX, pushing Bitcoin perpetual-swap prices that feed into U.S. derivatives. Kitchen fought the penalty on jurisdictional grounds, insisting the trades never touched American servers or counterparties. The three-judge panel rejected that argument in a 2-1 decision, holding that any price distortion in contracts “directly linked” to U.S. markets gives the agency authority, even if the manipulative clicks occurred abroad.

Judges Wilkins and Rao formed the majority, finding that the Commodity Exchange Act’s “direct-and-significant” test reaches foreign conduct when it moves prices inside U.S. contracts. Judge Katsas dissented, warning that the majority’s logic could let regulators police every keyboard stroke on every offshore crypto venue. The upshot: Kitchen’s sanctions stand, and the CFTC’s green light to pursue similar cases is now stamped by the nation’s most important regulatory court.

In plain terms, the court said U.S. derivatives regulators can chase traders anywhere in the world as long as their actions ripple into American prices. That removes a major escape hatch for offshore platforms and traders who treat jurisdictional gray zones as free passes.

The decision hands the CFTC new leverage over crypto perpetual-swap desks, stablecoin issuers whose coins anchor offshore futures, and any exchange that offers products priced off U.S. reference rates. Expect compliance teams at Binance, Bybit and smaller DeFi-linked venues to revisit geofencing, KYC for high-volume traders, and liquidity-shaping algorithms that could be second-guessed thousands of miles away. Spot Bitcoin ETF desks, meanwhile, gain a measure of comfort knowing spoofing that distorts their underlying futures now carries enforceable penalties.

For traders and exchanges that still believe “if the servers are overseas, the rules don’t apply,” today’s opinion is a blunt reminder: U.S. derivatives prices are now an extraterritorial tripwire.

Bitcoin: UAE, Sweden Bust $7M Crypto Gang Linked to Contract Hits

UAE and Sweden Dismantle Crypto-Linked Money-Laundering Ring

Authorities in the United Arab Emirates and Sweden have arrested seven people in a joint operation targeting a Sweden-based criminal organization accused of laundering more than $7 million through cryptocurrency.

Seven Arrests in Joint Operation

The operation led to the arrest of the alleged leader of the laundering network in the UAE, along with six other suspected members of the organization in Sweden.

The group was reportedly based in Sweden but operated across jurisdictions, using digital assets to move and conceal proceeds linked to criminal activity.

Links to Wider Criminal Activities

Investigators also identified alleged connections between the organization and other serious crimes, including contract killings. The arrests are part of coordinated efforts by authorities in both countries to disrupt cross-border financial networks that rely on cryptocurrency.

The case highlights the continued use of digital assets in illicit finance while underscoring the growing cooperation between international law enforcement agencies targeting crypto-enabled criminal activity.

Ninth Circuit Rules Bitcoin Futures Are Commodities, Strengthening CFTC Authority

Wellermen Image CFTC Wins Ninth Circuit Crypto Futures Ruling
The Ninth Circuit just gave the CFTC a decisive win in its decade-old case against James Devlin Crombie, holding that his bitcoin futures contracts fell squarely under the agency’s authority. The decision strengthens regulators’ grip over crypto derivatives and sends a clear signal that U.S. courts will treat digital-asset futures as commodities, not clever workarounds.

Crombie ran a website that let customers bet on bitcoin’s price through “investor agreements” that functioned like futures. The CFTC sued in 2011, alleging he operated an unregistered exchange and committed fraud by misusing customer funds. After a district court granted summary judgment for the agency, Crombie appealed, arguing that bitcoin was not a commodity in 2011 and that the CFTC lacked jurisdiction. The three-judge panel rejected both claims outright, ruling that bitcoin qualified as a commodity under the Commodity Exchange Act even before the agency’s 2015 Bitcoin guidance, and that Crombie’s platform met the definition of a futures contract.

The court affirmed the lower-court injunction, monetary penalties, and restitution order against Crombie. The decision hands regulators a precedent they can cite against any unregistered crypto futures platform, while Crombie and similarly situated operators face steeper legal exposure and fewer avenues for appeal.

In plain English, the ruling confirms that if you offer leveraged bets on crypto prices without CFTC registration, you’re breaking the law today and were breaking it a decade ago. It removes any lingering doubt that bitcoin and similar digital assets are commodities subject to futures-market rules, and it narrows the gray zone where exchanges might claim they’re outside federal oversight.

For crypto markets, the ruling tilts authority further toward the CFTC on derivatives and away from arguments that digital assets are too novel for existing statutes. It raises the compliance bar for offshore and decentralized platforms that offer U.S. users leveraged exposure, and it could accelerate enforcement sweeps against unregistered futures desks. Stablecoins remain untouched here, but token classification risk rises for any project promising price exposure without registration. Exchanges and DeFi protocols that rely on jurisdictional ambiguity now face a precedent that treats functional equivalence to futures as legal equivalence.

Bottom line: regulators just picked up a sharper tool, and traders betting on regulatory blind spots just saw one close.

Court Strikes Down IRS Crypto Seizure, Redrawing the Forfeiture Playbook

Wellermen Image COURT GUTS IRS CRYPTO SEIZURE—AND SHAKES THE ENTIRE PLAYBOOK
The D.C. federal court just gutted an IRS crypto seizure that targeted 24 wallets allegedly tied to a $1.7 billion dark-web narcotics ring. The ruling says the government’s forfeiture complaint was so thin it failed to state a plausible claim, forcing the IRS to start over or walk away. In one stroke, the decision re-draws the line between suspicion and proof when agencies chase digital assets.

The case began when the IRS-CI traced bitcoin payments to Silk-Road-style markets and applied for warrants to seize 24 wallets. Prosecutors filed an in-rem forfeiture action under the Civil Asset Forfeiture Reform Act, arguing the coins were proceeds of drug trafficking. The wallets’ unknown owners never appeared, but the court still scrutinized the complaint on the merits. Judge Dabney L. Friedrich found that the government’s narrative rested on blockchain clustering guesses and a single alleged transaction link; that, she held, does not meet even the modest “plausibility” standard required to survive a motion to dismiss. The opinion stresses that civil forfeiture pleadings must spell out facts showing a direct, substantial connection between the coins and the crime—not just guilt by digital proximity.

The practical result is straightforward: the 24 wallets are no longer frozen under this complaint. The government can amend and refile, but any new filing will have to show a clearer money-trail rather than relying on algorithms and heuristics. Claimants who stayed silent before now have precedent suggesting courts will demand more than metadata before signing off on seizures.

In plain English, the court told federal agents they cannot treat blockchain analytics like a subpoena. To grab crypto, investigators must still connect specific coins to provable crimes with the same rigor they would use for bricks of cash or bank accounts. That raises the bar for future IRS and DOJ crypto cases and signals to exchanges and DeFi protocols that compliance departments may face fewer panicked takedown requests.

The decision also lands at a moment when the SEC and CFTC are jockeying for crypto oversight. A judiciary unwilling to rubber-stamp forfeitures indirectly limits how much leverage enforcement agencies can wield through asset grabs, shifting the balance toward due-process arguments that exchanges and token issuers can cite when regulators come knocking. Stablecoin issuers and mixers now have fresh authority to push back against broad “tainted wallet” lists.

For traders and protocols, the takeaway is double-edged: stronger evidentiary shields reduce the odds of sudden wallet blackouts, yet the ruling does nothing to curb the agencies’ appetite—only their shortcuts. Expect more detailed complaints, longer investigations, and a higher premium on solid record-keeping. The wallets may be safe for now, but the hunt is far from over.

SEC Wins Round as Binance Case Survives First Major Test; Core Charges Stand

Wellermen Image SEC Stuns Crypto: Binance Case Survives First Major Test
A federal judge in Washington just refused to throw out the SEC’s sweeping lawsuit against Binance, letting the agency’s core charges stand and sending a clear signal that crypto exchanges remain squarely in the regulator’s crosshairs. The decision keeps the case alive at a moment when traders had started betting the agency’s reach was shrinking.

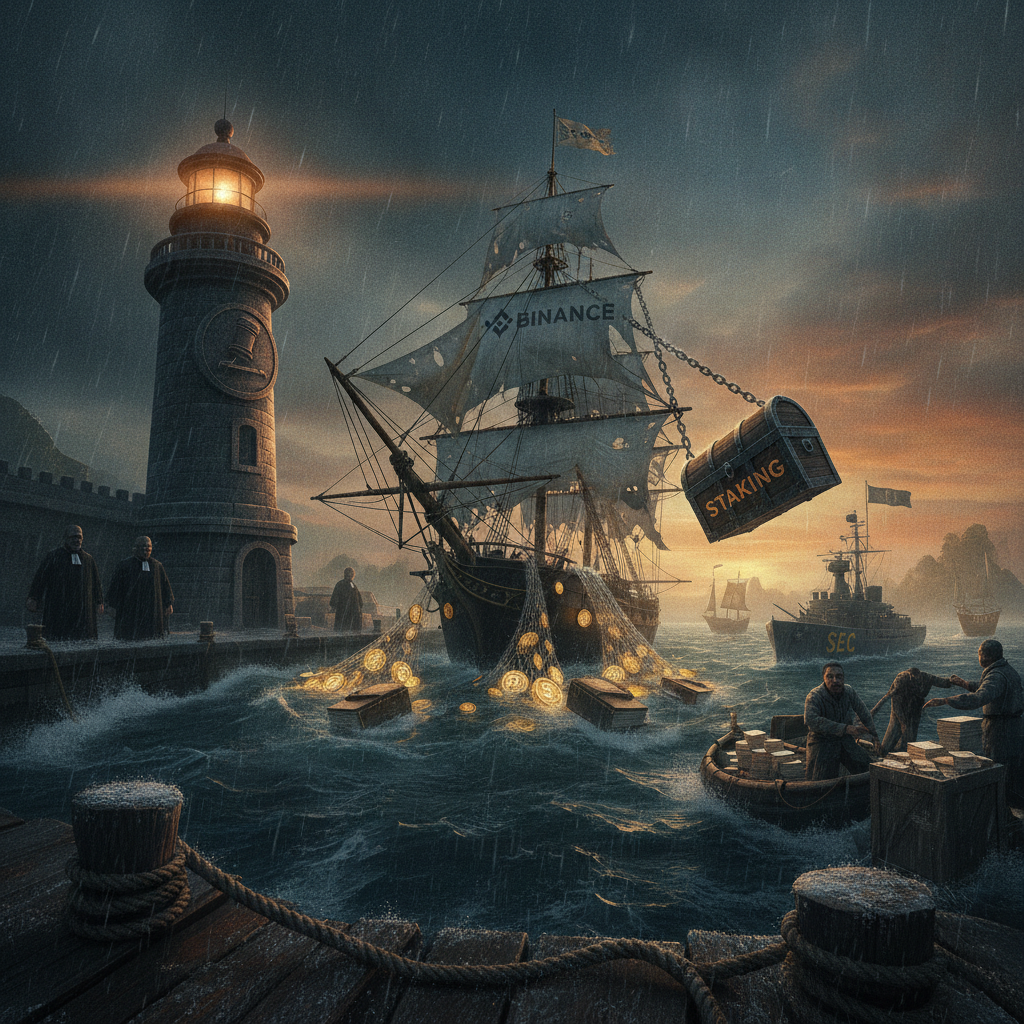
The suit began last summer when the SEC accused Binance and its U.S. affiliate of operating unregistered exchanges, offering unregistered securities, and commingling customer funds—an allegation that rattled markets and prompted billions in withdrawals. Binance asked the court to dismiss most claims, arguing that crypto tokens are not securities and that the agency had stretched old laws to cover new technology. Judge Amy Berman Jackson kept the majority of the charges intact, ruling that the SEC had plausibly alleged Binance offered investment contracts under the well-known Howey test, and that the platform’s staking program could qualify as a security. She tossed only a narrow slice of the complaint dealing with simple-token resales.

For crypto markets, the ruling tilts power back toward the SEC at a time when the agency’s authority looked newly vulnerable. The decision preserves broad enforcement leverage over spot trading platforms and keeps the threat of large penalties alive, which could push more volume offshore or deeper into DeFi. Stablecoin issuers and token projects now face renewed classification risk: if judges treat staking rewards or exchange listings as securities, projects built on those mechanics must prepare for registration or enforcement. Exchanges that had hoped for a lighter touch will likely accelerate lobbying and legal spend, while traders price in higher compliance costs and possible delistings.

The message is blunt: until Congress draws clearer lines, judges will let the SEC keep swinging.

Bitcoin Inflows Hit $159M as Zcash ETF Attracts $46.6M

U.S. Bitcoin ETFs Return to Inflows as Zcash Fund Attracts $46.56 Million

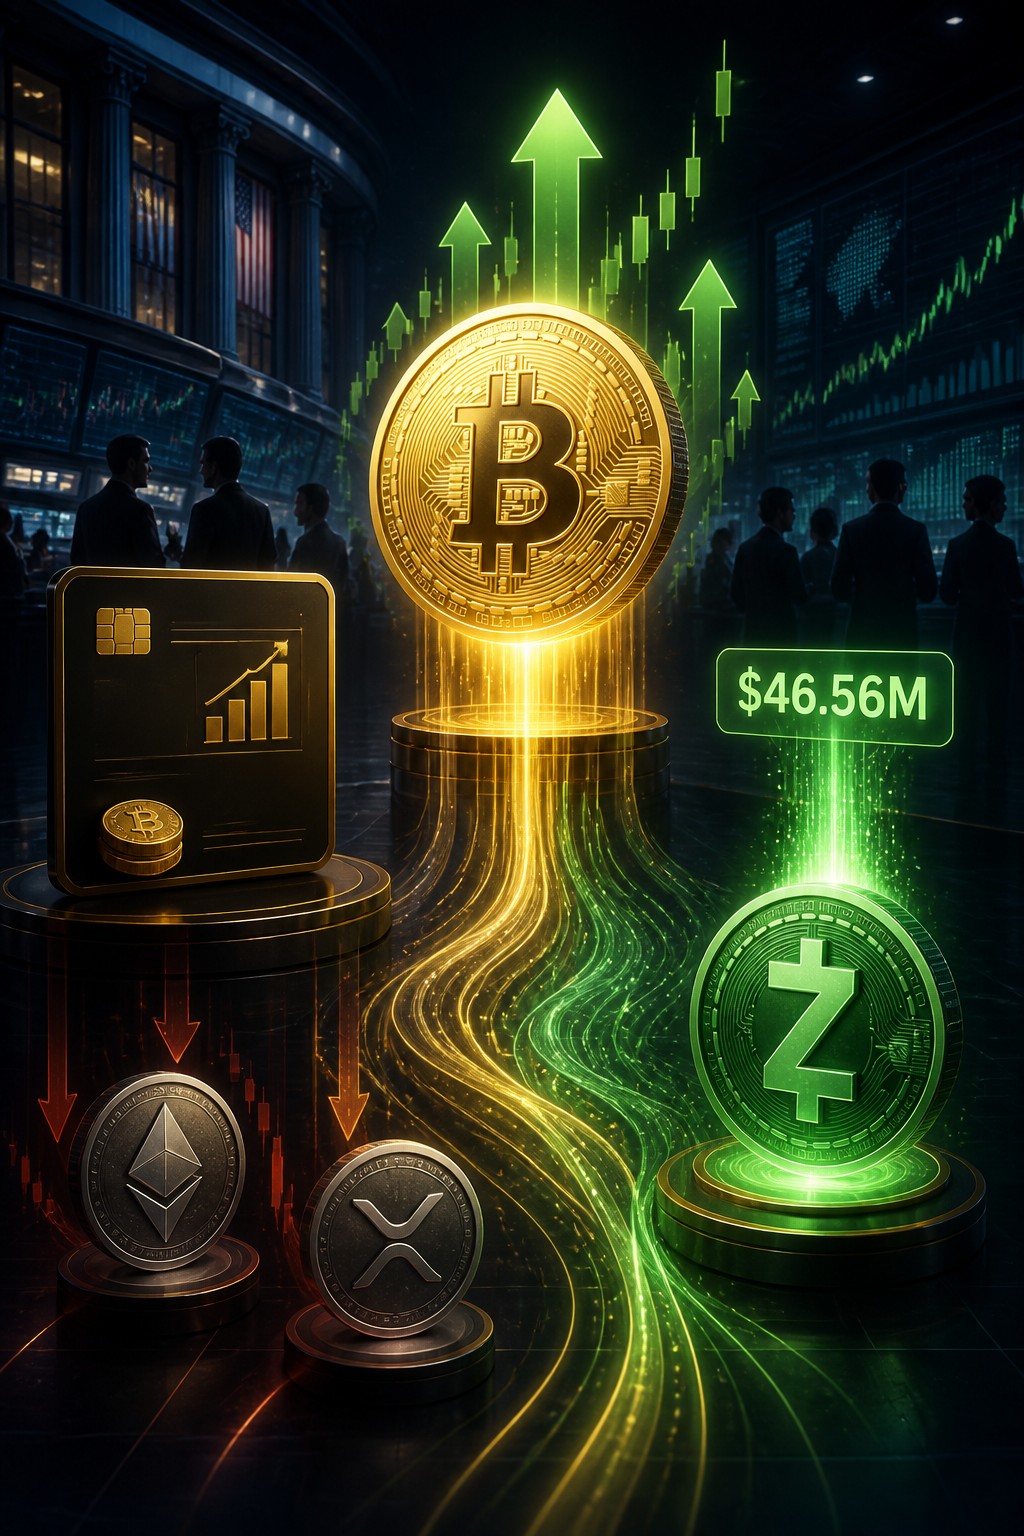
U.S. spot bitcoin exchange-traded funds recorded $159.45 million in net inflows on Thursday, reversing recent weakness as BlackRock’s iShares Bitcoin Trust (IBIT) led the rebound. Ether and XRP funds continued to see outflows, while a recently launched Zcash ETF attracted $46.56 million in new capital.

BlackRock’s IBIT Leads Bitcoin ETF Rebound

The return to positive flows marks a recovery for the U.S. bitcoin ETF market after a period of investor withdrawals. BlackRock’s IBIT accounted for the largest share of Thursday’s inflows, highlighting continued institutional demand for bitcoin exposure through regulated investment products.

Spot bitcoin ETFs allow investors to gain exposure to bitcoin through traditional brokerage and market infrastructure without directly holding the cryptocurrency.

Ether and XRP Funds Remain Under Pressure

While bitcoin funds attracted fresh capital, exchange-traded funds linked to ether and XRP continued to experience outflows. The divergence suggests that investor demand remained concentrated in bitcoin rather than extending broadly across digital-asset funds.

Zcash ETF Draws Fresh Capital

The recently launched Zcash ETF recorded $46.56 million in inflows on Thursday. Zcash is a privacy-focused cryptocurrency designed to support shielded transactions, and the fund’s inflows indicate early investor interest in gaining exposure to the asset through an exchange-traded product.

The contrasting flows across bitcoin, ether, XRP and Zcash funds underscore the varied appetite for cryptocurrency investment products as institutional participation continues to develop.

Delaware Court Rules DFT Token Subscription Binding; Investor Owes $2.5M Despite No Registration Condition

Wellermen Image Court Slams Delaware Crypto Startup Over Failed Token Deal
Delaware’s top business court just told two crypto entrepreneurs they cannot sue their way out of a bad deal with an investor who walked away from a $2.5 million token purchase. The ruling tightens the screws on how Delaware companies must honor their private-placement promises and signals that judges will not rescue founders when token sales collapse.

Diamond Fortress Technologies and its founder Charles Hatcher II sued an investor who signed a subscription agreement to buy $2.5 million worth of DFT tokens but never wired the cash. The investor argued the deal was conditioned on an SEC-compliant resale registration that never happened. The Delaware Superior Court ruled that the subscription contract was clear, binding, and did not make token registration a condition of payment. Because the investor failed to pay, the court entered judgment against him for the full amount plus interest.

The decision hands a clear win to the startup and its founder, while sending a warning shot to token buyers who try to back out by claiming regulatory hurdles that the paperwork never required. It also tightens Delaware’s stance that private-placement contracts will be enforced as written, even when the underlying tokens later face SEC scrutiny or exchange-listing problems.

For crypto markets, the ruling underscores that Delaware courts will treat token subscription agreements like any other commercial contract, increasing enforcement risk for buyers and giving issuers stronger collection tools. It also suggests that future token purchasers may demand explicit escape clauses tied to SEC or exchange approvals, or else face the same straight-forward liability. Exchanges and DeFi protocols that custody or list tokens issued under Delaware entities now have another precedent showing that downstream regulatory issues do not automatically void upstream payment obligations.

The message for traders and issuers alike: paper still rules, and Delaware judges are not in the business of rewriting token contracts when the market turns.

D.C. Circuit Orders SEC to Revisit Grayscale’s Spot Bitcoin ETF Rejection

Wellermen Image Grayscale Beats SEC, Wins Spot-Bitcoin ETF Review

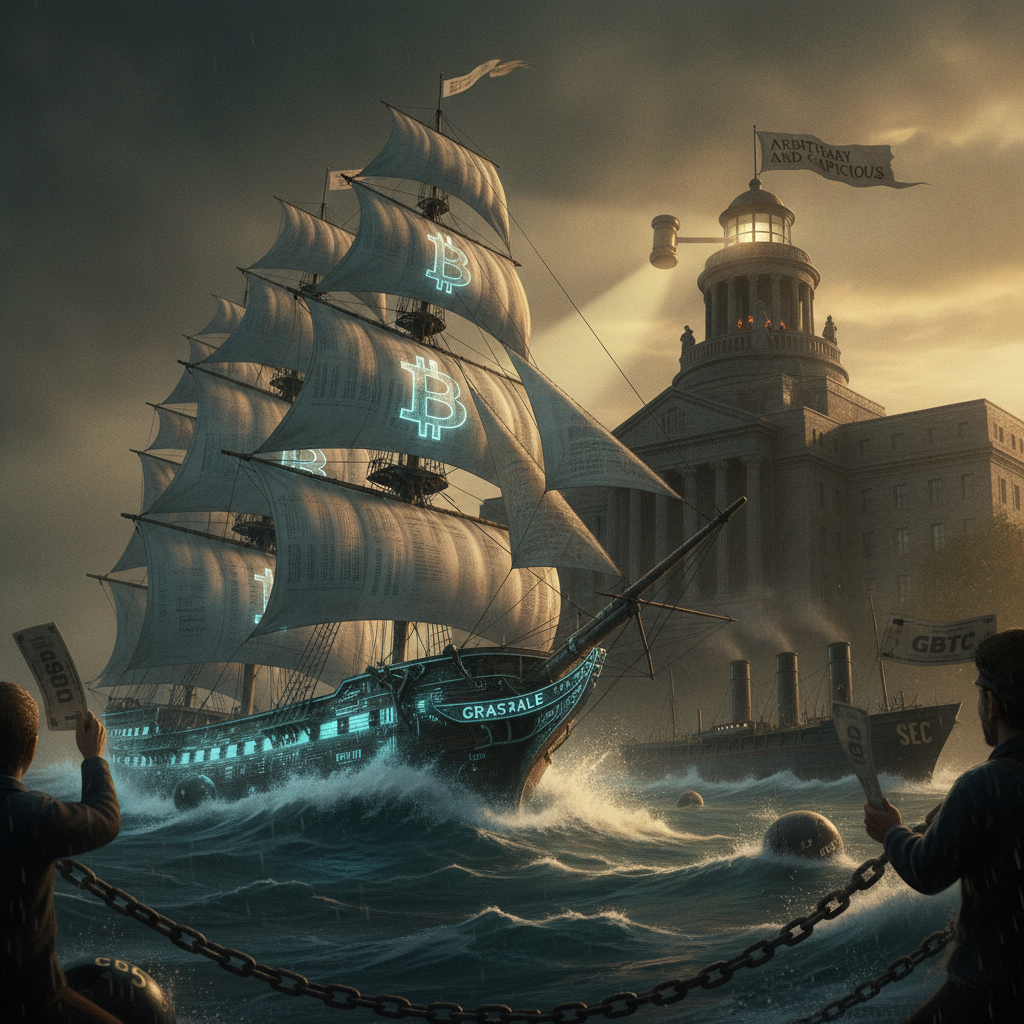
The D.C. Circuit just ordered the SEC to revisit its 2022 rejection of Grayscale’s spot Bitcoin ETF, delivering the first major legal defeat to Gary Gensler’s campaign against crypto investment products. The unanimous three-judge panel said the agency failed to explain why a futures-based Bitcoin ETF is kosher but a spot version is not, exposing a glaring inconsistency in the Commission’s reasoning. Markets are already pricing in higher odds of approval and a fresh wave of institutional money.

Grayscale filed its petition after the SEC turned down its application to convert the Grayscale Bitcoin Trust into an exchange-traded product. The trust, already holding roughly $16 billion in actual Bitcoin, argued that listing shares on an exchange would give investors the same exposure with tighter spreads and daily redemptions. The SEC’s stated worry was that spot Bitcoin markets are uniquely susceptible to fraud and manipulation, yet it had approved futures-based ETFs on the theory that Chicago-regulated futures prices are “sufficiently correlated” with spot prices to deter manipulation. Grayscale asked why the same correlation logic could not protect a spot product.

Writing for the court, Judge Rao ruled that the SEC’s refusal to square these two positions was “arbitrary and capricious.” The agency offered no data showing futures ETFs are meaningfully harder to manipulate than spot ETFs, nor did it consider whether the CME’s surveillance-sharing agreements with spot platforms could close the gap. Because the Commission must treat similar cases alike, the court sent the order back for a fresh look, stopping short of ordering immediate approval.

In plain English, the ruling does not green-light a spot ETF tomorrow, but it strips the SEC of its favorite talking point—that spot Bitcoin products are categorically too risky. If the Commission cannot produce a coherent distinction on remand, it will either have to approve Grayscale’s filing or risk another loss that further erodes its authority over crypto listings.

The decision shifts power toward exchanges and issuers who can now cite judicial skepticism of the SEC’s “Bitcoin-is-different” rationale. Spot products suddenly look less like regulatory poison and more like an inevitable next step, boosting confidence that CFTC oversight of futures markets can serve as a compliance bridge. Traders are already repricing GBTC’s discount, while DeFi protocols that rely on BTC collateral may gain a regulated on-ramp if creation-redemption mechanics are finally cleared.

Expect the SEC to stall, appeal, or impose new conditions; none of those moves erases the fact that the judiciary just forced the agency to justify its crypto policy in public instead of by press release.

×