Texas Appeals Court Orders Fast Hearing in Envy Blockchain Mining Permit Battle

Wellermen Image Court Slams Brakes on Texas Crypto Mining Dispute

A Texas appeals court has handed Envy Blockchain and its partners a partial reprieve in their fight to keep mining equipment online. The decision matters because it shows how state courts—not federal regulators—are increasingly deciding what counts as a “good neighbor” in crypto mining, and those rulings can shut down or green-light operations overnight.

The fight started when El Paso homeowners complained about noise, vibrations, and flashing lights from Envy’s facility, prompting the city to revoke the company’s permits. Envy raced to state district court for an emergency order to keep mining while it challenged the revocation, but the trial judge refused. Envy then asked the Eighth Court of Appeals to compel the lower court to act. The appeals court granted partial mandamus relief, ordering the trial judge to hold an immediate hearing and decide whether a temporary injunction should issue, but stopped short of forcing the permits back into place on its own.

The three-justice panel ruled that Envy has a clear right to have its injunction request heard quickly, yet the company must still prove—under Texas rules—that it faces imminent harm and that the balance of equities favors keeping the rigs running. The city keeps the upper hand for now: its permit revocation stands unless and until a trial judge says otherwise. For Envy and its landlord, NV Landco, the clock is ticking; every day without power means lost Bitcoin revenue and mounting lender pressure.

In plain English, the court told both sides to get back in the ring and fight it out in the trial court instead of letting the dispute die in procedural limbo. Texas procedural law, not federal securities or commodities rules, is what now dictates whether the mining site stays dark.

That reality highlights a widening gap between federal crypto policy and state-level land-use fights. While the SEC and CFTC spar over token classifications, municipal noise ordinances can sideline millions in hash-rate without ever touching a whitepaper. Exchanges and DeFi protocols that rely on steady U.S. hash-power could see regional supply shocks if similar suits proliferate.

Traders should watch Texas dockets as closely as they watch Federal Reserve statements; one adverse noise ruling can cut hashrate faster than any enforcement action.
Seventh Circuit Blocks CFTC’s Fast-Track Writ in Kraft/Mondelēz Spoofing Probe

Wellermen Image COURT HANDS CFTC A RARE PROCEDURAL DEFEAT
The Seventh Circuit has just told the CFTC to slow down. In a terse, unpublished order, the court denied the agency’s emergency petition for a writ of mandamus that would have forced Kraft and Mondelēz to turn over massive volumes of documents in the long-running “spoofing” probe. The ruling underscores that even a muscular regulator can be reined in when it tries to skip the line.

The CFTC launched its investigation after alleging that the food giants manipulated wheat-futures prices by placing and then canceling large orders—an echo of the “spoofing” cases that sent Navinder Sarao to prison. When Kraft and Mondelēz resisted the agency’s sweeping subpoena, the CFTC ran to the district court for enforcement; losing there, it then asked the Seventh Circuit to bypass normal appeals and issue an extraordinary writ. The three-judge panel said no, leaving the fight to grind through ordinary channels.

That means months—possibly years—of additional discovery fights, cost-shifting motions, and privilege logs before the agency can even think about an enforcement complaint. For companies under the CFTC’s microscope, the message is clear: delay is still a viable defense.

In plain English, the court told the CFTC it cannot leapfrog the judicial process just because a case involves commodities. The agency must still prove its enforcement theories under the same rules that govern every other civil litigant.

For crypto markets the precedent is double-edged. On one hand, it signals that courts will not rubber-stamp every CFTC data grab—an encouraging sign for DeFi protocols and offshore exchanges that fear extraterritorial sweeps. On the other, the underlying legal theory—that massive, quickly canceled orders can count as manipulation—remains intact and could yet be aimed at crypto-market makers or automated trading desks. Traders and token issuers should expect continued scrutiny, but with slightly better procedural armor.

Bottom line: regulators just learned they can still lose on procedure, but the substantive risk for aggressive trading strategies in futures—or their crypto analogs—has not gone away.

Replay Attacks Grow as BIP-110 Backers Brand Bitcoin ‘Spamcoin’

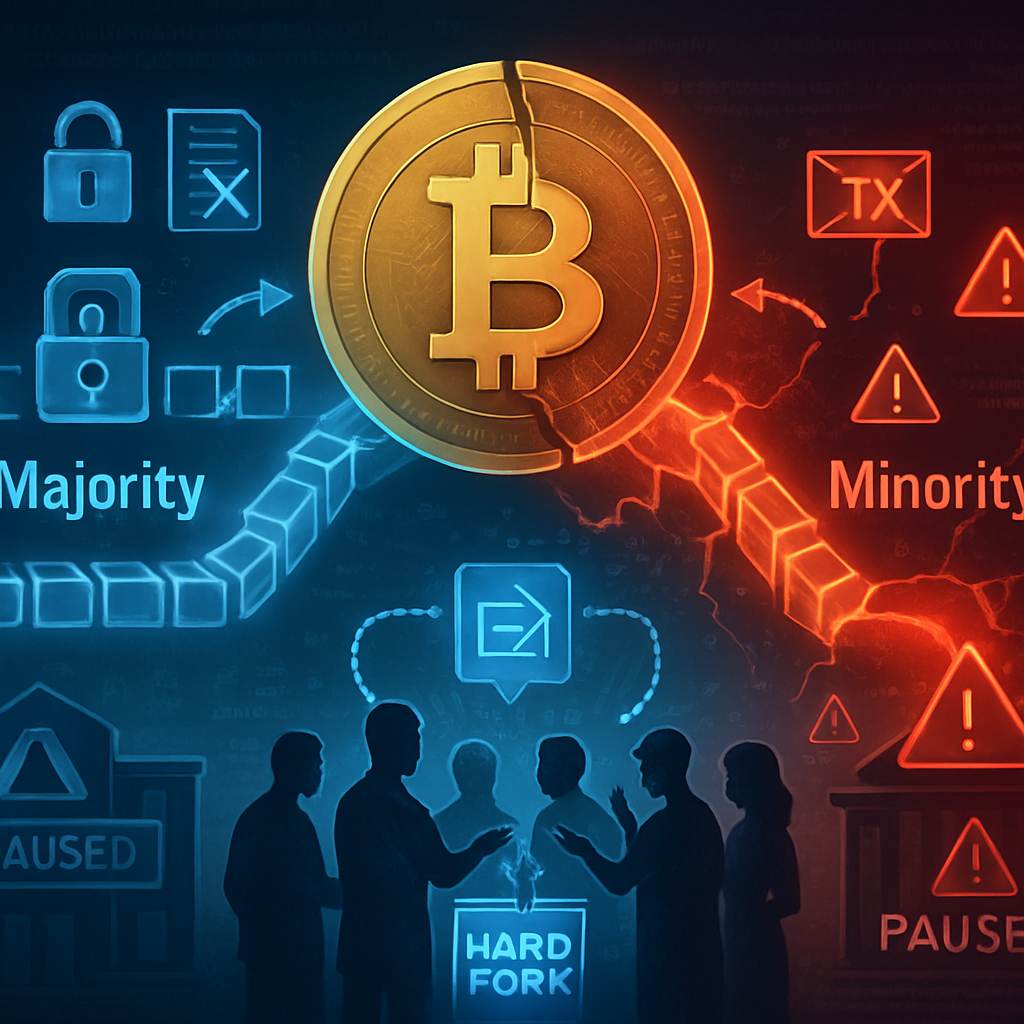
A push to revive the stalled “BIP-110” fork has reignited debate over replay attacks in Bitcoin, a risk where a transaction broadcast on one chain can be copied and executed on another. The discussion, involving Bitcoin developer Luke Dashjr and other backers of the proposal, centers on advancing a hard fork on a minority chain—raising questions about replay protection, user safety, and how exchanges might respond if a split occurs.

Why Replay Attacks Are Back in Focus

Replay attacks occur when two blockchains share compatible transaction formats and signature rules after a split. Without strong replay protection, a transaction intended for one chain may also be valid on the other, allowing it to be “replayed.” For users, wallets, and service providers, this can lead to unintended fund movements, double-spends across chains, and operational disruption.

The renewed concern follows talks among BIP-110 supporters about proceeding with a hard fork that would update consensus rules on a minority chain. If the technical design lacks robust, default-on replay protection, any subsequent chain split could expose participants to cross-chain transaction leakage until services implement mitigations.

What Is at Stake With a Minority-Chain Fork

Hard forks that do not achieve overwhelming miner, node, and ecosystem alignment tend to create minority and majority chains. The minority chain carries distinct risks:

  • Transaction Safety: Absent deliberate replay protection, valid transactions may propagate between chains, potentially confusing wallets, exchanges, and payment processors.
  • Market and Liquidity Impact: A split can fragment liquidity and price discovery, with exchanges often pausing deposits and withdrawals while they assess stability and implement safeguards.
  • Operational Complexity: Services must update infrastructure, carefully handle deposits, and distinguish coins across chains to avoid accidental replays.

Backers of the BIP-110 effort have argued for rule changes on the minority chain. However, details on activation parameters, replay protections, and ecosystem coordination remain central to whether the proposal can proceed without significant user risk.

Replay Protection: Lessons From Past Chain Splits

Historical precedents highlight the importance of proactive defenses:

  • Ethereum (2016): Following the DAO fork, both Ethereum and Ethereum Classic initially faced replay issues due to shared transaction validity. Tooling and protocol-level distinctions were later introduced to reduce replay vectors.
  • Bitcoin-Derived Forks (2017–2018): Projects such as Bitcoin Cash implemented new signature hashing (e.g., SIGHASH_FORKID) and other changes to ensure that transactions on the new chain would be invalid on the original chain, and vice versa.

Best practice in modern hard forks is to introduce strong, default-on replay protection so transactions cannot be inadvertently broadcast to both networks. Clear communication from developers and exchanges, plus wallet updates that segregate coins and transaction formats, are typically essential to a smooth transition.

Outlook

As discussion around a BIP-110 revival continues, the key focus for developers and market participants is whether any proposed fork will include robust replay protection and a coordinated rollout plan. Until technical specifications, activation thresholds, and ecosystem support are clarified, exchanges and wallets are likely to proceed cautiously to mitigate replay risk in the event of a split.

No activation timeline has been finalized publicly. Market participants will be watching for concrete technical details, industry coordination, and explicit replay-protection mechanisms before assessing the potential impact of a BIP-110 chain on users and liquidity.

Judge Lifts 23-Year SEC Block Against Bilzerian, Clears Path to Seize Offshore Assets

Wellermen Image JUDGE BLOWS UP BILZERIAN’S 23-YEAR BLOCKADE ON SEC ENFORCEMENT
A federal judge just shattered a two-decade legal shield that had frozen the SEC’s ability to collect nearly $80 million in penalties from notorious corporate raider Paul Bilzerian. The ruling, issued Tuesday in Washington, D.C., lifts a 2001 injunction that had blocked the Commission from pursuing Bilzerian’s hidden assets, including a private island and millions in offshore trusts. The decision removes a major obstacle to enforcement against high-net-worth defendants who use complex structures to dodge judgments.

The case began in 1989 when the SEC sued Bilzerian for securities fraud tied to his hostile takeover of several public companies. A jury found him liable, and the court ordered him to pay $79.8 million in disgorgement and penalties. By 2001, Bilzerian had transferred assets to trusts in the Cook Islands and the Isle of Man, claiming he could no longer pay. In response, he obtained a sweeping injunction that barred the SEC from filing new actions or enforcing existing judgments against him or his family without court permission. That order effectively froze enforcement for more than two decades.

On Tuesday, Judge Royce Lamberth ruled that the injunction had served its purpose and no longer protected any legitimate interest. He found that Bilzerian’s trust arrangements were designed to evade collection rather than to preserve assets for creditors. The court dissolved the injunction, cleared the way for the SEC to pursue additional enforcement actions, and gave the agency authority to seek turnover of assets held in foreign trusts. Bilzerian and his associates lose the procedural shield they relied on; the SEC and future defrauded investors gain renewed collection power.

The decision reframes the balance of power between regulators and sophisticated defendants. Courts have historically been reluctant to unwind decades-old injunctions, but Judge Lamberth signaled that asset-protection schemes will not receive indefinite sanctuary. This lowers the practical barrier for the SEC to chase hidden wealth, especially when that wealth sits in offshore vehicles.

For crypto markets the ruling carries direct implications. Enforcement officers at the SEC have already signaled they intend to treat digital-asset wallets and DeFi protocols as the next frontier for collection. If a defendant can no longer hide behind an old injunction, exchanges and protocols that custody assets for sanctioned or judgment-proof individuals could face subpoenas or asset-freeze orders. Stablecoin issuers and on-ramp services may now need to run more rigorous sanctions and judgment checks, because the legal cost of ignoring an unpaid SEC award just increased. Traders holding tokens in offshore mixers or privacy wallets should treat the ruling as a warning: the window for asset shielding is narrowing, not widening.

The message is blunt: yesterday’s legal barricades won’t stop today’s collection efforts.

Supreme Court Narrows SEC’s Crypto Reach as DeFi Gains Ground

Wellermen Image COURT SLAPS SEC ON WRISTS, EXPANDS DEFINITION OF COMMODITY
Supreme Court’s latest decision narrows the SEC’s reach over digital assets, handing DeFi platforms and token issuers a major legal win. The ruling clarifies that many tokens and decentralized protocols fall outside traditional securities law, shifting the regulatory battlefield to the CFTC and state attorneys general.

The case began when the SEC sued a decentralized finance protocol alleging unregistered securities offerings and operating an unregistered exchange. Lower courts split on whether the protocol’s native token met the Howey test for investment contracts. The Supreme Court accepted the appeal to resolve whether purely algorithmic or governance tokens, without centralized profit-sharing promises, could still be deemed securities.

Writing for the majority, the Court held that a token is not a security unless investors reasonably expect profits derived predominantly from the entrepreneurial or managerial efforts of others. The justices rejected the SEC’s broader “ecosystem efforts” theory, ruling that mere price appreciation tied to overall market adoption or community development does not satisfy Howey. The decision also narrowed the definition of “exchange” under the Securities Exchange Act to exclude protocols lacking custody or discretionary control over user funds.

The immediate winners are decentralized autonomous organizations, liquidity providers, and token holders who now face lower enforcement risk from the SEC. Losers include the agency itself, whose enforcement-first strategy suffered a public rebuke, and centralized exchanges that had already delisted tokens under regulatory pressure. State regulators and the CFTC are expected to step into the gap, particularly around commodities classification and consumer protection.

In plain English, the Court told the SEC it cannot label every token a security just because someone might make money from holding it. The decision forces regulators to prove specific promises of managerial profits rather than relying on vague ecosystem narratives. Protocols that stay truly decentralized and avoid marketing token price appreciation as an investment strategy now operate in a clearer legal lane.

The ruling shifts authority toward the CFTC on commodities grounds while leaving stablecoins and custodial exchanges exposed to future enforcement. Decentralized protocols gain breathing room, but centralized entities face heightened compliance costs if they cannot prove non-security status. Traders will likely reprice tokens previously viewed as high-risk, though volatility may spike as markets digest enforcement uncertainty.

This decision opens a narrow window for compliant DeFi growth before Congress or statehouses fill the regulatory vacuum.

Court Rules: If It Looks Like a Futures Contract, the CFTC Regulates It

Wellermen Image Judges Hand CFTC A Win Over Family Trust in Derivatives Dispute
A federal appeals court ruled that the Commodity Futures Trading Commission may pursue enforcement actions against private trusts and individuals who trade in commodity derivatives, even when those trades occur outside traditional exchange venues. The decision strengthens the CFTC’s reach into decentralized or off-exchange trading and signals that informal investment vehicles will not escape federal oversight.

The Conway Family Trust challenged a CFTC enforcement order after its trustees placed leveraged commodity bets that the agency deemed off-exchange futures contracts. The trust argued that its activities fell outside CFTC jurisdiction because the contracts were bilateral, non-standardized, and executed away from any designated contract market. The Seventh Circuit rejected that view, holding that the statutory definition of “contract of sale of a commodity for future delivery” covers any arrangement that functions economically like a futures contract, regardless of form or venue. By focusing on economic substance rather than paperwork, the court aligned with the CFTC’s long-standing position that leverage and future settlement create regulatory exposure.

The ruling hands the CFTC a clear procedural victory: the agency can now cite this precedent when it targets family offices, hedge funds, or DeFi protocols that structure commodity exposure through bespoke instruments. Private trusts lose the ability to claim safe-harbor status simply by avoiding exchanges or standardization. Meanwhile, traders who rely on over-the-counter commodity derivatives must either register with the CFTC or redesign their structures to fall outside the economic definition of futures—an increasingly narrow path.

In plain English, the court told investors that if it walks like a futures contract and settles like a futures contract, the CFTC can regulate it—even if lawyers label it something else. That removes a layer of legal insulation many sophisticated players had counted on when they moved trading offshore or on-chain.

The decision widens the CFTC’s footprint at the exact moment crypto-native protocols are experimenting with tokenized commodity exposure and decentralized perpetual-swap venues. Stablecoin issuers that embed leveraged commodity exposure inside their products, or DeFi exchanges that clear synthetic futures, now face a clearer enforcement roadmap. Exchanges themselves may feel indirect pressure: as the agency’s reach grows, legitimate platforms could see volume migrate from lightly regulated corners to CFTC-compliant venues—or, conversely, see traders exit U.S. jurisdiction entirely. Either way, compliance costs are likely to rise.

For traders and builders, the message is simple: documentation tricks will not outrun economic reality.

Bitcoin hits $70k for first time since June—why now?

Bitcoin jumped more than 7% on Wednesday, lifting a wide range of crypto-related assets as a mix of market developments improved risk appetite across digital assets.

Bitcoin Leads Broad Crypto Rally

The world’s largest cryptocurrency by market value advanced sharply during the session, extending recent volatility and drawing fresh interest from traders. The gains helped push other major tokens and crypto-linked equities higher, reflecting bitcoin’s outsized influence on broader market sentiment.

What’s Driving the Move

Market participants cited a confluence of catalysts that supported risk assets, including improving liquidity conditions in crypto markets and a more constructive tone around regulatory and macroeconomic headlines. In crypto, sharp single-day advances are often amplified by derivatives positioning and liquidations, which can accelerate upside moves once momentum builds.

Broader Market Reaction

Altcoins typically exhibit higher beta to bitcoin, and many moved in tandem as liquidity rotated across the market. Crypto-exposed stocks, such as exchanges and mining firms, also gained alongside the rally, reflecting sensitivity to spot prices and trading activity.

Why It Matters

Bitcoin’s outsized daily swings can reset market sentiment quickly, influencing capital flows, trading volumes, and near-term risk positioning across digital assets. Investors are watching upcoming macro data, policy signals, and regulatory updates that could shape momentum and volatility in the days ahead.

Fifth Circuit Slams SEC’s ‘Everything Is a Security’ Push, Narrowing Token Regulation

Wellermen Image COURT RIPS SEC OVER “UNBRIDLED” TOKEN RULE
Fifth Circuit slams SEC’s enforcement-by-definition approach in blistering April 17 ruling.

The U.S. Court of Appeals for the Fifth Circuit just handed the crypto industry its clearest win yet against the SEC’s “everything is a security” campaign. In a consolidated appeal, the panel threw out the agency’s sweeping attempt to treat digital assets as investment contracts unless they are literally handed over to buyers, effectively kneecapping the SEC’s ability to police secondary-market trading with vague enforcement threats. The decision sends an unmistakable signal: regulators can no longer stretch decades-old precedent to cover code they barely understand.

The case grew out of enforcement actions against two offshore trading platforms accused of listing unregistered tokens. Rather than litigate whether any particular token met the Howey test, the SEC argued that merely “offering” a digital asset on an exchange was enough to trigger securities liability. The Fifth Circuit rejected that shortcut, holding that the agency must still prove purchasers reasonably expected profits derived solely from the efforts of others—an evidentiary bar the SEC had hoped to bypass with a bright-line rule. Judges also chastised the Commission for attempting to “regulate by press release,” noting that its interpretation would let staff declare new asset classes securities without notice-and-comment rulemaking.

For traders and exchanges, the immediate takeaway is reduced enforcement tail-risk: platforms no longer face strict-liability exposure simply because a token trades on their books. Secondary-market liquidity should improve as legal overhang shrinks, and issuers gain breathing room to structure token sales that avoid promoter-driven profit expectations. The ruling also weakens the SEC’s leverage in settlement negotiations, since its fallback threat—automatic securities classification—has been judicially cabined.

DeFi protocols that rely on decentralized liquidity pools now operate under a narrower shadow: if governance tokens confer no ongoing managerial rights, they are less likely to be swept into the agency’s net. Stablecoin issuers, however, remain exposed; the opinion expressly left open the possibility that tokens promising redemption or yield could still satisfy Howey. CFTC oversight of spot commodity trading is effectively affirmed, tilting the jurisdictional balance away from the SEC.

The Commission is expected to seek en banc review or petition the Supreme Court, but until then exchanges and market-makers can price in a lower probability of enforcement shocks—an opportunity, provided they maintain robust compliance on actual securities offerings.

New York Court Rules Crypto Isn’t a Commodity Under UCC, Regal Wins

Wellermen Image Regal Wins: Commodities Court Keeps Crypto Out
A New York appeals court just handed Regal Commodities a decisive victory over trader Tauber, ruling that digital assets are not “commodities” under the state’s commercial code. The decision slams the door on a lawsuit that tried to drag crypto into the same legal framework that governs wheat, oil, and gold futures, and it signals that judges remain wary of treating tokens like traditional exchange-traded assets.

The case began when Tauber claimed Regal had mishandled margin calls on leveraged crypto positions and sued under Article 2 of New York’s Uniform Commercial Code, which covers the sale of “goods.” Regal moved to dismiss, arguing that virtual currencies fall outside the UCC’s definition of commodities. The trial judge agreed and tossed the suit; Tauber appealed, betting that an expansive reading of the statute would let him invoke the code’s buyer-protection rules. On March 27 the Appellate Division, Second Department, unanimously affirmed the dismissal, holding that cryptocurrencies are intangible property, not the sort of tangible or exchange-traded commodities the UCC was written to regulate.

Regal escapes liability under a statute never meant for crypto; Tauber loses both his case and the procedural advantages that would have come with it. The ruling also narrows the legal avenues available to any trader who wants to import old-school commodities protections into digital-asset disputes. Going forward, plaintiffs will have to plead common-law claims, securities statutes, or specific state crypto laws instead of leaning on the UCC.

In plain English, the court told traders: stop trying to jam crypto into legal boxes built for grain silos and oil tankers. New York judges will not stretch existing commodities definitions to cover tokens without clear legislative direction.

For markets, the decision quietly strengthens the hand of regulators who insist that most tokens are either securities or novel instruments requiring fresh rules. It undercuts arguments that crypto should be treated like futures contracts for margin and delivery purposes, which could chill institutional desks hoping to pledge digital collateral under UCC-style safe-harbor provisions. Exchanges and DeFi protocols that have leaned on commodities analogies for their custody or lending programs now face a precedent saying those analogies don’t fly in New York—the gateway jurisdiction for dollar-clearing and derivatives. Traders who prefer regulatory clarity may read the ruling as a warning to structure contracts explicitly rather than assume old statutes will stretch.

Bottom line: until Congress or statehouses draw new lines, judges will keep crypto outside legacy commodities law, leaving both opportunity and risk squarely in the gray zone.

Seventh Circuit Denies CFTC Mandamus, Reinforces Judicial Oversight in Kraft Wheat-Futures Case

Wellermen Image CFTC Mandamus Bid Sends Shockwaves Through Enforcement Playbook
The Seventh Circuit just told the CFTC it cannot force a district judge’s hand in the long-running Kraft manipulation case, handing traders and exchanges a rare check on the agency’s courtroom tactics. The ruling matters because it signals that federal judges—not regulators—will decide how discovery and sanctions play out when the CFTC pushes novel theories of fraud in commodity markets, including digital-asset venues that blend spot and derivatives trading.

The dispute traces back to 2015, when the CFTC accused Kraft and Mondelēz of rigging the wheat futures market by buying physical grain and simultaneously selling futures, allegedly to push prices higher. After years of litigation, Kraft sought internal CFTC documents to prove the agency had changed its enforcement theory mid-case. District Judge Gary Feinerman ordered production; the CFTC refused, claiming deliberative-process privilege. Rather than appeal the order, the agency filed an extraordinary petition for mandamus asking the Seventh Circuit to vacate it outright.

Writing for the three-judge panel, Chief Judge Diane Wood ruled that mandamus is “a drastic remedy” reserved for clear legal errors causing irreparable harm, not a shortcut around normal appellate review. The court found the district judge’s privilege analysis “at least colorable” and noted that any error could be corrected on final appeal. In short, the CFTC lost the procedural battle and must now either turn over the documents or risk sanctions that could weaken its underlying manipulation case.

The decision tightens the CFTC’s toolkit just as the agency eyes broader oversight of crypto-linked commodity contracts and DeFi protocols that resemble futures markets. Exchanges and trading firms gain leverage to demand internal agency records when facing novel enforcement theories, raising the cost and timeline of litigation. For traders, the ruling lowers the odds that aggressive CFTC positions will sail through without judicial pushback, especially where novel assets blur the line between spot commodities and regulated derivatives.

Judges—not regulators—still hold the gavel when enforcement meets innovation.

Bitcoin.com Integrates UAE-Registered USD Stablecoin into Self-Custodial Wallet

Bitcoin.com Adds UAE-Registered USDU Stablecoin to Self-Custodial Wallet

Bitcoin.com has integrated USDU, described as the United Arab Emirates’ first central bank-registered U.S. dollar stablecoin, into its self-custodial wallet. The move expands access to the asset beyond institutional channels and into retail-focused crypto infrastructure.

Integration Brings USDU to Retail Users

The addition of USDU to Bitcoin.com’s wallet broadens the stablecoin’s distribution by making it available through a widely used, non-custodial application. Self-custodial wallets allow users to hold and manage digital assets directly, maintaining control of private keys rather than relying on third-party custodians.

Regulatory Significance in the UAE

USDU’s registration with the UAE’s central bank signals alignment with local regulatory requirements. In a jurisdiction building out comprehensive virtual asset oversight, central bank-registered stablecoins are positioned to serve both compliant institutional use cases and everyday payments, remittances, and settlements.

Why Stablecoin Integrations Matter

Stablecoins pegged to the U.S. dollar are widely used as on-chain cash equivalents for trading, cross-border transfers, and merchant payments. Integrations into mainstream, self-custodial wallets can increase accessibility and liquidity while supporting broader adoption of regulated digital dollars in emerging markets like the UAE.

Panel Consolidates Crypto Lawsuits in Chicago, Centralizing Token Regulation

Wellermen Image Panel Orders Crypto Cases To Illinois

A federal panel has ordered three crypto-related lawsuits to be consolidated in Chicago, giving the Northern District of Illinois the first crack at shaping national rules for how digital assets are treated under the law. The decision matters because it creates a single courtroom where judges will decide whether tokens are securities, commodities, or something else entirely.

The three cases all claim that crypto platforms violated securities laws by selling unregistered tokens. Plaintiffs in each suit say the tokens should have been registered with the SEC before they were sold to retail investors. The defendants pushed back, arguing the tokens are commodities outside the SEC’s reach. When the cases landed in different federal courts, the Judicial Panel on Multidistrict Litigation stepped in to decide which district should handle the common legal questions.

The panel chose Chicago after the lead plaintiff, Anthony Motto, showed that the Northern District of Illinois already has an active docket of similar crypto disputes and the judges there have experience with complex financial-products cases. Centralizing the actions means one judge will decide whether the tokens at issue are securities, whether the platforms functioned as unregistered exchanges, and how damages should be calculated if liability is found. That single ruling could bind or strongly influence dozens of copycat suits now waiting in other districts.

The order shifts power away from the SEC’s chosen venues in California and Pennsylvania and into a Midwest courtroom that has historically been more skeptical of expansive federal regulatory theories. Exchanges and DeFi protocols now face the prospect of a precedent that either tightens or loosens the definition of an investment contract—language that directly affects how tokens are listed, how liquidity providers structure yield programs, and whether stablecoin issuers must register offerings. Traders should watch early motion practice; any ruling that narrows the “investment contract” test will immediately lower compliance costs and re-price tokens that have carried heavy regulatory discounts.

For the industry, the transfer to Illinois is the first concrete signal that crypto litigation may start clustering in sympathetic districts rather than those hand-picked by enforcement agencies.

Fifth Circuit Slams SEC Crypto Crackdown, Demands Howey Test Proof

Wellermen Image Fifth Circuit Slams Brakes on SEC’s Crypto Crackdown
The Fifth Circuit just handed crypto a rare legal win, slapping down the SEC’s attempt to treat most digital assets as securities under a sweeping new definition. In a sweeping opinion, the court ruled that the agency overstepped its authority by trying to regulate digital assets as securities without proving they meet the traditional Howey test. The decision is a direct rebuke of the SEC’s aggressive enforcement strategy and signals that courts are ready to push back on regulatory overreach.

The case began when a crypto company challenged an SEC enforcement action, arguing that the agency’s attempt to label its tokens as securities lacked legal foundation. At issue was whether the SEC could bypass the established Howey test — which asks if an asset involves an investment of money in a common enterprise with an expectation of profits derived from the efforts of others — and instead use a broader, more vague standard. The Fifth Circuit said no. Judges ruled that the SEC cannot invent new legal standards on the fly; it must stick to the law as written and interpreted by courts.

The ruling means the SEC’s enforcement actions against token issuers and exchanges could face serious legal hurdles going forward. Projects that were once in the SEC’s crosshairs now have precedent to push back. Exchanges may find it easier to list tokens without fear of retroactive enforcement. DeFi protocols, often targeted under the same broad theory, could see reduced regulatory pressure in the near term.

In plain English, the court told the SEC: you can’t just call something a security because you want to regulate it. The agency must prove it fits the legal definition. That raises the bar for enforcement and shifts the burden back to regulators to show real investor harm and legal grounding.

This decision chips away at the SEC’s authority to unilaterally define what counts as a security in crypto markets. It doesn’t eliminate regulatory risk — the CFTC still has jurisdiction over commodities, and Congress could still act — but it slows the agency’s momentum and forces it to be more precise. Stablecoin issuers and token projects that were bracing for enforcement may now have breathing room. Exchanges could see a modest uptick in token listings as legal risk recedes. Traders might interpret this as a green light for more speculative assets, though that optimism could be short-lived if the SEC appeals or lawmakers step in.

The Fifth Circuit just reminded everyone that regulators don’t get to rewrite the rules without Congress — and markets are already pricing in the difference.

Ninth Circuit Narrows CFTC Powers in Monex Leveraged-Metals Case

Wellermen Image CFTC Suffers Major Loss in Ninth Circuit Monex Appeal
The Ninth Circuit just handed the CFTC a stinging defeat, ruling that Monex’s leveraged metals contracts are not subject to the agency’s anti-fraud powers under the CEA. The decision slashes the CFTC’s reach over retail precious-metals trading and signals that the agency’s expansive view of its own authority may not hold up on appeal.

The fight began in 2017 when the CFTC accused Monex of running a $290 million fraud scheme through its Atlas program, which let retail customers buy gold, silver and other metals on margin. Monex argued that its contracts were “actual delivery” within 28 days, exempting them from CFTC oversight under the CEA’s retail-commodity exception. The district court agreed and dismissed the suit; the CFTC appealed, claiming the exception only applied to contracts that result in real, immediate possession—not leveraged trades that stay on Monex’s books.

Writing for a unanimous panel, Judge John B. Owens held that the plain language of the statute turns on whether the seller “actually delivers” the commodity to the buyer or an agent, not on whether the buyer takes physical possession. Because Monex transferred title and gave customers the contractual right to demand delivery, the court said the exception applied—even if most customers never exercised it. The ruling guts the CFTC’s case and blocks similar enforcement actions against other leveraged-metals dealers.

In plain English, the Ninth Circuit told the CFTC it cannot stretch the “actual delivery” loophole to cover transactions that merely look like futures. The decision narrows the agency’s jurisdiction over retail commodity contracts that settle in physical assets within the statutory window, shifting the regulatory line closer to traditional futures and swaps.

For crypto markets the message is clear: the CFTC’s authority over leveraged or margined digital-asset trading could face the same textual test. If exchanges can structure spot-delivery mechanics within 28 days, they may fall outside CFTC enforcement even when customers rarely take custody. That reduces enforcement risk for DeFi protocols and offshore platforms but also creates a regulatory vacuum that could invite congressional fixes or state-level action. Stablecoin issuers offering leveraged exposure should re-examine whether their structures trigger the same exemption.

Bottom line: courts are willing to read commodity statutes literally, and that literalism can leave regulators with less power than they thought.

Offshore Crypto Derivatives Fall Under U.S. Regs as Court Expands CFTC’s Reach

Wellermen Image Court Hands CFTC Fresh Power Over Crypto Trading Platforms

The D.C. Circuit just told the CFTC it can police off-exchange crypto derivatives even when no U.S. customer touches them, expanding Washington’s reach over digital-asset markets that until now enjoyed a quiet offshore lane. The ruling arrives as lawmakers debate stablecoin bills and the SEC circles spot-Bitcoin ETFs, sharpening the sense that every major crypto trade now carries a federal regulator’s shadow.

Trevor Kitchen, a trader who ran a peer-to-peer Bitcoin options desk outside U.S. borders, asked the Commission to drop its enforcement case after he moved servers to Malta and blocked American IP addresses. The CFTC refused, insisting that offering leveraged crypto contracts to any trader who might later route funds through a U.S. bank was enough to trigger U.S. jurisdiction. Kitchen appealed, arguing the agency was stretching the Commodity Exchange Act past its territorial limits and chilling legitimate foreign business.

Writing for a unanimous panel, Chief Judge Srinivasan held that the Act’s “direct and significant” effects test reaches foreign platforms whenever dollar-clearing or U.S. bank wires are foreseeable, even if the contract itself is booked abroad. The court rejected Kitchen’s “targeting” argument, saying that once a product is designed to settle in dollars, the platform effectively plugs itself into the U.S. financial grid and must obey CFTC rules on fair pricing, segregation of customer funds, and trade reporting.

In plain English, any crypto exchange or DeFi protocol that offers futures-style products, options, or leveraged tokens in dollars now risks CFTC registration and oversight if even a modest slice of volume clears through American banks or stablecoin issuers. That lowers the appeal of anonymous offshore entities and raises compliance costs for DEX aggregators that rely on USDT or USDC settlement, while handing registered futures commission merchants a competitive edge.

Exchanges that already hold CFTC licenses will likely see volume migrate from gray-market rivals, but pure-code DeFi options vaults could face a fork in the road: geoblock U.S. persons and lose liquidity, or restructure as registered entities and accept on-chain reporting obligations. Stablecoin issuers, meanwhile, inherit indirect scrutiny because their peg instruments are now the rails the court used to anchor foreign platforms to U.S. jurisdiction.

The message to traders and builders is blunt: dollar exposure equals U.S. oversight, and pretending otherwise just became an expensive legal bet.

×