Chicago Court Consolidates Three Crypto Suits, Signals Nationwide Howey Test Battle

Wellermen Image COURT ORDERS CONSOLIDATION OF THREE CRYPTO SUITS

Three separate investor lawsuits against a crypto platform now move to a single courtroom in Chicago, a move that could shape how exchanges and DeFi protocols defend against nationwide class claims.

The Panel on Multidistrict Litigation granted Anthony Motto’s request to fold two additional cases—one from California and one from Pennsylvania—into his existing suit in the Northern District of Illinois. All three complaints allege the same core claim: the platform sold unregistered securities and manipulated token prices. By combining them, the court eliminates duplicative discovery and conflicting rulings, but it also concentrates the litigation firepower of plaintiffs’ counsel in one venue.

The judges found the actions shared “common questions of fact” about how tokens were marketed and whether they qualify as securities. They rejected arguments that local differences in state law or customer agreements justified separate tracks. The Northern District of Illinois will now preside over coordinated pre-trial matters, including class-certification fights, motions to dismiss, and document production. The order does not decide the merits; it simply streamlines the battlefield.

In plain terms, the ruling hands plaintiffs a procedural edge. A single judge will decide whether the tokens are securities under the Howey test, and that decision will bind discovery across all three states. Defendants lose the chance to shop for friendlier venues or to force plaintiffs into piecemeal litigation.

For the broader market, the order signals that courts view crypto cases as sufficiently similar to consolidate, increasing pressure on exchanges and DeFi projects to prepare for national-scale suits rather than isolated complaints. Regulators will watch whether the Illinois court classifies the tokens as securities, a finding that could invite parallel SEC enforcement and affect how other platforms structure token sales.

Watch Chicago: the first substantive ruling on these tokens’ status could set the tone for exchange liability nationwide.
Fifth Circuit Narrows SEC’s Crypto Enforcement, Demands Token-by-Token Security Proof

Wellermen Image Court Deals Fresh Blow to SEC’s Crypto Crackdown
The Fifth Circuit just handed the SEC a stinging defeat in its war on crypto, ruling that the agency overstepped its authority when it tried to punish a major exchange for unregistered offerings. This matters because it chips away at the SEC’s power to treat every digital token as a security and signals to markets that judges are willing to rein in the agency’s reach.

The case began when the SEC sued a crypto exchange for listing tokens it claimed were unregistered securities. The agency argued that because the tokens were sold as investments with expectations of profit from the issuer’s efforts, they qualified as securities under the Howey test. The exchange fought back, saying the SEC lacked clear rules and was stretching old laws to cover new technology. The fight landed at the Fifth Circuit after a lower court sided with the agency.

Judges in New Orleans ruled that the SEC cannot simply declare every token a security without proving the specific economic realities of each offering. They found the agency’s blanket approach too broad and ordered the case back to the lower court with stricter limits on what the SEC must show. The exchange wins breathing room; the SEC loses momentum and precedent.

In plain English, the court told the SEC it cannot treat tokens like stocks just because someone might make money. The agency must now prove each token actually meets the legal definition of a security, token by token, rather than painting the entire industry with one broad brush. This raises the bar for future enforcement actions and forces the SEC to build stronger cases instead of relying on vague guidance.

Markets are reading this as a win for exchanges and DeFi projects that have lived under constant enforcement threat. The ruling narrows the SEC’s ability to label tokens as securities on a whim, which could slow enforcement actions and ease pressure on trading platforms. It also highlights growing tension between the SEC and courts over whether digital assets belong under securities law or commodity rules, a fight that could shift more authority toward the CFTC. Stablecoin issuers and token projects gain a measure of protection, while traders may see reduced delisting risk on U.S. platforms.

The message to the industry is clear: enforcement risk just dropped, but the legal war is far from over.

Ninth Circuit Revives CFTC Suit Against Monex, Rules Leveraged Spot Metals Can Be Regulated as Futures

Wellermen Image Court Hands CFTC Fresh Weapon Over Spot Metals
The Ninth Circuit just revived a stalled CFTC lawsuit against Monex, ruling that leveraged retail metals trades can be regulated as futures even when no contract ever changes hands. The decision re-opens the door to enforcement against any platform that lets customers buy gold or silver with borrowed money and hold it in the dealer’s vault. Traders and exchanges now face the real possibility that spot-leverage products will be treated like derivatives.

The CFTC sued Monex in 2017, claiming its Atlas program—which lets retail customers finance up to 150 percent of their metals purchase—amounted to illegal, off-exchange futures trading. A district judge tossed the case, saying the trades were simple spot sales because ownership transferred at once. On appeal, a three-judge panel reversed. Writing for the court, Judge Wardlaw held that the economic reality of the deal—financing, daily margin calls, and automatic liquidation—made each transaction the “functional equivalent” of a futures contract subject to CFTC oversight.

Monex argued that actual delivery of metal to its depository satisfied the Commodity Exchange Act’s exception for spot transactions. The panel disagreed, focusing on whether the customer gained “independent control” of the metal. Because Monex kept the bars and only gave buyers a bookkeeping entry, the court said delivery was illusory. The ruling hands the agency a broad test: if the buyer cannot remove the commodity without the dealer’s ongoing involvement, the CFTC can regulate it.

In plain terms, the court told metals dealers that letting customers use leverage and keeping the metal in your own warehouse is now a regulated activity. The CFTC no longer needs an exchange-traded contract to bring an enforcement action; it only needs evidence that retail customers are speculating with borrowed money on commodities they never physically touch.

The decision widens the CFTC’s reach over crypto-native platforms that mirror Monex’s structure—margin-financed token trades, perpetual swaps, or vaulted stablecoins. Expect the agency to test the same “functional futures” theory against exchanges and DeFi protocols that advertise leverage without moving assets on-chain to customer wallets. Token issuers and lending desks will face fresh questions about whether their products are spot commodities or unregistered derivatives, and compliance costs are likely to rise.

Traders who rely on high-leverage “spot” metals desks or similar crypto offerings should treat this ruling as a warning flare: regulators now have clearer precedent to treat those products like futures, and enforcement risk just jumped.

D.C. Circuit Narrows CFTC Authority Over Crypto Derivatives

Wellermen Image Court Deals Fresh Blow to CFTC Crypto Reach
Trevor Kitchen just beat the CFTC in a ruling that could redraw the lines between futures and digital assets. The D.C. Circuit tossed an enforcement order against the former trader, holding that his crypto-linked contracts fell outside the agency’s statutory grasp. Markets are already pricing in lighter oversight for certain token products.

Kitchen had pitched leveraged contracts tied to Bitcoin and Ether price feeds on an offshore platform. The CFTC claimed the deals were illegal off-exchange retail commodity transactions and fined him. Kitchen fought back, arguing the products were neither futures nor commodities under the Commodity Exchange Act. The three-judge panel agreed, finding the CFTC lacked jurisdiction because the contracts did not involve the actual delivery of any physical commodity.

Judges ruled the agency stretched the statute when it treated crypto price exposure as a traditional commodity interest. They stressed that the CEA’s reach stops at instruments that contemplate delivery of a tangible good or a narrow class of financial instruments; pure price bets on digital tokens sit outside that fence. Kitchen walks away with no penalty and a precedent that narrows the CFTC’s enforcement perimeter.

The decision chips away at the agency’s ability to police crypto derivatives that never touch an underlying asset. Stablecoin issuers and offshore exchanges gain breathing room, while domestic platforms may face fewer registration hurdles for similar products. Traders betting on unregulated leverage now have a stronger legal shield, but pure futures on CME-listed Bitcoin remain squarely inside CFTC turf.

Expect platforms to test new structures that replicate futures economics without triggering delivery language. The ruling tilts the playing field toward offshore venues and pushes the CFTC to lobby Congress for clearer statutory power or risk watching more volume migrate beyond its reach.

– Bitcoin Whale From 2012 Moves $13.7M After 14 Years – Bitcoin Whale From 2012 Shifts $13.7M After 14 Years – Bitcoin Whale 2012 Moves $13.7M After 14 Years

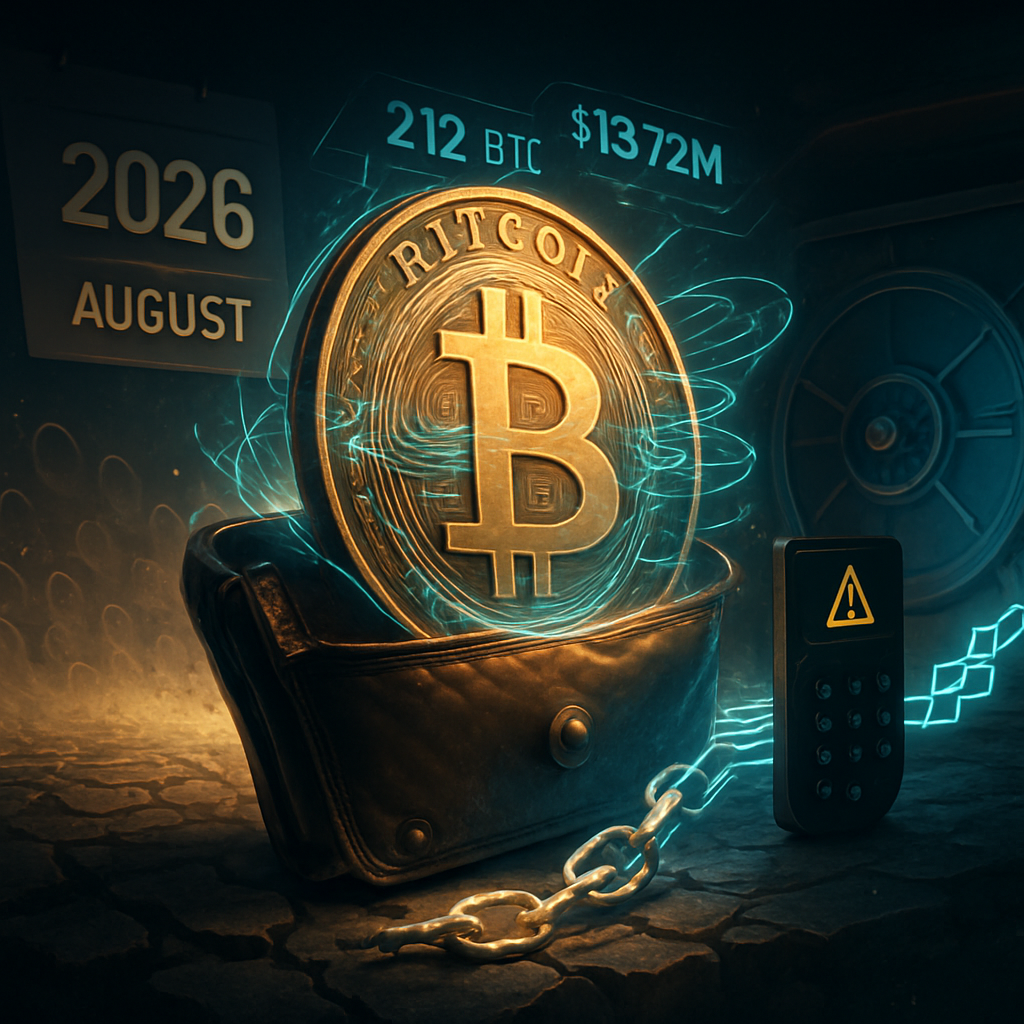
A long-dormant bitcoin address first active in 2012 moved 212 BTC in August, transferring funds worth approximately $13.72 million after more than 14 years of inactivity. The transaction occurred amid a broader wave of “awakening” coins this month, following reports of a Coldcard-related exploit that has prompted some veteran holders to relocate funds.

2012-Era Address Moves 212 BTC

Blockchain records show the 2012 cohort address moved 212 BTC in a single transaction, marking its first on-chain activity since the early years of Bitcoin. At prevailing market prices during the transfer, the coins were valued at roughly $13.72 million. Based on historical pricing from 2012, the stash reflects gains on the order of hundreds of thousands of percent—around 584,725%—if compared with purchase-era valuations. It is not clear whether the funds were sold or simply reorganized to new wallets.

Wave of Dormant Coins Reawakens in August

August has seen an uptick in activity from long-inactive bitcoin addresses. The trend follows reports of a security incident connected to Coldcard hardware wallets, which has led some long-time holders to move funds as a precaution. While not all movements are linked to the incident, the clustering of awakenings suggests heightened security awareness among early adopters and custodians of legacy wallets.

Why It Matters

  • Supply dynamics: Movements from early-era wallets can temporarily increase exchange inflows if coins are sent to trading venues, though many awakenings involve internal reorganizations or enhanced security setups.
  • Market sentiment: Transfers by “vintage” holders often draw attention due to the size of latent gains and the potential for distribution, even when no sale occurs.
  • Security posture: Periodic shifts by dormant wallets frequently coincide with broader industry security events, prompting holders to rotate keys, consolidate UTXOs, or migrate to updated custody arrangements.

Context: Dormant Supply and Early-Holder Behavior

Bitcoin’s dormant supply—coins that have not moved for years—represents a significant portion of the total circulating supply. Historically, awakenings from 2010–2013-era addresses occur sporadically and can reflect a range of motivations, from estate planning and wallet upgrades to opportunistic profit-taking during periods of elevated prices. Without direct evidence of exchange deposits, on-chain moves alone do not confirm selling.

As with prior episodes, this month’s reactivation of a 2012 address underscores the long-term appreciation of early-mined or early-purchased BTC and highlights how security events can ripple across holder behavior, even many years after initial acquisition.

Ninth Circuit Expands CFTC Reach: Offshore Futures Operators Now in U.S. Regulatory Radar

Wellermen Image Court Hands CFTC Fresh Win Over Unregistered Trader
The Ninth Circuit just handed the CFTC a clean victory against James Devlin Crombie, ruling that the agency can still punish him for running an unregistered futures-trading business even though he claims he never touched U.S. customers. The decision strengthens the agency’s long reach and signals that offshore operators cannot dodge U.S. oversight simply by pointing to foreign servers or foreign clients.

Crombie ran a website offering futures contracts and collected over $1.3 million from investors between 2008 and 2011. The CFTC sued him for operating without registration and for fraud, but Crombie fought back, arguing that because his trading platform sat on foreign servers and most customers were abroad, the U.S. agency lacked jurisdiction. A federal judge in San Francisco rejected that claim, froze his assets, and ordered him to pay more than $2 million in restitution and penalties. Crombie appealed, insisting the Commodity Exchange Act could not reach his overseas activity.

The three-judge panel disagreed. It held that the Act’s anti-fraud and registration provisions apply whenever U.S. “commerce” is involved, and that Crombie’s website, dollar-denominated accounts, and U.S.-based marketing created enough of a domestic hook. Judges stressed that the CFTC need not prove every investor was American; it only needs to show that the conduct had a “direct and significant connection” with U.S. markets or participants. Because Crombie accepted U.S. wires and used the American banking system, the court found the link solid.

The ruling tightens the noose on anyone who hopes geography alone will keep the CFTC at bay. Offshore crypto or derivatives platforms that touch U.S. rails—dollar settlement, U.S. marketing, U.S. servers leased from U.S. providers—now face clearer exposure. The decision also lowers the bar for proving jurisdiction: once regulators show any meaningful U.S. nexus, the burden shifts to the defendant to prove total insulation.

For crypto markets, the message is blunt. Tokens or platforms that even arguably function like futures, or that allow U.S. dollar on-ramps, sit inside the CFTC’s crosshairs regardless of where the code lives. Exchanges that still flirt with the “offshore-only” defense just lost another layer of cover, and traders should assume that any service denominated in dollars or marketed in English is on U.S. regulatory radar.

The Ninth Circuit just made “we’re based abroad” a weaker shield; operators who ignore that shift are betting against both the law and the odds.

Court Greenlights IRS to Seize Crypto Wallets in Tax-Evasion Case

Wellermen Image COURT UPHOLDS IRS CRYPTO ACCOUNT SEIZURE
A federal judge in Washington just green-lit the IRS’s seizure of twenty-four crypto accounts tied to a global tax-evasion probe. The ruling, issued in an in-rem forfeiture case, hands the government sweeping authority to treat cryptocurrency wallets as forfeitable property whenever it can show probable cause of unreported income. Markets are watching: if wallets can be grabbed like cash or cars, the risk premium on holding large, anonymous balances just ticked higher.

The case began when IRS agents traced more than $300 million in unreported taxable gains to a network of exchange accounts and private wallets. The government filed civil-forfeiture papers directly against the accounts themselves, a maneuver that lets prosecutors bypass the account holders. Defense lawyers argued that crypto’s decentralized nature makes it impossible to serve traditional notice and that the wallets are intangible “information,” not seizable “property.” Judge Dabney L. Friedrich rejected both claims, holding that a blockchain address is enough to satisfy due-process requirements and that digital assets are property under federal forfeiture statutes.

The opinion hands the IRS a clear win and gives prosecutors a new template for targeting offshore or pseudonymous crypto wealth. Exchanges that fail to cooperate with subpoenas can now expect their customer wallets to be frozen first and litigated later. Meanwhile, DeFi protocols that advertise non-custodial privacy are on notice: if a wallet’s transaction history links it to tax evasion, the code itself offers no shield once the government obtains a civil seizure order.

In plain English, the decision tells anyone parking large sums in crypto that the IRS can reach those funds without first identifying or arresting the owner. Notice by blockchain publication—essentially tweeting the seizure order—is now legally sufficient, lowering the practical barrier for future IRS crypto sweeps.

For markets, the ruling expands the government’s toolkit without changing statutory definitions of securities or commodities; yet it tilts the decentralization-versus-regulation balance toward enforcement. Traders who prize anonymity will price in higher compliance costs or migrate deeper into privacy coins and mixers. Exchanges, already under strict Travel-Rule obligations, face an added incentive to monitor source-of-funds aggressively or risk seeing customer wallets blacklisted by court order.

The bottom line: civil forfeiture just became a sharper sword in the IRS crypto arsenal, and anyone treating wallet privacy as absolute is now on notice.

Partial Court Win for Binance: SEC Case Narrowed, Core Securities Fight Continues

Wellermen Image SEC LOSES GROUND IN BINANCE FIGHT — FOR NOW
The U.S. District Court for the District of Columbia has issued a partial ruling in the SEC’s high-profile lawsuit against Binance Holdings, delivering a mixed verdict that narrows the Commission’s case while leaving the core fight over crypto exchanges and unregistered securities alive. The decision matters because it signals that judges are willing to push back on the SEC’s broadest theories of liability, which could reshape enforcement strategy and embolden platforms that have been playing defense.

The SEC sued Binance in 2023, alleging the world’s largest crypto exchange operated without proper registration, allowed U.S. users to trade unregistered securities, and mishandled customer funds. Binance pushed back hard, arguing the agency overreached by treating most digital assets as securities and by claiming jurisdiction over a foreign platform with decentralized operations. The court had to decide whether the SEC’s claims could survive early dismissal motions and whether the agency had adequately alleged that Binance’s tokens and services violated federal law.

Judge Amy Berman Jackson largely rejected Binance’s attempt to toss the entire case, keeping alive the SEC’s core allegations that BNB and other tokens were sold as investment contracts. However, she trimmed several of the agency’s more aggressive claims, including parts of the unregistered exchange and staking counts, and cast doubt on whether every token on the platform automatically qualifies as a security. Binance scored points by narrowing the battlefield; the SEC lost ground by seeing some of its broadest theories constrained before trial.

In plain English, the court is telling the SEC that it can pursue Binance for operating an unregistered exchange and selling certain tokens, but it cannot blanket-label every crypto transaction as a securities violation without stronger proof. This distinction matters because it forces the agency to be more precise in future cases and gives exchanges a roadmap for structuring products to avoid the same pitfalls.

For crypto markets, the ruling injects both relief and uncertainty. The SEC’s authority takes a modest hit, as judges signal they won’t rubber-stamp every enforcement theory, potentially easing pressure on exchanges and DeFi protocols that feared similar broad-brush attacks. At the same time, the decision leaves the door open for the agency to refine its case, meaning stablecoin classification fights and token-by-token scrutiny will continue. Traders may see short-term sentiment lift from the narrowed claims, but regulatory overhang persists.

The message for the industry is clear: partial victories in court can shift enforcement dynamics, but they rarely end the regulatory war.

– Metaplanet Expands Bitcoin Treasury in US with 2,100 BTC Nasdaq Bet – Metaplanet Expands Bitcoin Treasury with 2,100 BTC Nasdaq Bet – Metaplanet Expands Bitcoin Treasury in US via 2,100 BTC Nasdaq Play

Tokyo-based Metaplanet is pursuing a proposed transaction with Nasdaq-listed Super League Enterprise that would expand its presence into US capital markets by leveraging the company’s existing Bitcoin holdings, rather than initiating additional purchases. The plan aligns with Metaplanet’s Bitcoin-focused treasury strategy, which centers on holding roughly 2,100 BTC.

Proposed deal with Super League Enterprise

The contemplated arrangement with Super League Enterprise (Nasdaq: SLE) is designed to provide Metaplanet a foothold in US markets. While specific terms were not disclosed, the approach would utilize Bitcoin already on Metaplanet’s balance sheet to support the structure of the deal.

Extending a Bitcoin treasury strategy

Metaplanet, listed in Tokyo, has adopted Bitcoin as a core treasury asset, positioning itself among a small cohort of public companies holding sizable BTC reserves. By seeking a US market pathway without adding to its Bitcoin stack, the company aims to broaden investor access to its strategy while managing balance sheet risk.

Why US market access matters

Listing exposure in the United States can increase liquidity and visibility among global investors, particularly those seeking direct or indirect exposure to corporate Bitcoin strategies. Working with an existing Nasdaq-listed entity offers a potential route to that market without undertaking a separate US listing process.

What to watch next

Further details on structure, timing, and regulatory steps were not immediately available. Any final agreement would be subject to customary approvals and market conditions.

Delaware Court Nixes Diamond Fortress Fingerprint Wallet Patent as Abstract Idea

Wellermen Image Court Blocks Diamond Fortress Crypto Patent Claim
Delaware’s Superior Court just handed the crypto industry a blunt reminder that software patents must solve a concrete technical problem to survive. The ruling kills off Diamond Fortress Technologies’ attempt to sue over a fingerprint-based biometric authentication system for digital wallets, effectively narrowing the legal weapons available to blockchain patent trolls.

The case started when Diamond Fortress sued a wallet provider claiming its patented method of using a user’s fingerprint to unlock access to private keys was being infringed. The defense argued the patent merely described an abstract idea—biometric login—implemented on generic computers. Judge Paul R. Wallace agreed, granting summary judgment that the claims were ineligible under Section 101 of the patent statute because they lacked any inventive concept beyond routine data collection and storage.

The decision immediately shifts power away from patent holders who dress up basic authentication flows as novel inventions. Companies building wallet software, DeFi protocols, and exchange custody solutions can now operate with reduced fear of infringement suits over fingerprint or facial-recognition login layers. At the same time, the ruling underscores that the Patent Office will keep facing challenges when it grants broad software patents that courts later find too abstract to enforce.

In plain English, the court said wrapping an everyday security step inside a blockchain app does not create a new invention. The legal impact is straightforward: future litigants will have a harder time weaponizing similar patents, and defendants gain a stronger hand to dismiss cases early rather than endure costly discovery.

For crypto markets, the ruling tilts the scale toward open implementation of biometric security features without licensing overhead, lowering barriers for wallet developers and DeFi front-ends. It also signals that courts will continue to police overbroad patents in digital-asset infrastructure, reducing the regulatory overhang that can chill innovation while leaving the SEC and CFTC on the sideline—this was a patent fight, not a securities case. Exchanges and protocols that integrate biometrics can treat the ruling as a green light to enhance user security without new legal drag.

Bottom line: expect fewer surprise patent lawsuits over routine wallet features, but keep watching for the next abstract idea dressed up as a breakthrough.

D.C. Circuit Forces SEC to Revisit Grayscale’s Spot Bitcoin ETF

Wellermen Image Court Slams SEC Over Bitcoin ETF Rejection
The D.C. Circuit just ordered the SEC to reconsider its denial of Grayscale’s spot Bitcoin ETF, ruling the agency’s logic was arbitrary and inconsistent with its treatment of similar products. The decision sends a clear message: regulators cannot treat the same underlying asset differently based on packaging alone. Markets read this as a win for crypto’s institutional legitimacy and a potential crack in the SEC’s wall of resistance.

The case began when Grayscale asked the SEC to convert its Bitcoin Trust into an exchange-traded fund that would hold actual Bitcoin. The Commission turned the request down, arguing that the proposed ETF carried risks of fraud and manipulation not present in Bitcoin futures products already trading on exchanges. Grayscale sued, claiming the SEC had no coherent reason to reject spot exposure when it had already approved futures-based vehicles that track the same price.

A three-judge panel agreed. Writing for the court, Judge Rao found the SEC failed to explain why fraud risks would be greater in a spot ETF than in futures products, especially when both rely on the same underlying Bitcoin market. The judges also noted that the SEC had approved similar structures for gold and other commodities, undermining its claim that crypto’s unique dangers justified special treatment. The ruling vacates the denial and sends the application back to the agency for a fresh look.

In plain terms, the court told the SEC its reasoning did not hold up. The Commission can still reject the ETF, but it must supply a more consistent and evidence-based explanation. Until then, Grayscale’s product is back in play, and other sponsors watching from the sidelines now have precedent on their side.

The decision shifts the balance of power between the SEC and courts on crypto matters. It does not force approval, but it narrows the agency’s discretion to say no without stronger proof of investor harm. Spot Bitcoin ETFs could soon offer mainstream investors direct exposure without wallets or private keys, increasing demand for regulated custody solutions and pressuring exchanges to tighten compliance. The ruling also weakens the SEC’s ability to label most tokens as unregistered securities by implication, since the court signaled that functional similarity, not labels, should drive policy.

For traders and issuers, the case lowers the perceived risk of bringing crypto products to market under existing rules.

CFTC Wins Appeal: Crypto Promoters Labeled Commodity Trading Advisors

Wellermen Image CFTC Wins Appeal, Crypto Promoter Labeled Commodity Advisor
Federal appeals court hands regulators their clearest victory yet in defining who must register with the CFTC. The ruling slams a door that many crypto promoters hoped would stay open: marketing digital assets without registering as a commodity trading advisor. For traders and platforms, the message is simple—talking about futures-style returns now carries registration risk.

James Donelson built an online audience by promising crypto trading signals and portfolio advice. The CFTC sued, arguing he was acting as a commodity trading advisor without the required registration and disclosures. Donelson countered that he only gave “general market commentary,” not personalized trading instructions, and therefore fell outside the statute. The district court disagreed, and the Seventh Circuit has now affirmed.

The three-judge panel ruled that once an adviser holds himself out to the public as someone who can guide commodity trades—even if the advice is delivered online and the audience is anonymous—he meets the legal definition. The court rejected Donelson’s claim that the advice must be “tailored” to each subscriber; collective, paid-for guidance is enough. Because his crypto advice involved futures-linked assets, the CFTC’s reach was confirmed.

In plain English, the court said registration rules travel with the advice, not with the adviser’s business model. If you charge money for trading tips on anything the CFTC oversees, you probably need to register. That standard applies whether the tips arrive by newsletter, Discord, or TikTok.

For the market, the decision widens the CFTC’s net around informal crypto influencers and signal services. Exchanges and DeFi protocols that partner with such commentators could inherit secondary liability risk. Stablecoin issuers and token projects that pay for “educational” content may find themselves funding unregistered advisory activity. Traders relying on these sources face the possibility that their favorite newsletter suddenly goes dark or hikes prices to cover compliance costs.

The upshot: crypto advice is no longer a gray zone; it is now a regulated service, and the CFTC just proved it can enforce that view on appeal.

Bitcoin, Ethereum: AI Pivot Boosts Miners; One Twist Could Revive Mining

Bitcoin miners that have secured contracts to provide artificial intelligence (AI) and high-performance computing (HPC) services are commanding premium valuations, as softer bitcoin prices and compressed “hashprice” pressure pure-play mining operators.

AI and HPC Deals Lift Mining Valuations

Investors have increasingly favored miners that diversify beyond bitcoin block rewards by leasing capacity, power, and infrastructure to AI and HPC customers. These arrangements can deliver steadier, contract-based revenue compared with the volatility of bitcoin mining, where income depends on coin prices, transaction fees, and network difficulty.

Several publicly listed miners have announced AI or HPC initiatives in recent years, including hosting or operating GPU clusters for third parties. Companies such as Core Scientific, Iris Energy, Bitdeer, and Hut 8 have pursued data center expansions or contracts aimed at servicing AI workloads, reflecting a broader shift toward dual-use infrastructure.

Hashprice Compression Squeezes Pure-Play Miners

Hashprice—a commonly tracked metric for miner revenue per unit of hashrate—has remained under pressure during periods of weaker bitcoin prices and rising network difficulty. Lower hashprice reduces margins for operators reliant solely on mining rewards, intensifying competition and accelerating consolidation in the sector.

By contrast, AI and HPC contracts can offer multi-year visibility, higher revenue per megawatt, and utilization rates less correlated with bitcoin market cycles. This perceived resilience has contributed to higher relative valuations for diversified miners versus pure-play peers.

Diversification Becomes a Strategic Priority

Pivoting into AI and HPC typically requires significant capital investment, access to high-quality power, cooling, and networking, as well as the ability to procure GPU hardware and attract enterprise clients. Despite these hurdles, miners with existing large-scale power footprints and data center expertise are well positioned to pursue hybrid strategies that balance bitcoin mining with compute hosting.

With mining economics sensitive to price swings and difficulty adjustments, the market’s preference for diversified revenue streams has become more pronounced, reinforcing a valuation gap between miners with AI/HPC exposure and those focused exclusively on bitcoin production.

Coinbase Wins Court Ruling: SEC Must Explain Rulemaking Denial

Wellermen Image Coinbase Wins Key Court Fight Over SEC Oversight
The Third Circuit handed Coinbase a procedural win that could slow the SEC’s enforcement train. The court said the agency must explain itself before courts will review its refusal to write new crypto rules. For markets, the ruling keeps uncertainty alive but gives exchanges breathing room.

Coinbase filed its petition after the SEC rejected the exchange’s 2022 rulemaking petition asking the agency to clarify how existing securities laws apply to digital assets. The SEC argued that its denial was unreviewable “agency inaction,” and Coinbase had no right to force the Commission’s hand. The Third Circuit disagreed. It held that an agency’s outright refusal to begin rulemaking is final agency action and therefore subject to judicial review under the Administrative Procedure Act.

Writing for the panel, the judges ruled that Coinbase’s petition stated a plausible claim that the SEC’s denial was arbitrary and capricious. The case now returns to the district court for a full hearing on whether the Commission gave adequate reasons for keeping its cards close to the vest. In practical terms, Coinbase gains the right to argue that the SEC must articulate a coherent policy before it can keep hammering exchanges with enforcement actions.

The decision narrows the SEC’s insulation from judicial scrutiny but stops short of ordering the agency to issue new rules. It shifts the battlefield from whether courts can review such denials to whether the SEC’s justifications hold water under administrative-law standards. That opens a lane for exchanges and token issuers to press for clearer guidance instead of facing regulation by enforcement.

Authority-wise, the ruling chips away at the SEC’s ability to dodge questions about which tokens are securities and how DeFi protocols fit inside existing statutes. Traders now see a slightly lower probability of sudden rule-by-lawsuit surprises, yet the core classification risk remains. Exchanges may delay product launches or new listings while the legal dust settles, and stablecoin issuers will watch closely to see if clearer definitions emerge from the coming district-court showdown.

The case proves that courts will at least listen when industry asks the SEC to show its work; whether the agency listens is the next bet markets must price.

Bitcoin News: WLFI Faces Pentagon-Flagged AI Ties Scrutiny

World Liberty Financial (WLFI), a cryptocurrency venture linked to members of Donald Trump’s family, is facing scrutiny following reports that nearly half of the artificial intelligence (AI) models on its partner platform, Worldclaw, originate from Chinese companies identified by the U.S. Department of Defense as military-affiliated.

Allegations Over AI Model Providers

The concerns center on the provenance of AI models listed on Worldclaw, a partner platform to WLFI. According to the reports, a significant share of those models are supplied by firms that appear on Department of Defense lists of Chinese military-aligned or defense-linked companies. Inclusion on such lists does not in itself determine illegality for private-sector partnerships, but it can attract heightened regulatory and political attention in the United States.

What Are WLFI and Worldclaw?

WLFI is a crypto-focused initiative associated with Trump family interests. Worldclaw is described as a Hong Kong-based AI marketplace that aggregates and distributes machine-learning models from various developers. The partnership positions WLFI adjacent to AI tooling and services, an area that has seen rising interest from digital-asset projects seeking to integrate AI capabilities with blockchain-based applications.

Regulatory Context and Potential Impact

The U.S. government maintains lists of Chinese companies assessed to have ties to the country’s military-industrial complex, and U.S. authorities have taken a stricter posture toward technology transfers and financial relationships involving such entities. While listing AI models from those firms does not automatically constitute a violation of U.S. law, it raises due diligence, sanctions-screening, and reputational considerations for U.S.-linked ventures and their partners.

Any continued association could invite questions from investors, exchanges, and service providers about compliance controls, supplier vetting, and exposure to evolving U.S. restrictions. Market participants may also watch for any changes to Worldclaw’s listings or WLFI’s partnership framework as the situation develops.

What to Watch

Key developments to monitor include any formal statements from WLFI or Worldclaw addressing the reports, potential adjustments to model suppliers on Worldclaw, and any regulatory guidance that clarifies how U.S.-linked crypto and AI platforms should engage with vendors connected to entities on Defense Department lists.

×