Seventh Circuit Upholds CFTC Win in Unregistered Crypto-Futures Case

Wellermen Image COURT SLAMS DONELSON—CRYPTO FUTURES SELLER LOSES APPEAL

The Seventh Circuit just handed the CFTC a decisive win against James Donelson, affirming that his unregistered crypto-futures scheme violated the Commodity Exchange Act. The ruling tightens the regulatory net around anyone selling leveraged or margined digital-asset contracts, and it comes at a moment when the CFTC is already flexing its muscles over crypto derivatives.

The case started when Donelson, operating through a website called “Coin Drop Markets,” offered retail customers leveraged exposure to Bitcoin, Ether, and other tokens without registering with the CFTC or routing trades through a designated contract market. The agency sued, alleging fraud and illegal off-exchange trading; the district court granted summary judgment, froze his assets, and ordered nearly $3 million in restitution and penalties. Donelson appealed, arguing the contracts were not “commodity futures” and that the CFTC lacked jurisdiction once the underlying tokens were deemed securities by the SEC.

Writing for a three-judge panel, the Seventh Circuit rejected every claim. The court held that any agreement offering leveraged or margined exposure to a commodity—including digital assets—qualifies as a futures contract if it allows customers to speculate on price moves without taking delivery. Because Donelson’s platform did exactly that, registration and exchange-trading rules applied. The judges also brushed aside his SEC-preemption argument, noting that dual registration obligations are common and that the agencies’ overlapping authority does not cancel either regulator’s power.

In plain English, the decision tells crypto entrepreneurs that calling a product a “swap,” “pool,” or “investment opportunity” will not shield them from CFTC oversight if customers can trade with leverage and no delivery ever changes hands. The ruling also cements the CFTC’s position that most major tokens are commodities, giving the agency clear statutory footing even when the SEC simultaneously labels the same tokens securities in their initial offerings.

For markets, the ruling expands the CFTC’s practical reach without new legislation. Expect enforcement teams to target DeFi protocols offering perpetual-style contracts, offshore exchanges serving U.S. users, and any platform that lets traders post margin to speculate on token prices. Centralized exchanges may face pressure to list only CFTC-compliant products or risk vicarious liability. Traders using unregulated leverage products will see fewer counterparties, wider spreads, and a higher risk of sudden platform shutdowns.

Bottom line: the Seventh Circuit just made it costlier—and legally riskier—to offer U.S. customers crypto exposure without CFTC oversight, shifting the advantage back to registered exchanges and pushing DeFi builders toward compliance-first architectures or geographic exclusion of American users.
SBI, Kyobo Complete Japan-Korea Stablecoin Test Without Dollar Dependency

SBI Digital Practice and Kyobo Life Complete Yen-Won Stablecoin Settlement Pilot

SBI Digital Practice and South Korean insurer Kyobo Life have completed a cross-border pilot that converted yen-linked test tokens directly into won-linked tokens. The trial examined whether tokenized settlement infrastructure could streamline institutional transfers between Japan and South Korea.

Testing Direct Currency Conversion

The pilot focused on the direct exchange of test tokens representing the Japanese yen and South Korean won. Unlike conventional cross-border transfers, which may involve multiple intermediaries and currency-conversion steps, the trial tested whether institutions could move value between the two currencies through a token-based process.

The tokens used in the exercise were test assets designed for the pilot and were not presented as publicly circulating stablecoins. The initiative was intended to assess the operational feasibility of digital-currency settlement in an institutional setting.

Potential Benefits for Institutional Transfers

SBI Digital Practice and Kyobo Life evaluated whether stablecoin-style infrastructure could reduce settlement delays, simplify conversion procedures and lower transaction costs. These factors are among the key considerations for financial institutions exploring blockchain-based payment and settlement systems.

Cross-border transfers between Japan and South Korea typically require coordination among banks, payment providers and foreign-exchange services. A direct tokenized settlement model could reduce the number of processing steps, although issues such as regulatory compliance, liquidity and interoperability would still need to be addressed before commercial deployment.

Broader Digital-Settlement Development

The completed pilot reflects wider efforts by financial institutions in Asia to examine tokenized deposits, stablecoins and other blockchain-based payment instruments. Further testing would be required to determine how such systems could operate at scale and integrate with existing banking infrastructure.

No commercial launch or broader rollout was announced as part of the pilot.

Third Circuit Forces SEC to Define Crypto as Security or Commodity

Wellermen Image COINBASE WINS ROUND ONE IN SEC WAR

The Third Circuit just forced the SEC to answer the crypto industry’s central question: are digital assets securities or commodities? By granting Coinbase’s petition for review, the court blocked the agency from hiding behind its own refusal to issue clear rules. The decision instantly hands exchanges and DeFi protocols a new lever to challenge enforcement-first tactics.

The lawsuit began when Coinbase asked the SEC for formal guidance on whether major tokens traded on its platform fall under securities law. The agency ignored the petition, then launched an enforcement action alleging unregistered offerings. Coinbase sued, arguing the SEC’s silence plus contradictory public statements violated the Administrative Procedure Act. Today the Third Circuit agreed the petition was improperly denied and ordered the SEC to either start a rulemaking or explain why crypto assets are already covered.

Judges Ambro, Krause, and Porter ruled that the SEC cannot treat silence as policy when billions in trading volume hang in the balance. Coinbase keeps its petition alive; the SEC loses the shield of “no comment.” Practically, the Commission must now decide within a court-imposed timeline whether to classify staking rewards, wrapped tokens, and liquidity-provider incentives as securities or admit they fall outside its remit.

In plain English, the court told regulators they can’t weaponize uncertainty. If the SEC drags its feet again, exchanges gain ammunition to argue in future enforcement cases that no reasonable notice existed. That single procedural win shifts negotiating power away from Washington and toward the trading desks.

The ruling chips away at the SEC’s authority to set crypto policy through enforcement alone. Expect CFTC officials to seize the opening and claim broader jurisdiction over spot markets. Stablecoin issuers will cite the decision to argue their tokens are payment instruments, not investment contracts. Centralized exchanges gain breathing room to lobby for safe-harbor legislation before the next enforcement wave; DeFi protocols may accelerate offshore structures while the window stays open. Traders should watch for a short-term relief rally in large-cap tokens most exposed to SEC allegations.

This is a procedural beachhead, not a final victory—watch how the SEC rewrites its playbook next.

HYPE Surges Above $90 as Hyperliquid Launches Manual Borrowing

Hyperliquid’s native HYPE token reached a record high of $90.92 after the decentralized trading platform introduced manual borrowing, allowing users to borrow stablecoins against HYPE and Bitcoin collateral.

HYPE Reaches New Record

The token’s move above $90 followed the launch of the new borrowing feature on Hyperliquid. The record marks a notable price milestone for HYPE as the platform expands its collateralized borrowing capabilities.

Manual Borrowing Goes Live

Under the new system, users can manually borrow stablecoins by pledging HYPE or Bitcoin as collateral. The feature adds another lending-related function to Hyperliquid’s ecosystem and gives users access to stablecoin liquidity without selling their underlying assets.

Crypto Groups Take Illinois to Court Over 0.2% Tax Ahead of January Launch

Wellermen Image

Crypto Groups Move to Block Illinois Tax

The Crypto Council for Innovation and the Blockchain Association are escalating their legal fight against Illinois’ proposed 0.2% crypto tax. They argue the levy is unconstitutional and could create expensive compliance demands before its January effective date.

The dispute follows an earlier lawsuit challenging the measure, putting the state’s new crypto policy under immediate legal pressure. The industry groups are now seeking to stop the tax before businesses and users are forced to build systems around it.

At 0.2%, the rate may look modest, but the groups argue the real burden could come from tracking taxable crypto activity, calculating obligations, and complying with a rule that may apply across fast-moving digital-asset transactions. The lawsuit’s constitutional claims will determine whether Illinois can enforce the measure as written.

What This Means for Crypto

In plain English, the trade groups want a court to pause the tax before January while judges consider whether Illinois overstepped its authority. A temporary block would give exchanges, businesses, and investors more time and clarity; allowing the tax to proceed could raise operating costs and push some activity to other jurisdictions.

The case also highlights a broader problem for crypto users: even a small transaction tax can become complicated when assets move frequently, prices swing sharply, and records are spread across wallets and platforms.

Market Impact and Next Moves

The immediate market reaction is likely mixed rather than dramatic. This is a state-level legal fight, not a direct change to token supply or blockchain security, but investors may view the challenge as a test of whether aggressive crypto taxation can survive organized industry opposition.

The key risks are regulatory uncertainty, higher compliance costs, and the possibility that other states copy Illinois if the measure survives. The opportunity is clearer rules: a successful challenge could discourage poorly designed taxes, while a negotiated replacement may give legitimate crypto businesses a more workable path to operate.

For now, Illinois’ 0.2% crypto tax is less a settled policy than a legal showdown that could shape the cost of doing business in digital assets.

Germany Reportedly Eyes 25% Crypto Tax From 2028 in Blow to Investors

Wellermen Image

Germany Reportedly Plans 25% Crypto Tax From 2028

Germany’s Finance Ministry is reportedly considering a 25% tax on cryptocurrency gains, potentially ending the country’s current one-year holding exemption. The proposal could reshape investor behavior and weaken Germany’s reputation as one of Europe’s more crypto-friendly markets.

The reported plan would mark a sharp departure from existing rules, under which certain crypto gains can become tax-free after assets are held for more than 12 months. If adopted, the new regime could affect long-term holders, traders, and businesses that built strategies around Germany’s current tax treatment.

The key question is whether the proposal becomes law and how broadly it would apply. Details remain limited, including whether the tax would cover all digital assets, how staking and decentralized finance income would be treated, and whether existing holdings would receive transitional protection.

What This Means for Crypto

In plain English, a 25% capital-gains tax would allow the government to claim a quarter of an investor’s taxable profit. That could make selling less attractive and encourage some holders to delay transactions, relocate, or seek more tax-efficient structures.

Traders would likely face the biggest immediate impact because frequent buying and selling creates more taxable events. Long-term investors could also reassess Germany’s appeal, while crypto businesses may worry that less favorable rules could push talent and capital toward jurisdictions with clearer or lighter taxation.

Market Impact and Next Moves

The short-term reaction would likely be bearish for Germany’s crypto market, though the broader global impact may remain limited unless the measure becomes part of a wider European tax push. Investors typically punish uncertainty first, especially when rules threaten established strategies.

The main risks are regulatory drift, unclear enforcement, and forced selling by investors who want to exit before new rules take effect. The opportunity is more selective: projects with strong fundamentals and genuine adoption may remain attractive, but tax planning and legal compliance will become just as important as token performance.

Germany’s crypto advantage may not disappear overnight, but a 25% tax would make every investor calculate the cost of staying.

Layer-2 and DeFi Tokens Rally as Post-Fed Fears Fade

Starknet and Arbitrum Rise More Than 17% as Crypto Market Broadens

Starknet and Arbitrum posted gains of more than 17% as the cryptocurrency market advanced broadly, while the U.S. 10-year Treasury yield moved back below 5%.

Altcoins Lead Market Gains

Starknet, the Ethereum layer-2 network associated with the STRK token, and Arbitrum, another Ethereum scaling network represented by ARB, were among the strongest performers. Both tokens rose more than 17% during the session.

Most CoinDesk 100 Constituents Advance

Market breadth was also strong. A total of 98 assets in the CoinDesk 100 advanced, indicating that gains extended well beyond a small group of leading cryptocurrencies.

Treasury Yields Ease

The U.S. 10-year Treasury yield slipped back below 5%. Movements in government bond yields can influence broader risk sentiment, including demand for digital assets, although the market response can vary depending on the wider economic backdrop.

US Bank Tests Proprietary Stablecoin in Cross-Border Stellar Pilot

Wellermen Image

US Bank Tests Proprietary Stablecoin Across Stellar Network

A US bank has moved its proprietary USBDC stablecoin between North American and European entities in a cross-border pilot on the public Stellar blockchain. The test puts traditional banking rails under pressure while showing how stablecoins could make international transfers faster and more programmable.

The pilot was sparked by the bank’s effort to test digital money in a real cross-border setting rather than a closed laboratory environment. USBDC was transferred between the institution’s regional entities, with Stellar providing the public blockchain infrastructure for settlement.

The transaction does not signal an immediate replacement for the global banking system, but it does show where the industry is heading. Banks are increasingly testing stablecoins for internal transfers, treasury operations, and settlement, while public blockchains are becoming harder for financial institutions to ignore.

What This Means for Crypto

A proprietary stablecoin is a digital token issued and controlled by one institution, typically designed to maintain a stable value against a traditional currency such as the US dollar. In this case, the token appears to have been used as a settlement instrument between the bank’s own international entities.

For traders and long-term investors, the important signal is not necessarily USBDC itself, but the growing institutional use of blockchain networks. Builders may benefit if banks create demand for faster settlement, tokenized deposits, and compliant financial applications on public chains.

Market Impact and Next Moves

The short-term market reaction is likely mixed. The pilot is bullish for the broader stablecoin and tokenization narrative, but it does not automatically create demand for Stellar’s native token or guarantee that the bank will expand the program.

The main risks are regulatory approval, liquidity, privacy concerns, and whether banks eventually choose private networks over public blockchains. Still, successful cross-border testing could strengthen the case for blockchain-based settlement and attract more institutions to the sector.

The bigger opportunity is simple: if banks can move regulated digital money across borders efficiently, stablecoins may become financial infrastructure rather than just another crypto trading product.

Bitcoin: Saylor Says SEC Exemption Puts Tokenized MSTR, STRC Onchain 24/7

Michael Saylor Says SEC Innovation Exemption Could Enable 24/7 Onchain Trading for Tokenized MSTR and STRC

Strategy Executive Chairman Michael Saylor said a new U.S. Securities and Exchange Commission (SEC) innovation exemption could allow tokenized versions of the company’s securities to trade onchain around the clock. The comments mark a potential test of Saylor’s long-standing push to bring corporate credit and equity instruments onto blockchain networks.

Saylor Links SEC Exemption to Tokenized Securities

Saylor made the claim in a public statement, arguing that the SEC’s new exemption clears the way for tokenized versions of MSTR and STRC to trade continuously outside traditional stock-market hours.

MSTR is the stock ticker associated with Strategy, the business-intelligence company that has made bitcoin its primary treasury asset. STRC refers to one of the company’s preferred securities. Tokenization would represent ownership or economic exposure to those instruments through blockchain-based tokens.

Unlike securities traded on conventional exchanges, blockchain-based markets can operate continuously, subject to the rules of the platform, the applicable securities framework and available market liquidity. Saylor’s comments indicate that Strategy-linked assets could become an early example of this model if the relevant regulatory and market conditions are met.

Regulatory Scope Remains Unclear

The statement did not provide details about the exemption, identify the entities that would issue or trade the tokens, or explain the specific legal conditions attached to the SEC’s action. It also did not establish that all tokenized versions of MSTR or STRC are currently approved for unrestricted trading.

Regulatory exemptions typically apply only within defined parameters. Issuers and trading platforms may still need to comply with registration, disclosure, investor-protection, custody and market-integrity requirements. The availability of 24/7 trading would also depend on the structure of the tokenized products and the platforms supporting them.

A Test of Saylor’s Digital Credit Strategy

Saylor has spent the past year promoting the use of blockchain networks to issue and trade digital representations of financial instruments. He has described tokenized securities as part of a broader effort to modernize capital markets and expand access to digital credit products.

If implemented, tokenized MSTR and STRC could provide a live test of whether publicly traded corporate securities can operate across both traditional and blockchain-based markets. The experiment would also highlight the practical challenges of connecting onchain settlement with existing securities laws, exchange infrastructure and investor safeguards.

Further details from Strategy, the SEC or the platforms involved will be needed to determine the exemption’s precise scope and whether tokenized MSTR and STRC will begin trading under the framework described by Saylor.

Crypto VC Funding Soars 31% to $5.7B in Q2 2026

Crypto Venture Funding Rebounds to $5.7 Billion in Q2 2026

Crypto venture capital funding rebounded sharply in the second quarter of 2026, with investors deploying approximately $5.7 billion across 384 deals. The increase was driven primarily by larger, later-stage financings, while fundraising for new crypto-focused venture funds remained unusually weak.

Investors Favor Larger, Later-Stage Deals

The second-quarter results suggest that venture investors are returning to established companies and projects with more developed operations. Larger later-stage financings accounted for much of the increase in total capital deployed during the period.

Although the number of transactions remained an important measure of activity, the rise in overall funding indicates that deal sizes played a significant role in the quarter’s recovery.

New Fundraising Remains Weak

The rebound in venture deployment contrasted with continued weakness in fundraising for new crypto venture funds. This suggests that existing funds may be directing more capital toward portfolio companies, even as managers face challenges raising fresh pools of investment.

The divergence between higher investment activity and subdued fund formation could point to a more selective market. Investors appear to be committing capital to later-stage opportunities while remaining cautious about launching or backing new crypto-focused funds.

What the Trend Signals for Crypto Markets

The quarterly figures indicate renewed institutional interest in the cryptocurrency sector, but the concentration of funding in larger, later-stage transactions reflects a measured approach rather than broad-based expansion across the market.

Future quarters will show whether the second-quarter increase marks the beginning of a sustained recovery in crypto venture activity or a temporary rise driven by a limited number of large financings.

Family Finds Sealed 1980s Nintendo Games Worth a Fortune in Closet

Heritage Auctions Examines Sealed Collection of 1980s Nintendo Games

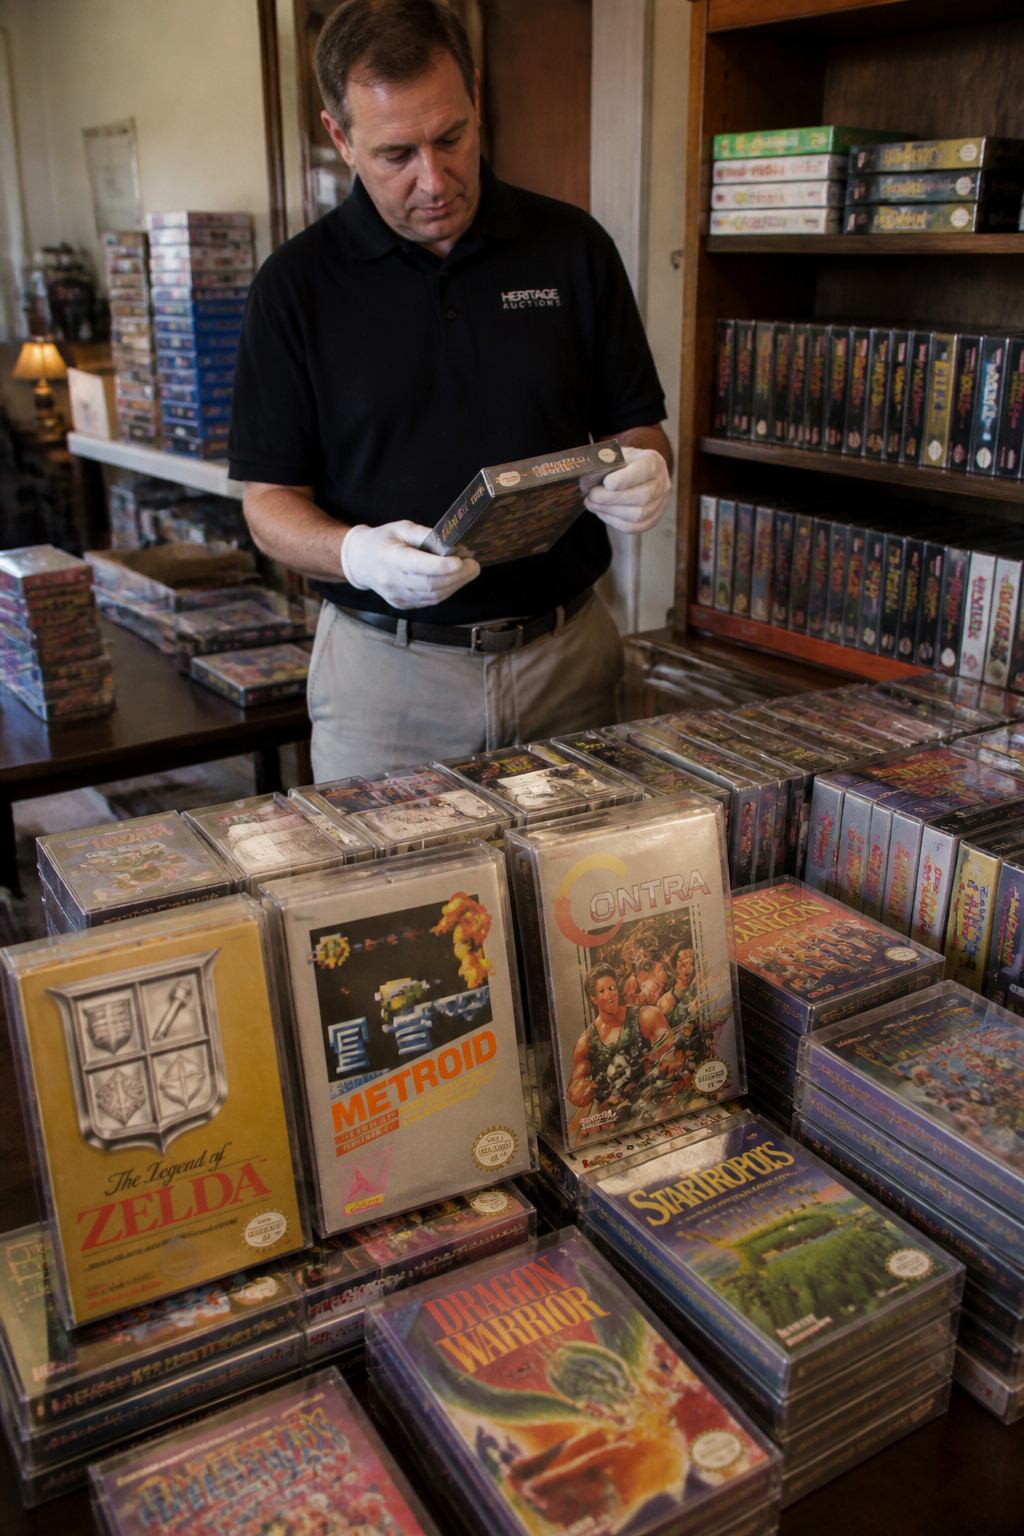
Heritage Auctions has identified a large collection of vintage Nintendo games in the Dallas-Fort Worth area, with approximately 90% of the items still sealed. The collection includes early editions of several well-known Nintendo Entertainment System titles.

Rare Games Found in Dallas-Fort Worth

Heritage Auctions sent partner Cris Bierrenbach to meet the seller and assess the collection. The company said the visit revealed a substantial hoard of games stored in a private residence.

Among the titles identified were early printings of The Legend of Zelda, Metroid, and Contra. The collection also reportedly includes dozens of other games from the 1980s era.

Sealed Condition May Affect Value

Collectors generally place a premium on video games that retain their original factory seals, particularly when the packaging is well preserved and the titles are associated with major franchises. Condition, edition, packaging details, and auction demand can all influence the final market value of individual games.

Heritage Auctions’ review of the Dallas-Fort Worth Collection is expected to provide further details about the titles and their condition before any potential sale.

**CLARITY Act Stalls: Waters and Emmer Clash Over Trump Bitcoin Deals**

CLARITY Act Faces Uncertain Future as Lawmakers Continue Digital Asset Debate

Congressional discussions over U.S. cryptocurrency regulation are continuing despite the recent setback for the CLARITY Act. Rep. Tom Emmer remains optimistic that lawmakers can revive negotiations and advance the bill before the end of the year, while Rep. Maxine Waters has criticized the legislation in its current form.

Emmer Pushes for Renewed Discussions

Emmer has expressed hope that Congress will reopen talks on the CLARITY Act, a proposed framework intended to establish clearer rules for digital assets and define the responsibilities of federal regulators.

Although the bill recently suffered a legislative setback, Emmer indicated that negotiations could resume. He continues to support the possibility of securing passage before year-end, suggesting that the measure may not be permanently off the congressional agenda.

Waters Raises Concerns Over the Bill

Waters has taken a different position, warning that approving the CLARITY Act without significant changes could have broader political and regulatory consequences. She argued that passing the legislation in its current form would condone what she described as President Donald Trump’s “worst actions.”

Her comments reflect opposition among some lawmakers who believe the proposal does not adequately address potential conflicts of interest, regulatory oversight, or investor protections.

What Happens Next?

The CLARITY Act’s future will depend on whether lawmakers can reach agreement on the bill’s regulatory framework and address objections from both parties. Key issues include the division of authority between federal agencies and the safeguards that would apply to digital asset markets.

For now, the legislation appears to remain politically unsettled rather than definitively abandoned. Further negotiations will determine whether Congress revisits the measure and whether a revised version can attract enough support for passage.

Kalshi Wins Round One as Court Keeps Election Contracts Alive

Wellermen Image KALSHI WINS ROUND ONE AS COURT LETS ELECTION BETS STAND
A federal appeals panel just refused to freeze a lower-court order that keeps Kalshi’s election contracts alive, giving the platform a short-term victory over the Commodity Futures Trading Commission. The decision signals that judges are unwilling to slam the brakes on a product that could let millions of Americans trade their political views the way they trade oil or wheat. For crypto markets already watching every regulatory skirmish, the case now functions as a live stress test of how far the CFTC’s authority really reaches.

The fight began when Kalshi asked the CFTC to approve “Congressional Control Contracts” that would pay out depending on which party controls the House or Senate after the November election. The agency said no, arguing that election outcomes are too political and not commodities. Kalshi sued, a district judge sided with the exchange, and the CFTC rushed to the appeals court for an emergency stay that would have shut the contracts down immediately. Instead, the D.C. Circuit left the district court’s injunction in place while the full appeal proceeds, effectively letting the market open for now.

Judges focused on whether the CFTC could show “irreparable harm” if trading started. The agency claimed that once dollars change hands on a political event, confidence in regulated markets would collapse. The panel found that argument thin, noting that similar contracts already trade offshore and that Kalshi’s version would be capped, transparent, and under CFTC oversight. Because the government could not prove immediate disaster, the court kept the door open. Kalshi keeps its license to list the contracts; the CFTC keeps its right to appeal but loses the ability to stop trading overnight.

In plain terms, the ruling narrows the CFTC’s emergency powers when it wants to block a new product. The agency still believes it can win on the merits—that election contracts are not commodities and that letting people bet on politics invites manipulation. But the bar for a last-minute injunction just got higher. If Kalshi survives the full appeal, other platforms could argue that any CFTC attempt to shutter novel contracts requires more than just policy dislike.

For crypto, the message is double-edged. A win for Kalshi shows courts willing to push back when regulators stretch definitions of “commodity” or “event contract.” That could give DeFi protocols and prediction-market tokens breathing room, especially if they structure themselves as CFTC-registered entities rather than unregistered securities. Yet the underlying legal question—whether political events can be packaged as tradable instruments—remains unsettled, leaving stablecoin issuers and on-chain betting apps exposed to future enforcement waves. Exchanges now have a precedent to cite when the agency tries to act fast; traders have a reminder that regulatory gray zones can flip green or red on short notice.

The CFTC can still win the war even after losing this battle, but today’s order proves that speed alone won’t decide what counts as a legal market.

Texas Appellate Panel Denies Envy Blockchain’s Bid to Move Fraud Case to Bankruptcy Court

Wellermen Image Court Slaps Envy Blockchain With Texas Mandamus Ruling
Texas appellate judges just forced Envy Blockchain and its co-founders back into state court after the company tried to yank its fraud case into federal bankruptcy proceedings. The Eighth District Court of Appeals in El Paso denied the company’s petition for mandamus, meaning the underlying lawsuit over allegedly fraudulent real-estate transfers will stay in Texas district court rather than migrate to a bankruptcy judge’s docket. For crypto firms already juggling creditors, regulators, and civil plaintiffs, the ruling underscores how hard it can be to park disputes in friendlier federal forums once fraud allegations surface.

The fight began when NV Landco 1 LLC, a land-holding affiliate tied to Envy, transferred parcels to insiders just before creditors came knocking. Plaintiffs claim the moves were classic fraudulent conveyances designed to shield assets from collection. When Envy filed for Chapter 11 protection, the company asked the bankruptcy court to take exclusive jurisdiction over the fraudulent-transfer claims. The state-court plaintiffs pushed back, arguing the transfers were separate from the bankruptcy estate and belonged in Texas courts. The trial judge agreed and refused to relinquish the case, prompting Envy to seek an extraordinary writ of mandamus from the El Paso appeals court.

The three-justice panel ruled that mandamus is an “extraordinary remedy” reserved for clear abuses of discretion, and the trial court’s decision to keep the case did not rise to that level. Because the fraudulent-transfer claims involve third-party recipients and potentially separate property, the judges found no automatic federal preemption. In plain English, the panel told Envy that filing bankruptcy does not automatically freeze every state-law fraud suit connected to its officers or affiliates.

For crypto market participants, the decision is a reminder that bankruptcy filings are no longer a reliable “get out of state court free” card. Plaintiffs alleging fraudulent conveyances can still press claims in front of local judges, exposing company insiders to personal discovery, depositions, and potential asset freezes outside the protective cocoon of federal bankruptcy. That raises litigation risk for exchanges and DeFi protocols whose founders hold side assets, and it could embolden creditors to file parallel state actions before a petition is even docketed.

The upshot: bankruptcy may delay, but it will not erase, state-law accountability for crypto insiders accused of hiding value.

Public Wins: Seventh Circuit Rebuffs CFTC Secrecy in Kraft–Mondelēz Wheat Case

Wellermen Image JUDGES SHUT DOWN CFTC’S BID TO SEAL TRIAL, KEEPING FOOD GIANT CASE PUBLIC

A federal appeals court just handed regulators a blunt “no” on secrecy. The Seventh Circuit refused to let the CFTC hide its upcoming civil trial against Kraft and Mondelēz, ruling that the public deserves to watch how the agency builds its price-manipulation case. Markets took the hint: if the CFTC cannot cloak a simple commodity dispute, its chances of quietly negotiating crypto settlements just shrank.

The case began when the CFTC accused the two food giants of rigging the wheat market in 2011. Kraft and Mondelēz wanted the entire proceeding sealed, arguing that future discovery would expose sensitive pricing strategies. The CFTC agreed to the secrecy, then asked the district court to seal the record. When the lower court balked, the agency petitioned the Seventh Circuit for a writ of mandamus, claiming that any public airing would chill future investigations.

Writing for the panel, Chief Judge Diane Wood rejected the petition outright. The court held that mandamus is an extraordinary remedy, not a shield for regulatory embarrassment, and that the CFTC had failed to show any “irreparable injury” from transparency. The judges stressed that commodity-price manipulation cases touch the public interest at its core—food prices—and secrecy would undermine confidence that the agency is playing fair.

In plain terms, the ruling slams the door on closed-door CFTC enforcement. Regulators can no longer promise targets confidentiality as a bargaining chip; every docket entry, deposition, and exhibit is presumptively open unless a judge finds an overriding need. That precedent travels: crypto exchanges staring down manipulation charges now have case law saying the public gets a front-row seat.

For digital-asset markets the message is double-edged. On one hand, greater transparency may pressure the CFTC to build stronger, evidence-based cases instead of bluffing defendants into settlements. On the other, traders and DeFi protocols lose the strategic comfort of confidential negotiations; every subpoena, wallet trace, and chat log could become headline fodder. Stablecoin issuers and DEX operators should assume their enforcement records will be public unless they can prove concrete competitive harm.

Expect defense counsel to wave this opinion at regulators the next time the CFTC tries to keep a crypto case under seal—because after today, sunlight is the default, not the exception.

×