Fifth Circuit Narrows SEC Power, Rejects Automatic Securities Label for Crypto

Wellermen Image SEC Loses Big on Crypto Classification Battle

A federal appeals court has delivered a major setback to the SEC’s broad regulatory push over crypto, ruling that certain digital assets cannot automatically be labeled “investment contracts” just because they are sold with marketing hype. The decision narrows the agency’s authority and could reshape how exchanges, DeFi protocols, and token issuers operate across the country.

The lawsuit originated when the SEC brought an enforcement action against a crypto firm, alleging unregistered securities offerings tied to its token sales. The company fought back, arguing that the tokens were utility assets—not investment contracts—and that the SEC’s theory stretched the Howey test beyond recognition. The Fifth Circuit agreed to hear the appeal after a lower court sided with the agency, setting up a showdown over how courts should classify digital assets sold to retail traders.

Judges ruled that the mere presence of profit-seeking language in marketing materials does not automatically convert a token into a security. The court emphasized that for an asset to qualify as an investment contract, buyers must reasonably expect profits derived primarily from the efforts of others. The panel found that the SEC failed to prove this expectation was central to the transaction, especially when tokens carried genuine utility or were traded on decentralized platforms. As a result, the enforcement action was significantly curtailed, handing the company a partial but meaningful victory.

The ruling shifts the burden onto the SEC to demonstrate clear investor reliance on promoter efforts rather than assuming it from general marketing language. This raises the bar for future enforcement actions and could force the agency to refine its approach when pursuing token issuers and exchanges.

Crypto markets are likely to interpret this as a regulatory green light for broader product launches and exchange listings, at least in the short term. The decision weakens the SEC’s leverage in settlement negotiations and may embolden DeFi protocols to resist compliance demands that rest on shaky legal footing. Stablecoin issuers and token projects previously wary of U.S. exposure may accelerate product rollouts, while exchanges gain negotiating room on listing standards and custody arrangements.

Traders should watch for a wave of new token filings and exchange announcements testing the limits of this precedent—opportunity exists, but aggressive issuers could still trigger fresh enforcement if facts differ sharply from this case.
CFTC Wins Monex Appeal, Expands Reach Over Leveraged Crypto Margin Trades

Wellermen Image CFTC WINS ON MONEX APPEAL, MARKETS ON EDGE
The Ninth Circuit just handed the CFTC a major enforcement victory in the long-running Monex fraud case, reversing a lower court’s dismissal and reopening the door to civil penalties against the precious-metals dealer. At stake is whether leveraged retail metals contracts sold through a financing subsidiary count as “leveraged transactions” under the Commodity Exchange Act, a question that could ripple through every crypto margin product on U.S. shores.

The case began when the CFTC accused Monex of running a $290 million retail metals Ponzi that relied on undisclosed “margin” loans to let customers trade with ten-to-one leverage. The district judge threw the suit out in 2018, ruling that Monex’s arrangements fell outside the statute because title to the metals technically passed to the customer. On appeal, the Ninth Circuit disagreed, holding that the economic reality of the financing—where Monex retained possession and the customer could never take delivery without paying off the loan—meant these were leveraged retail commodity transactions squarely inside the CFTC’s jurisdiction. The panel also reinstated the antifraud counts, finding that allegations of hidden fees and undisclosed counterparty risk were enough to survive a motion to dismiss.

Monex loses the motion, the CFTC gains momentum, and every U.S. platform offering financed crypto trades now faces renewed regulatory risk. The decision widens the CFTC’s net to cover any margin, leverage, or financing scheme that lets retail customers speculate on commodities—including digital ones—without taking actual possession.

In plain English, the court said regulators can look past paper title to the economics of the deal. If a platform keeps the asset and the customer is betting on price moves with borrowed money, the transaction is likely a regulated, leveraged commodity contract.

For crypto, the ruling tilts authority toward the CFTC on margin products, raises the compliance bar for DeFi protocols that embed leverage, and forces exchanges to decide whether they want to register as futures commission merchants or redesign products to avoid the label. Stablecoin issuers who allow financed trading face the same fork in the road.

Expect platforms to tighten margin rules or add “delivery” mechanics to dodge CFTC oversight, while traders should price in higher compliance costs and potential product shutdowns if they stay on U.S.-facing venues.

DC Circuit Narrows CFTC’s Crypto Authority Over Offshore Trades

Wellermen Image CFTC Loses Key Appeal on Crypto Jurisdiction
The D.C. Circuit just handed the CFTC a clear setback, ruling that the agency overreached when it tried to punish a crypto trader for conduct that happened before any clear rules existed. The decision narrows the CFTC’s authority to chase violations retroactively and signals that courts are willing to push back when regulators stretch old statutes to cover new technology.

Trevor Kitchen was accused of running a fraudulent crypto scheme and manipulating the price of a digital asset that traded on an offshore platform. The CFTC claimed the trades affected U.S. markets and therefore fell under its watch. Kitchen argued that the CFTC had no authority because the underlying asset wasn’t a futures contract and the platform wasn’t registered with the agency. The Commission rejected those arguments, fined him, and barred him from trading. Kitchen appealed.

On review, the three-judge panel sided with Kitchen. The court held that the CFTC could not apply its anti-fraud rules to transactions that were not executed on a registered exchange and did not involve traditional commodity derivatives. Judges emphasized that the agency must show a concrete link to U.S. futures markets before it can bring enforcement actions. Without that link, the Commission’s reach stops at the water’s edge.

In plain English, the ruling tells the CFTC it cannot use its broad enforcement powers to police every crypto trade that might ripple into the United States. If the asset is not a futures contract and the venue is offshore, the agency must prove a direct connection to domestic markets or stay out. The decision does not strip the CFTC of power over actual U.S.-listed crypto futures, but it raises the bar for proving jurisdiction when trades occur abroad.

For exchanges and traders, the case lowers the risk of surprise enforcement when they operate outside CFTC-registered venues. DeFi protocols and offshore platforms gain breathing room, while the agency faces higher evidentiary hurdles if it wants to claim cross-border impact. Stablecoin issuers and spot-market venues also benefit indirectly, because the court refused to treat every digital asset as a commodity under CFTC purview.

Expect regulators to test new statutory language or push for clearer legislation rather than rely on expansive readings of existing rules.

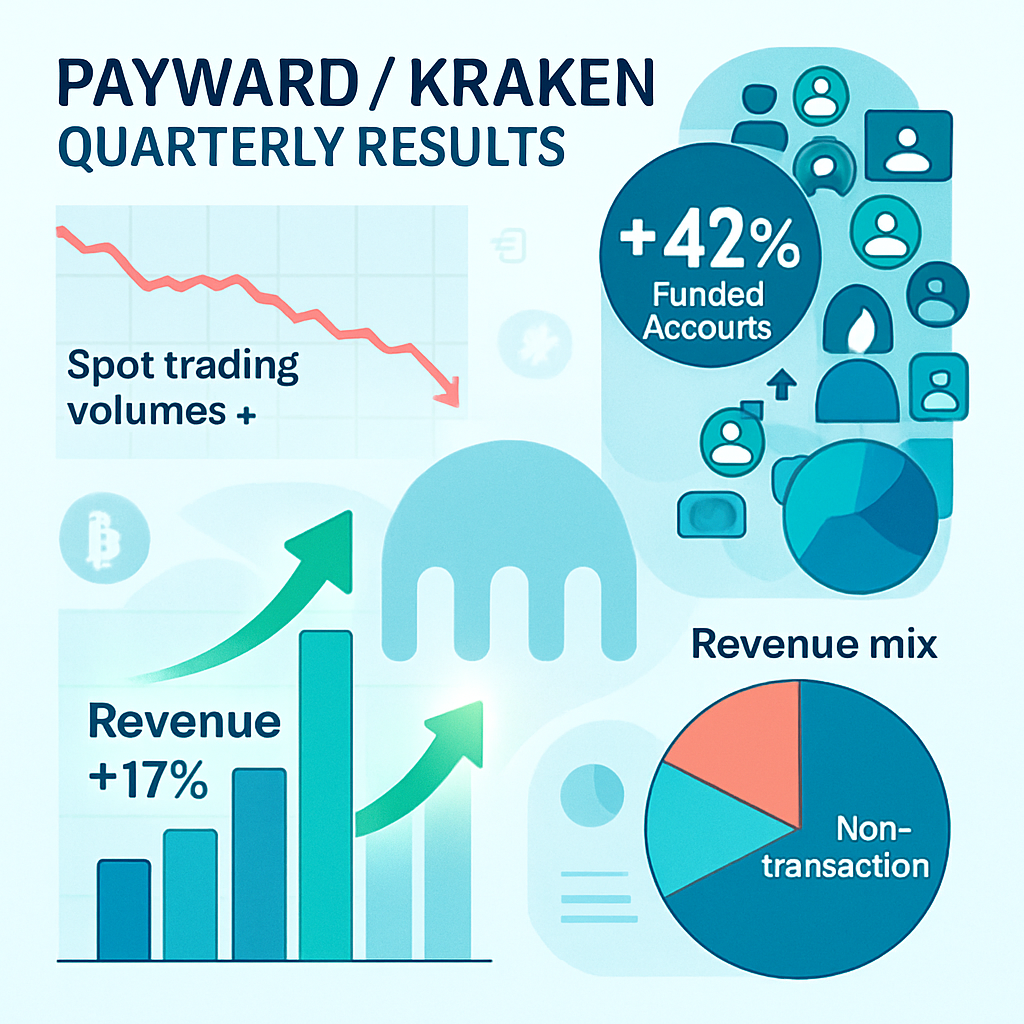
– Payward (Kraken) Revenue Rises 17% as Q2 Volume Falls – Kraken Parent Payward Revenue Up 17%, Q2 Volume Drops – Payward (Kraken) Revenue Up 17% as Q2 Trading Falls

Payward, the parent company of cryptocurrency exchange Kraken, reported a 17% increase in second-quarter revenue despite a decline in spot trading volumes. The company said funded accounts rose 42%, and a larger share of revenue came from non-transaction activities.

Revenue Growth Amid Softer Trading

The second quarter saw weaker spot trading activity, yet Payward expanded overall revenue by 17%. The performance suggests the company is less reliant on trading fees than in prior periods, helping offset the impact of subdued market volumes.

User Base Expansion

Payward reported a 42% increase in funded accounts, indicating stronger customer acquisition and engagement. A larger active user base typically supports recurring platform activity and can provide a buffer when trading conditions are less favorable.

Diversification Beyond Transaction Fees

A growing portion of Payward’s revenue came from non-transaction sources, reflecting efforts across the crypto exchange sector to diversify income beyond spot trading. Expanding into services outside pure trading can help stabilize results through varying market cycles.

CFTC Wins Major Crypto-Fraud Appeal: Crombie Ordered to Pay $2.8M for Bitcoin Futures Scheme

Wellermen Image CFTC WINS APPEAL — CROMBIE’S CRYPTO FRAUD STANDS
The Ninth Circuit just handed the CFTC a clean victory in its first major crypto-fraud case, affirming that a California man who ran a Ponzi scheme in Bitcoin futures must pay $2.8 million in restitution and penalties. The ruling matters because it locks in the agency’s power to police deceptive conduct even when the underlying instruments are novel digital assets.

James Devlin Crombie posed as a Bitcoin-trading wizard, promising 250 percent annual returns and 100 percent capital protection to draw in more than two hundred investors. Instead of trading futures contracts as advertised, he used new deposits to pay earlier victims and diverted the rest to his personal expenses. After a bench trial, the district court found that Crombie had violated the Commodity Exchange Act’s antifraud provisions and ordered him to disgorge his ill-gotten gains.

On appeal, Crombie argued that Bitcoin futures were outside the CFTC’s reach and that the agency had failed to prove the existence of actual futures contracts. The three-judge panel rejected both claims in a terse, unanimous opinion. It held that the CFTC has statutory authority over any futures contract tied to a commodity—including digital assets—and that Crombie’s marketing materials alone were enough to establish that he solicited trades in Bitcoin futures. Because the fraud finding rested on uncontested evidence of misrepresentations and client harm, the court saw no reason to disturb the judgment.

The decision is straightforward: the CFTC can bring enforcement actions against anyone who lies about crypto-related derivatives, regardless of whether the underlying asset itself is classified as a commodity. That precedent removes any lingering doubt about the agency’s jurisdiction in digital-asset futures markets and signals that future defendants will not escape liability by hiding behind technological novelty.

For traders and exchanges, the ruling tightens the margin of safety around marketing claims. Promises of outsized returns or guaranteed principal now carry clear legal risk, even in decentralized or offshore environments, because the CFTC can follow the money wherever U.S. investors are solicited. DeFi protocols that offer leveraged products should expect heightened scrutiny of their sales language, while centralized platforms gain a compliance roadmap they can cite to justify stricter marketing reviews.

The case also underscores that restitution orders travel with the fraudster: once liability is established, collecting the judgment becomes a game of asset tracing rather than legal argument. Market participants who view regulatory gray areas as moats should recalibrate—courts are now telling them those moats are filling in fast.

Judge Tosses Bulk IRS Crypto Seizures, Orders Return of Millions in Digital Assets

Wellermen Image JUDGE TOSSES IRS CRYPTO ACCOUNT SEIZURE, FORCING NEW RULES
A federal judge has ordered the IRS to return millions in crypto after ruling that bulk warrants targeting 24 anonymous wallets violated the Fourth Amendment. The decision marks the first time a court has suppressed digital-asset seizures on grounds that investigators failed to show probable cause for each account, sending an immediate chill through enforcement circles and a surge of relief through exchanges and traders who store value in self-custody wallets.

The case began when IRS agents traced ransomware payments to a cluster of cryptocurrency addresses and asked a magistrate judge for a single warrant covering every wallet that touched tainted funds. Defense lawyers argued that the sweep amounted to a digital dragnet, grabbing clean coins alongside dirty ones. Judge Dabney L. Friedrich agreed, holding that the government had not demonstrated individualized suspicion for each account and that the ensuing seizures were therefore unconstitutional.

Because the wallets contained both tainted and untainted assets, the court suppressed the entire seizure and ordered the government to relinquish control. Prosecutors had hoped to use the forfeited crypto to compensate victims; instead, those assets now return to unknown owners, some of whom may never surface.

In plain terms, the ruling says investigators can no longer lump dozens of blockchain addresses into one warrant without proving each one is probably linked to crime. That standard raises the bar for future crypto seizures and could force agencies to rely on narrower warrants or on civil forfeiture actions that carry their own due-process hurdles.

For markets, the decision tilts power away from bulk enforcement and toward privacy-preserving self-custody. Exchanges that already flag high-risk deposits may now face pressure to tighten compliance, while DeFi protocols and mixers could see renewed volume as users seek to avoid address-level surveillance. Stablecoin issuers, however, remain exposed: their off-chain reserve accounts are still reachable by traditional subpoenas, so any compliance savings won here will not extend to tokens that live inside regulated banking rails.

Traders now have a precedent to cite when the government comes knocking with a master wallet list; whether that precedent survives appeal will determine if the next bear market also features another round of headline-grabbing seizures.

Court Dashes SEC’s BNB-as-Security Theory, Binance Wins Narrow Victory

Wellermen Image Court Slaps Brakes on SEC’s Binance Assault
Federal judge Amy Berman Jackson just shredded the SEC’s sweeping lawsuit against Binance, tossing out the agency’s headline claim that Binance’s BNB token is a security. The ruling guts the SEC’s theory that almost every crypto token automatically falls under its jurisdiction, handing the industry its clearest legal win in years and instantly shifting the balance of power between Washington and digital-asset markets.

The case began in June 2023 when the SEC accused Binance and its U.S. affiliate of operating an unregistered exchange and offering unregistered securities. Binance fought back, arguing the agency was stretching the 1933 Securities Act beyond recognition. Judge Jackson agreed on the critical point: BNB, sold to the public in 2017, was never marketed as a profit-sharing investment in Binance’s business and therefore does not meet the Howey test for an “investment contract.” She left open the possibility that later sales or staking programs could still be securities, but the core token classification that terrified the entire sector is now in doubt.

The decision leaves the SEC bruised but not beaten. Claims tied to Binance’s staking product and unregistered exchange activities survive, so the case moves forward on narrower grounds. Still, the judge’s refusal to label BNB a security sets precedent other courts are likely to cite, and it signals that judges are no longer willing to rubber-stamp the agency’s “everything is a security” narrative.

In plain English, the court told the SEC it cannot simply declare a token a security because the issuer once raised money; regulators must prove investors were led to expect profits derived solely from the promoter’s efforts. That evidentiary bar just got higher for the agency and lower for token issuers.

The ruling chips away at the SEC’s de-facto authority over token classification and pushes oversight pressure toward Congress and the CFTC. Decentralized projects that never promise enterprise profits gain breathing room, while exchanges and DeFi protocols that offer staking or yield products still face compliance risk. Traders now see reduced headline risk for major exchange tokens, but the decision also highlights that staking services could still trigger registration—meaning platforms may quietly dial back such offerings until clearer rules emerge.

Bottom line: the SEC just lost its blanket leverage over token issuers, and markets will price that relief until the next enforcement headline hits.

Bitcoin Hashrate Drops 17% From Record as Miners Chase AI

Bitcoin’s network hashrate has slipped as much as 17% below its all-time high, according to CryptoQuant data, as several publicly listed miners redirect power and capital toward artificial intelligence (AI) and high-performance computing (HPC) data centers rather than expanding new bitcoin mining capacity.

Hashrate Pulls Back From Record Levels

Hashrate measures the aggregate computing power securing the Bitcoin blockchain, typically expressed in exahashes per second (EH/s). A retreat from peak levels indicates fewer machines are actively hashing or that miners are curtailing operations. While the network remains near historically elevated ranges, the pullback marks a notable shift after a prolonged climb to record highs earlier this year.

Short-term hashrate fluctuations are common and can be driven by miner economics, energy market conditions, infrastructure maintenance, or regional curtailments. The latest decline aligns with reports that some operators are reallocating resources to alternative compute workloads.

Miners Pivot to AI and HPC

Publicly traded mining firms have increasingly outlined AI and HPC strategies over the past two years, citing strong demand for data center capacity. These initiatives can involve repurposing existing sites, power contracts, and operational expertise to support GPU-intensive workloads that may offer different revenue profiles than bitcoin mining.

The shift does not necessarily imply a permanent exit from mining, but it reflects changing capital allocation priorities amid competitive pressures, hardware upgrade cycles, and post-halving revenue compression for miners.

Difficulty and Security Considerations

Bitcoin’s mining difficulty adjusts roughly every two weeks to target a 10-minute block interval. If lower hashrate persists, upcoming difficulty adjustments could ease, partially offsetting margin pressures for remaining miners. Despite the recent decline, the network’s security model remains anchored in large-scale, globally distributed hashrate and automatic difficulty recalibration.

What to Watch

  • Future hashrate trends and difficulty adjustments in response to miner behavior.
  • Capital expenditure and hosting announcements from major mining operators.
  • Energy market dynamics and data center build-outs that could influence miner resource allocation.
  • Deployment timelines for next-generation ASICs and potential impacts on fleet efficiency.

Delaware Court Rejects Contract Shield for Crypto Token Claims, Signals Stricter Securities Scrutiny

Wellermen Image Court Nixes Crypto Firm’s Contract Claim, Signals Tighter Scrutiny for Token Deals
Delaware’s Superior Court just gutted a crypto startup’s lawsuit, refusing to let a token-distribution contract serve as a shield against fraud claims. The ruling matters because it tells founders and exchanges that Delaware judges will not rubber-stamp private agreements that try to bury securities-law risk in code or fine print.

Diamond Fortress Technologies and its CEO Charles Hatcher sued their former partner over a deal that called for the creation and distribution of a proprietary token. The contract contained broad release clauses and a Delaware choice-of-law provision. Plaintiffs argued those clauses blocked the partner from bringing fraud or securities claims in another forum. The partner countered that the token had the hallmarks of an unregistered security and that the contract could not erase federal or state investor-protection rules.

The court agreed. It held that contractual releases cannot immunize parties from liability under the securities laws, even if the agreement is governed by Delaware law. Because the token’s economic realities looked more like an investment contract than a simple utility, the judge refused to dismiss the fraud counts. The plaintiffs therefore lose their procedural advantage and must now litigate the substance of whether the token sale violated registration and anti-fraud provisions.

In plain English, Delaware just reminded the industry that calling a token a “utility” or burying liability waivers in smart-contract code will not automatically defeat securities claims. The ruling narrows the protective zone that sophisticated parties thought they could draft around federal and state regulators.

For markets, the decision tilts power toward the SEC and plaintiff bar. Exchanges listing similar tokens face elevated due-diligence costs and potential secondary-liability theories. DeFi protocols that rely on click-wrap or on-chain disclaimers lose a layer of insulation. Traders holding such tokens should price in higher litigation risk and possible rescission claims.

Founders who still believe Delaware paperwork can outrun federal securities rules are betting against a precedent that now carries the state’s most business-friendly court’s seal.

DC Circuit Slams SEC on Bitcoin ETF Double Standard; Grayscale Wins Rehearing

Wellermen Image Court Rejects SEC’s Bitcoin ETF Double Standard
The D.C. Circuit just handed Grayscale a decisive win and the SEC a public rebuke. The three-judge panel ruled that the Commission’s refusal to convert the Grayscale Bitcoin Trust into an exchange-traded product was arbitrary and capricious, because the agency had already green-lit nearly identical bitcoin futures ETFs. Markets are already pricing in a higher probability of spot-bitcoin approval before year-end.

The case began when Grayscale asked the SEC to convert its existing trust—already holding more than $20 billion in actual bitcoin—into an ETF that would trade on NYSE Arca. The Commission turned the application down last year, arguing that the trust’s structure created fraud and manipulation risks that futures-based ETFs somehow avoided. Grayscale sued, saying the SEC was applying two different standards to products that both ultimately track the same underlying asset. On August 29, the appeals court agreed, holding that the SEC had failed to explain why one product’s safeguards were adequate while the other’s were not. The judges sent the matter back to the agency with instructions to reconsider the application under a consistent standard.

Grayscale wins the right to another hearing; the SEC loses the ability to treat spot and futures products as legally distinct without fresh justification. Existing spot-bitcoin ETP filings from BlackRock, Fidelity, and Invesco now carry fresh momentum, while the Commission must either approve them or craft a new rationale that can survive judicial review. For traders, the ruling lowers the perceived regulatory barrier to owning bitcoin through mainstream brokerage accounts.

The decision narrows the SEC’s discretion to reject spot products solely on manipulation concerns when comparable futures vehicles already trade. That shift matters for token classification fights, because the same logic could apply to ether or other commodities whose futures already clear on CFTC-regulated venues. Exchanges and market-makers are already modeling tighter spreads and deeper liquidity once a spot ETF launches, while DeFi protocols may face incremental competition as traditional capital gains easier on-ramps.

The ruling doesn’t guarantee approvals, but it makes outright denial far harder to defend.

CFTC Triumph in Donelson Appeal Signals Wider Crypto Derivative Oversight

Wellermen Image CFTC Wins Key Ruling in Donelson Appeal, Crypto Markets Brace for Wider Reach
The Seventh Circuit just handed the Commodity Futures Trading Commission a sweeping victory, affirming that James Donelson’s unregistered trading advice operation violated federal commodities law. For crypto traders and DeFi operators, the decision sharpens the agency’s power to pursue unregistered advisors who touch digital-asset derivatives—even when those assets sit in gray regulatory zones. The ruling lands just as markets price in fresh enforcement risk.

Donelson ran an online service promising futures-trading signals and automated strategies, collecting fees from retail clients without registering as a commodity trading advisor. The CFTC sued, arguing he needed registration and had to follow disclosure rules. Donelson countered that his signals were “educational,” not advisory, and that the underlying crypto products fell outside the CFTC’s reach. A district court sided with the agency; Donelson appealed.

Writing for a unanimous Seventh Circuit panel, the judges held that once a person offers trading advice on futures or swaps for compensation, registration is mandatory—even if the advice is delivered through software and even if the underlying tokens are also securities. The court rejected Donelson’s attempt to carve crypto out of the statute, ruling that the CFTC’s jurisdiction over derivatives survives regardless of whether the spot tokens themselves are commodities. The panel also refused to narrow the agency’s definition of “advice,” making it harder for signal-sellers to dodge oversight.

In plain English, the decision tells anyone peddling trading bots, paid newsletters, or algorithmic signals tied to futures or swaps that they must register with the CFTC or risk civil penalties, disgorgement, and injunctions. Registration brings disclosure duties, capital requirements, and direct regulatory supervision—costs many small operators cannot meet.

For crypto markets, the ruling broadens the CFTC’s footprint at the exact moment the agency is already sparring with the SEC over token classification. Expect heightened compliance costs for exchanges that list derivatives and for DeFi protocols offering leveraged products. Stablecoin issuers that embed derivatives-like mechanics could now face advisor-registration questions. Traders relying on third-party signals may see fewer options and higher fees, while well-capitalized firms gain a moat as barriers to entry rise.

Bottom line: unregistered crypto signal services just became a lot riskier, and the CFTC just secured another precedent that could stretch its authority over decentralized derivatives.

– What Happened in Crypto Today – Today in Crypto: Key Moves and News – Crypto Today: Top Headlines – Today’s Crypto Update: Major Moves – Cointelegraph News: Crypto Today’s Highlights

This daily briefing highlights the key themes shaping the cryptocurrency market, covering Bitcoin price drivers, blockchain developments, decentralized finance (DeFi), Web3 innovation, and regulatory actions influencing digital assets.

Market Drivers to Watch

Bitcoin and major altcoins continue to react to macroeconomic signals, liquidity conditions, and sentiment across risk assets. Intraday moves are often influenced by:

  • Institutional flows, including exchange-traded products and derivatives positioning
  • On-chain metrics such as exchange balances, realized volatility, and network activity
  • Macro indicators, including interest-rate expectations, inflation data, and dollar strength

Regulation and Policy Landscape

Regulatory developments remain a defining force for market structure and investor access. Key areas include:

  • Enforcement actions and guidance from securities and commodities regulators
  • Licensing and oversight frameworks emerging in major jurisdictions
  • Compliance standards for stablecoins, exchanges, and custody providers

DeFi and Web3 Developments

DeFi protocols and Web3 applications continue to evolve, with progress centered on:

  • Liquidity, collateral management, and security upgrades across lending and trading platforms
  • New use cases for tokenization, identity, and payments
  • Ecosystem growth on layer-2 networks aiming to reduce fees and improve throughput

Why It Matters

Price action in Bitcoin and broader crypto assets reflects a blend of market structure, technology adoption, and policy clarity. Monitoring these factors helps contextualize volatility, identify emerging trends, and assess the trajectory of digital asset infrastructure.

Third Circuit Forces SEC to Answer Coinbase’s Crypto Rulemaking Petition

Wellermen Image COINBASE SLAPS SEC WITH CIRCUIT RULING
The Third Circuit just handed Coinbase a procedural win that could slow the SEC’s crypto enforcement machine. The court ordered the Commission to answer the exchange’s petition for rulemaking instead of brushing it aside, marking the first time a federal appeals court has forced the agency to confront its own refusal to clarify digital-asset rules.

The case began when Coinbase filed a formal petition asking the SEC to write clear regulations for crypto trading, custody, and staking. The Commission sat on the request for more than a year, then denied it in a two-page letter. Coinbase appealed, arguing that the agency’s silence and later brush-off violated the Administrative Procedure Act’s requirement for reasoned decision-making. A three-judge panel agreed, holding that the SEC must provide a substantive response rather than treating the petition as a nuisance filing.

In practical terms, Coinbase wins breathing room while the SEC is told to justify, in public, why existing securities rules should—or should not—cover tokens, wallets, and staking rewards. The exchange loses nothing on the merits; it simply gains a written record it can use in future fights. The SEC loses the luxury of selective silence and must now weigh the political and legal cost of either issuing guidance or doubling down on case-by-case enforcement.

The ruling narrows the SEC’s room to maneuver without new legislation. Any future denial will have to survive judicial review, which raises the odds that the Commission will either propose token-specific rules or concede that some crypto activities fall outside its jurisdiction. That uncertainty tilts power toward exchanges and DeFi protocols that have long argued the agency is regulating by ambush.

Exchanges now have a template for challenging enforcement-first tactics, while the SEC’s threat to treat most tokens as unregistered securities loses some of its deterrent effect until the agency produces a coherent framework. Traders should expect continued volatility as lawyers trade filings and the market prices in the possibility—still only a possibility—that comprehensive crypto rules could emerge from this forced dialogue.

The decision shifts the battlefield from courtroom to comment file; whoever controls the narrative in that file will shape whether crypto remains in enforcement limbo or graduates to a regulated market.

Gemini Q2 Net Loss $108M Despite 37% Revenue Growth

Gemini reported a second-quarter net loss of $108 million despite a 37% increase in revenue, as growth in credit card and staking services offset a steep decline in trading activity. Exchange revenue fell 38% and trading volumes dropped by roughly two-thirds.

Q2 Performance Snapshot

  • Net loss: $108 million for the quarter.
  • Revenue growth: Up 37% in the period.
  • Exchange revenue: Down 38% as trading activity weakened.
  • Trading volume: Declined by about two-thirds.

Services Revenue Offsets Trading Slump

Credit card and staking revenue drove the company’s services growth during the quarter, helping to counter a sharp pullback in exchange-related income. The results highlight Gemini’s increasing reliance on non-trading products to diversify revenue beyond transaction fees.

Context

Gemini, a U.S.-based cryptocurrency exchange, has expanded its suite of services to include consumer payments and yield-generating products. The latest results suggest that ancillary offerings are becoming more important as spot trading volumes fluctuate.

Bitcoin Dips to Fresh August Lows as Binance Longs Face Cleanout

Bitcoin’s latest pullback coincided with a drop in futures open interest on Binance, signaling a reduction in leveraged exposure as analysis from CryptoQuant pointed to mounting pressure on long positions.

Binance Futures Open Interest Slides With Price

Open interest reflects the total value of outstanding futures contracts. A decline in open interest alongside a falling Bitcoin price typically indicates de-leveraging, often driven by long positions being closed or liquidated rather than an influx of new short exposure.

As the largest crypto exchange by derivatives volume, shifts in positioning on Binance can have an outsized impact on market liquidity and short-term price dynamics across the broader Bitcoin market.

Leverage Longs Face Mounting Pressure

CryptoQuant’s analysis highlights building stress on leveraged longs. When prices fall and open interest drops, it can suggest that bullish bets are being forced out, increasing the risk of liquidation cascades if downside persists. Such conditions often amplify intraday volatility.

Why It Matters

Derivatives positioning can accelerate price moves in both directions. A continued squeeze on longs may expose lower liquidity areas, while a thorough reset in leverage can also set the stage for more stable price action once forced selling subsides.

Key Indicators to Watch

  • Futures funding rates and basis to gauge directional leverage.
  • Open interest and liquidations across major venues for signs of de-risking or re-leveraging.
  • Spot exchange flows and volumes to assess underlying demand.
  • Macro risk sentiment, including equity and dollar moves, that can influence crypto volatility.
×