Fifth Circuit Halts SEC’s Surprise Token Securities Push, Demands Clear Rules

Wellermen Image Court Slams SEC, Hands Crypto Major Legal Win

The Fifth Circuit just ruled the SEC cannot retroactively declare a crypto token a security after years of silence and market reliance. The decision guts the agency’s “we’ll know it when we see it” enforcement style and hands the industry a rare moment of breathing room. For traders and exchanges still reeling from years of regulatory whiplash, the opinion is the clearest signal yet that courts will no longer rubber-stamp the SEC’s expanding definition of “investment contract.”

The fight began when the SEC charged a crypto project with selling unregistered securities, arguing its token met the Howey test. The company fought back, claiming the agency had never warned the industry that such tokens were securities and had in fact green-lit similar products through inaction. On appeal, the Fifth Circuit focused on fair notice: whether the SEC’s sudden enforcement violated due process when the same agency had stayed silent for years. The judges ruled that the SEC’s enforcement-by-surprise crossed a constitutional line and that the agency must give market participants clear rules before punishing them.

The SEC loses the case and the power to spring enforcement actions on long-standing market practices. The crypto project wins, but more importantly, every token issuer and exchange that relied on the agency’s past inaction gains a shield. Going forward, the SEC will have to issue explicit guidance or rulemaking before it can label tokens securities and bring enforcement actions. The ruling does not erase the Howey test, but it forces the agency to use it prospectively, not as an after-the-fact trap.

In plain English, the court told the SEC it cannot change the rules of the game mid-match. If the agency wants to treat tokens as securities, it must say so clearly and in advance. Vague speeches and enforcement-first tactics no longer pass constitutional muster in the Fifth Circuit.

The decision shifts power away from the SEC and toward exchanges and DeFi protocols that can now argue lack of fair notice when facing enforcement. Stablecoin issuers and token projects gain leverage in settlement talks, while traders may see reduced delisting pressure on tokens previously deemed “at risk.” CFTC authority over commodities remains untouched, but the ruling sharpens the line between what the SEC can police and what it must leave alone until it writes new rules. Decentralized projects that never registered or sought guidance are the biggest immediate winners.

Exchanges operating in the Fifth Circuit now have precedent to push back against enforcement letters that feel like regulation by ambush, while traders should watch for a wave of projects testing the limits of this new fair-notice defense.
Delivery Defines Victory: Ninth Circuit Narrows CFTC Authority in Monex Metals Case

Wellermen Image COURT HAMMERS CFTC IN MONEX FRAUD CASE
The Ninth Circuit just gutted the CFTC’s attempt to police a California precious-metals dealer under new Dodd-Frank anti-fraud rules, holding that retail leveraged metals transactions are not “retail commodity transactions” when the seller actually stores and delivers the metal. The decision reins in an agency that had claimed sweeping power to treat almost any financed commodity deal as a regulated futures contract.

The case began when the CFTC sued Monex Credit, Monex Deposit, and related firms in 2017, alleging that the company’s “Atlas” program—which lets retail customers buy gold, silver, and other metals on 25-to-1 margin—was a fraudulent scheme that should be shut down. The agency argued that even though customers could take physical delivery, the transactions were functionally futures because most buyers never requested delivery and simply traded on paper. Monex countered that its contracts always offered real delivery and therefore fell outside the CFTC’s post-2010 “retail commodity transaction” authority.

Writing for a unanimous three-judge panel, the Ninth Circuit agreed with Monex. The court zeroed in on the statutory definition of a retail commodity transaction, which applies only when precious metals “are, or are to be, delivered to the purchaser” within 28 days. Because Monex’s contracts gave customers an unqualified right to demand physical delivery, the deals satisfied that test—even if few customers exercised it. The panel rejected the CFTC’s “economic reality” test that would have looked past the contracts to the trading behavior of customers.

The ruling instantly narrows the CFTC’s reach over any dealer offering financed physical commodities with genuine delivery options. It also creates a clear circuit split with the Seventh Circuit, which used a broader reading in a 2018 FOREX case, setting up a likely Supreme Court showdown on how far Dodd-Frank’s retail-commodity provisions extend.

For crypto markets, the decision is a flashing yellow light. The same statutory language the CFTC tried to stretch against Monex is the one it now invokes against DeFi protocols and token issuers that let users post margin or borrow assets. If physical-delivery loopholes can gut CFTC oversight in metals, expect lawyers for exchanges and on-chain lending platforms to argue that programmatic delivery rights—or even the theoretical ability to withdraw—similarly removes their products from the agency’s grasp. Stablecoin issuers that promise redeemability, and DEXs that offer leveraged trading with withdrawal rights, now have fresh precedent to cite when the CFTC comes knocking.

The Monex decision shows how a single clause about “actual delivery” can redraw regulatory maps overnight; traders betting that the CFTC will dominate every leveraged product should recalibrate before the next enforcement wave.

Crypto Trader Triumphs as D.C. Circuit Tosses CFTC Case Over DeFi Platform

Wellermen Image CFTC Loses on Appeal: Crypto Trader Beats Agency Overreach
Trevor Kitchen just won a landmark appeal that could reshape how the CFTC polices crypto futures. The D.C. Circuit tossed the agency’s enforcement order, ruling that Kitchen’s decentralized trading platform falls outside its jurisdiction. The decision signals a potential crack in the CFTC’s long-standing claim of broad authority over digital asset markets.

The case began when the CFTC fined Kitchen for operating an unregistered swap execution facility. Kitchen argued his platform was a peer-to-peer protocol without a central operator, so it didn’t meet the statutory definition of an exchange. The agency countered that any system facilitating crypto derivatives should be regulated, regardless of decentralization. The judges sided with Kitchen, holding that the CFTC must prove actual control or custody before asserting jurisdiction.

The court’s opinion stressed that the Commodity Exchange Act was written for traditional intermediaries, not code-based protocols. Kitchen’s victory means the CFTC can’t simply label decentralized platforms as “facilities” without evidence of centralized decision-making. This ruling immediately undercuts pending enforcement actions against similar DeFi protocols.

In plain English, the decision forces the CFTC to draw a sharper line between platforms it can regulate and those it cannot. If a protocol truly operates without a central party holding funds or dictating rules, the agency’s reach may stop at the code. This narrows the CFTC’s leverage in negotiations with DeFi teams and could slow enforcement timelines across the sector.

The ruling hands exchanges and traders breathing room, but it also sharpens the regulatory spotlight on custody and control. Projects that can credibly prove decentralization may dodge CFTC registration, while those with hidden admin keys or treasury control remain exposed. Stablecoin issuers and futures desks will watch closely—any perceived centralization could invite fresh scrutiny.

Watch for copycat lawsuits and a likely CFTC appeal; the next six months will decide whether this is a one-off win or the start of a broader judicial pushback against agency expansion.

Bitcoin Small Holders Sell as 69,494 Wallets Exit Before $85K Rally

Bitcoin climbed above $85,000 after a decline in smaller-holder wallet groups during the July–August downturn. On-chain analytics platform Santiment said the contraction may have reduced reactive selling pressure before the cryptocurrency’s latest recovery.

Smaller Bitcoin Wallet Groups Contract

According to Santiment, 69,494 wallets disappeared from two balance groups associated with smaller Bitcoin holders during the market decline. The data suggests that some smaller participants reduced their exposure or moved their holdings into other wallet categories before Bitcoin rebounded.

The contraction occurred while Bitcoin was under pressure in July and August. Santiment described the period as a capitulation phase, in which more reactive market participants exited or reduced their positions.

Capitulation May Have Reduced Selling Pressure

Santiment argued that the earlier sell-off may have helped clear short-term selling pressure from the market. With fewer smaller-holder wallets represented in the affected balance groups, the supply available for immediate selling may have declined as Bitcoin began to recover.

However, wallet-count changes do not necessarily mean that individual investors permanently left the market. Wallets can move between balance categories as holdings change, and users may also consolidate funds across addresses.

Bitcoin Recovers Above $85,000

Bitcoin’s move above $85,000 followed the reduction in smaller-holder exposure highlighted by Santiment. The analysis offers an on-chain explanation for the timing of the rebound, but wallet activity remains only one factor influencing Bitcoin’s price.

Market liquidity, investor demand, macroeconomic conditions and activity among larger holders can also affect the direction and strength of a rally.

CFTC Wins Crombie Appeal: Ninth Circuit Rules Crypto Contracts Are Commodities Under the CEA

Wellermen Image CFTC WINS CROMBIE APPEAL — COMMODITIES DEFINITION UPHELD
The Ninth Circuit has affirmed a district-court judgment against James Devlin Crombie, confirming that the CFTC can pursue unregistered operators who trade virtual currencies that function as commodities. The ruling strengthens the agency’s reach over crypto futures, margin trading, and any instrument that meets the broad definition of “commodity” under the Commodity Exchange Act.

Crombie ran an online platform that allowed customers to trade Bitcoin contracts on margin. The CFTC sued, alleging he operated an unregistered futures commission merchant and a common-enterprise pool. Crombie countered that Bitcoin was not a commodity, so the CFTC had no jurisdiction. The district court disagreed, granted summary judgment, and ordered restitution and a trading ban. Crombie appealed, asking the Ninth Circuit to narrow the statutory definition.

The three-judge panel held that the CEA’s definition of “commodity” is deliberately open-ended and includes “all services, rights, and interests” in which contracts for future delivery are dealt. Because Crombie’s contracts settled in Bitcoin, and Bitcoin is something bought and sold in future-delivery markets, it qualifies. The panel rejected Crombie’s claim that only “hard” commodities like wheat or oil count. It also found that operating a leveraged trading platform without registration violated the CEA, regardless of whether the underlying asset is tangible.

In plain terms, the court told crypto-platform operators that if your product lets customers speculate on future price moves with leverage, you are inside the CFTC’s lane. Registration, disclosure, and anti-fraud rules apply. The decision does not speak to spot Bitcoin sales or non-leveraged DeFi protocols, but it removes one more argument operators have used to stay out of federal oversight.

The ruling tilts regulatory gravity toward the CFTC for any derivatives-style crypto product. Exchanges offering perpetual swaps or leveraged tokens now face clearer registration triggers, while spot markets and non-custodial protocols remain in a grayer zone. Traders should expect more enforcement notices citing this precedent when platforms ignore CFTC rules. Stablecoin issuers are indirectly affected: if their token serves as settlement collateral on a leveraged platform, that platform must register.

Bottom line: treat anything that smells like futures or leverage as a regulated commodity until the agencies say otherwise.

IRS Seizes 24 Crypto Wallets in Civil Forfeiture, Setting a New Frontier for Digital Assets

Wellermen Image Court Seizes 24 Crypto Wallets, Signals IRS Gets First Crack at Digital Assets
The IRS just won the right to grab twenty-four cryptocurrency accounts outright, and the ruling lands like a warning shot across every wallet in America. In a single stroke, the government converted a tax investigation into an asset grab that never needed a criminal conviction first. Traders who thought their keys meant privacy now know the IRS can turn a subpoena into ownership.

The case started when IRS agents traced suspicious blockchain activity to accounts they believed belonged to one person dodging taxes. Instead of indicting that person, the government filed a civil forfeiture complaint directly against the wallets themselves. The twist came when the court treated cryptocurrency like cash in a briefcase, not some new asset class requiring special rules. The judge accepted the IRS’s paperwork at face value and ordered the accounts forfeited because no one showed up to claim them.

Judges ruled that the IRS could seize the accounts under civil forfeiture statutes that normally target drug money or fraud proceeds. The accounts’ owner never responded, so the court treated silence as surrender. The government wins clean title; the account holder loses everything without ever stepping into a courtroom. Nothing in the opinion questions whether crypto deserves different treatment, which means the precedent now travels.

In plain English, the IRS can open a civil case against digital wallets, publish a notice, and—if no one objects—take the coins. That shortcut bypasses the slower, harder path of proving tax evasion in criminal court. It also tells exchanges and custodians that a subpoena plus a forfeiture notice can freeze or drain balances before their customers even know they’re targets.

The decision widens the IRS’s toolkit without touching the SEC or CFTC, yet it tightens the net around traders who keep coins on U.S.-facing platforms. Exchanges now face louder demands for wallet data, and DeFi protocols that touch American users may see similar forfeiture actions migrate on-chain. Stablecoin issuers, already under pressure to freeze addresses, just received another reason to honor government requests fast.

Every trader now carries the extra risk that a silent IRS filing can turn private keys into government property overnight.

SEC Secures Landmark Injunction Against Binance, Freezes U.S. Assets

Wellermen Image SEC Slams Binance with Landmark Injunction as Crypto Crackdown Escalates
A federal judge just handed the SEC a sweeping victory, ordering Binance to halt unregistered securities offerings and freezing assets tied to the exchange’s U.S. operations. The ruling signals that the world’s largest crypto platform can no longer pretend U.S. securities law doesn’t apply to tokens it lists or the services it sells stateside. Markets are already bracing for a broader regulatory storm.

The case began when the SEC sued Binance Holdings and its American arm in June, accusing them of offering unregistered securities, operating an unlicensed exchange, and commingling customer funds with corporate assets. Binance fought back, claiming its tokens were commodities and that its offshore structure kept it beyond U.S. reach. The court rejected those defenses outright, ruling that BNB and several other tokens met the Howey test and therefore qualified as securities. The judge also found that Binance.US likely violated custody rules by routing customer assets offshore without proper disclosure.

Binance loses the ability to onboard new U.S. users and must unwind existing margin and staking programs that the court labeled unregistered securities offerings. Meanwhile, the SEC gains momentum and precedent for treating most altcoins as securities, expanding its jurisdiction over offshore platforms that serve American traders. Traders lose access to certain products, but the ruling also clarifies the rules of the road, potentially reducing gray-area risk for compliant players.

In plain terms, the court said Binance can’t sell securities to U.S. investors without registering, and the exchange’s attempt to wall itself off from American oversight failed. The decision tightens the definition of “decentralized enough” to escape SEC oversight and puts every token sponsor and exchange on notice that listing alone can trigger liability.

The ruling strengthens the SEC’s hand against other large platforms and could chill listings of tokens that resemble investment contracts. It also raises the stakes for stablecoin issuers and DeFi protocols that offer yield or staking, since those features were central to the Binance findings. Expect trading volumes to migrate further offshore or into fully compliant venues, while legal departments at every exchange rewrite token admission policies overnight.

For traders and builders, the message is unmistakable: the SEC just proved it can reach major offshore platforms, and the window for unregulated altcoin exposure is narrowing fast.

Bitcoin News: X Sues UK Crypto Influencers in Landmark Lawsuit

X Sues Crypto Influencers Over Alleged $277,000 Creator Revenue Fraud

Social media platform X has filed a lawsuit against cryptocurrency influencers Vivek Kumar Sen and Zamyang Sherpa, accusing the pair of fraudulently obtaining more than $277,000 through the company’s creator revenue-sharing program.

Lawsuit Targets Alleged Revenue-Sharing Abuse

The case was filed in the High Court, according to the available information. X alleges that Sen and Sherpa improperly accessed or manipulated the platform’s creator monetization system to receive payments to which they were not entitled.

The creator revenue-sharing program allows eligible users to earn compensation based on engagement with advertising and other content distributed on the platform. X’s claims remain allegations, and the court has not issued a final ruling in the matter.

Crypto Influencers’ Accounts Suspended

The lawsuit follows the suspension of the influencers’ accounts, although the available details do not specify when the suspensions occurred or the precise conduct that led to them.

The dispute highlights the challenges social media platforms face in verifying creator activity and preventing abuse of monetization programs. Such systems can expose platforms to fraudulent claims when engagement, account ownership or payment eligibility is manipulated.

X Shifts Focus Toward Original Content

The legal action comes as X, owned by Elon Musk, continues to emphasize original content and changes to its creator-focused features. The company has increasingly sought to encourage users to publish directly on the platform while addressing practices that it says undermine the integrity of its revenue-sharing programs.

Further details about the allegations, the amount sought by X and the defendants’ response were not available in the information provided.

Delaware Court Lets Crypto Startup Sue in Open Court, Rejects Narrow Arbitration Clause

Wellermen Image Court Gives Crypto Startup a Green Light to Sue
Delaware’s Superior Court just let a crypto startup and its founder keep their lawsuit alive, ruling that a business dispute involving digital assets can be heard in state court rather than being forced into arbitration. The decision matters because it shows judges are willing to treat crypto-related contracts like any other commercial agreement, even when blockchain, tokens, or wallets are involved.

The case started when Diamond Fortress Technologies and its founder Charles Hatcher sued former partners over what they say was a broken deal to develop and commercialize a crypto product. The defendants tried to shut the case down by pointing to an arbitration clause in earlier paperwork. Hatcher and Diamond Fortress argued that the clause didn’t cover the later crypto venture and that forcing arbitration would effectively kill their chance to prove fraud and breach of contract. Superior Court Judge Paul R. Wallace agreed, finding the arbitration language too narrow to sweep in the new claims.

By keeping the case in open court, the ruling hands the plaintiffs leverage they wouldn’t have in private arbitration. The defendants lose their attempt to move the fight behind closed doors, where discovery is limited and outcomes stay confidential. For the crypto industry, the message is simple: contracts tied to tokens or digital platforms will be read the way ordinary contracts are read—no special immunity, no automatic escape hatch.

In plain terms, Delaware courts won’t rubber-stamp arbitration demands just because a project touches blockchain. If the paperwork doesn’t clearly cover the later dispute, judges will let the case proceed in public court, where evidence is aired and damages can be bigger. That raises the stakes for anyone drafting token deals, joint ventures, or licensing agreements in the space.

The decision tilts power toward founders and smaller teams who suspect larger partners of misusing code, tokens, or IP. It also warns exchanges, DeFi protocols, and token issuers that sloppy contract language can land them in prolonged public litigation instead of quick private arbitration, increasing both legal costs and reputational risk.

For traders and investors, the takeaway is that Delaware’s willingness to hear crypto cases in open court could make future disputes more transparent—and potentially more expensive—than many expected.

DC Circuit Forces SEC to Reconsider Grayscale Bitcoin ETF

Wellermen Image GRAYSCALE SLAMS SEC, COURT ORDERS BITCOIN ETF REVIEW
The D.C. Circuit just slapped the SEC for treating Grayscale’s spot Bitcoin ETF worse than futures-based products, forcing the agency to reconsider its 2022 denial and potentially opening the door for the first U.S.-listed Bitcoin exchange-traded fund. The ruling exposes the SEC’s reasoning as inconsistent and arbitrary, and it hands Grayscale a rare win against Gary Gensler’s crypto crackdown.

Grayscale filed its petition after the Commission rejected its proposal to convert the Grayscale Bitcoin Trust into an ETF, arguing that the product would expose retail investors to fraud and manipulation. The SEC claimed the Chicago Mercantile Exchange’s Bitcoin futures market lacked a “significant market” link to spot Bitcoin prices, so surveillance-sharing agreements couldn’t protect against manipulation. Grayscale countered that the Commission had already approved futures ETFs on the same logic, making its refusal arbitrary and capricious.

In a unanimous opinion written by Judge Rao, the three-judge panel agreed. The court held that the SEC failed to explain why it approved spot-Bitcoin-linked futures products yet rejected a spot-Bitcoin ETF that would trade on the same underlying market. Because the agency offered no coherent distinction, the denial violated the Administrative Procedure Act. The case now returns to the SEC for a fresh decision that must treat like products alike.

The decision strips the Commission of its favorite excuse for blocking spot Bitcoin ETFs and signals that regulators can’t keep moving the goalposts without a rational basis. It also puts pressure on the SEC to justify why it treats Bitcoin futures as safe enough for ETFs but Bitcoin itself as too risky, narrowing the agency’s discretion on commodity-based crypto products.

For markets, the ruling tilts power toward exchanges and issuers that want spot exposure without futures contango drag. If the SEC cannot articulate a new, defensible reason to deny, Bitcoin ETFs could list within months, bringing billions in traditional capital, tightening spreads, and reducing reliance on offshore venues. Ether and other large-token issuers will watch closely, because the same consistency argument could apply to them.

The SEC can still say no, but now it must do so with a straight face—or watch its rejections get reversed again.

Seventh Circuit Expands CFTC Power to Target Unregistered Crypto Platforms

Wellermen Image Court Slams Crypto Trader—And the CFTC’s Power Just Expanded
A federal appeals court just handed the CFTC a major win against a crypto trader, ruling that his unregistered business violated federal law and that the agency has the authority to pursue such claims. The decision in CFTC v. Donelson signals that commodity regulators can target more crypto activities—even those that don’t involve traditional futures contracts—raising the stakes for anyone operating in gray zones.

The case started when the CFTC accused James Donelson of running a cryptocurrency trading operation without proper registration and making misleading claims to attract customers. Donelson argued that the CFTC lacked authority over his platform because it didn’t deal in futures or other regulated derivatives. The district court sided with the agency, and Donelson appealed to the Seventh Circuit, hoping to narrow the CFTC’s reach.

Judges on the appeals court upheld the lower court’s ruling, finding that Donelson’s conduct fell squarely within the CFTC’s jurisdiction. The court rejected his argument that crypto trading platforms fall outside the agency’s scope, emphasizing that the Commodity Exchange Act gives the CFTC broad authority to regulate commodity transactions—including those involving digital assets. The decision means Donelson faces penalties and possible injunctions, while the CFTC gains a stronger legal precedent for future enforcement.

In plain terms, the court confirmed that the CFTC can go after unregistered crypto platforms even if they don’t offer classic derivatives. This lowers the bar for regulators and raises compliance costs for traders and platforms that had hoped to operate outside the agency’s reach.

For markets, the ruling strengthens the CFTC’s hand in a space where the SEC has struggled to prove jurisdiction. Traders and exchanges that once gambled on regulatory gaps now face a clearer threat: enforcement without needing to prove a futures contract exists. DeFi protocols and stablecoin issuers may feel indirect pressure as the CFTC signals willingness to stretch its authority. This could push some projects toward offshore structures or force others to seek formal registration.

The takeaway: the days of “ask forgiveness, not permission” are fading fast—plan for registration or plan for fines.

**Bitmine Buys 27,562 ETH as Tom Lee Declares Crypto Bull Market**

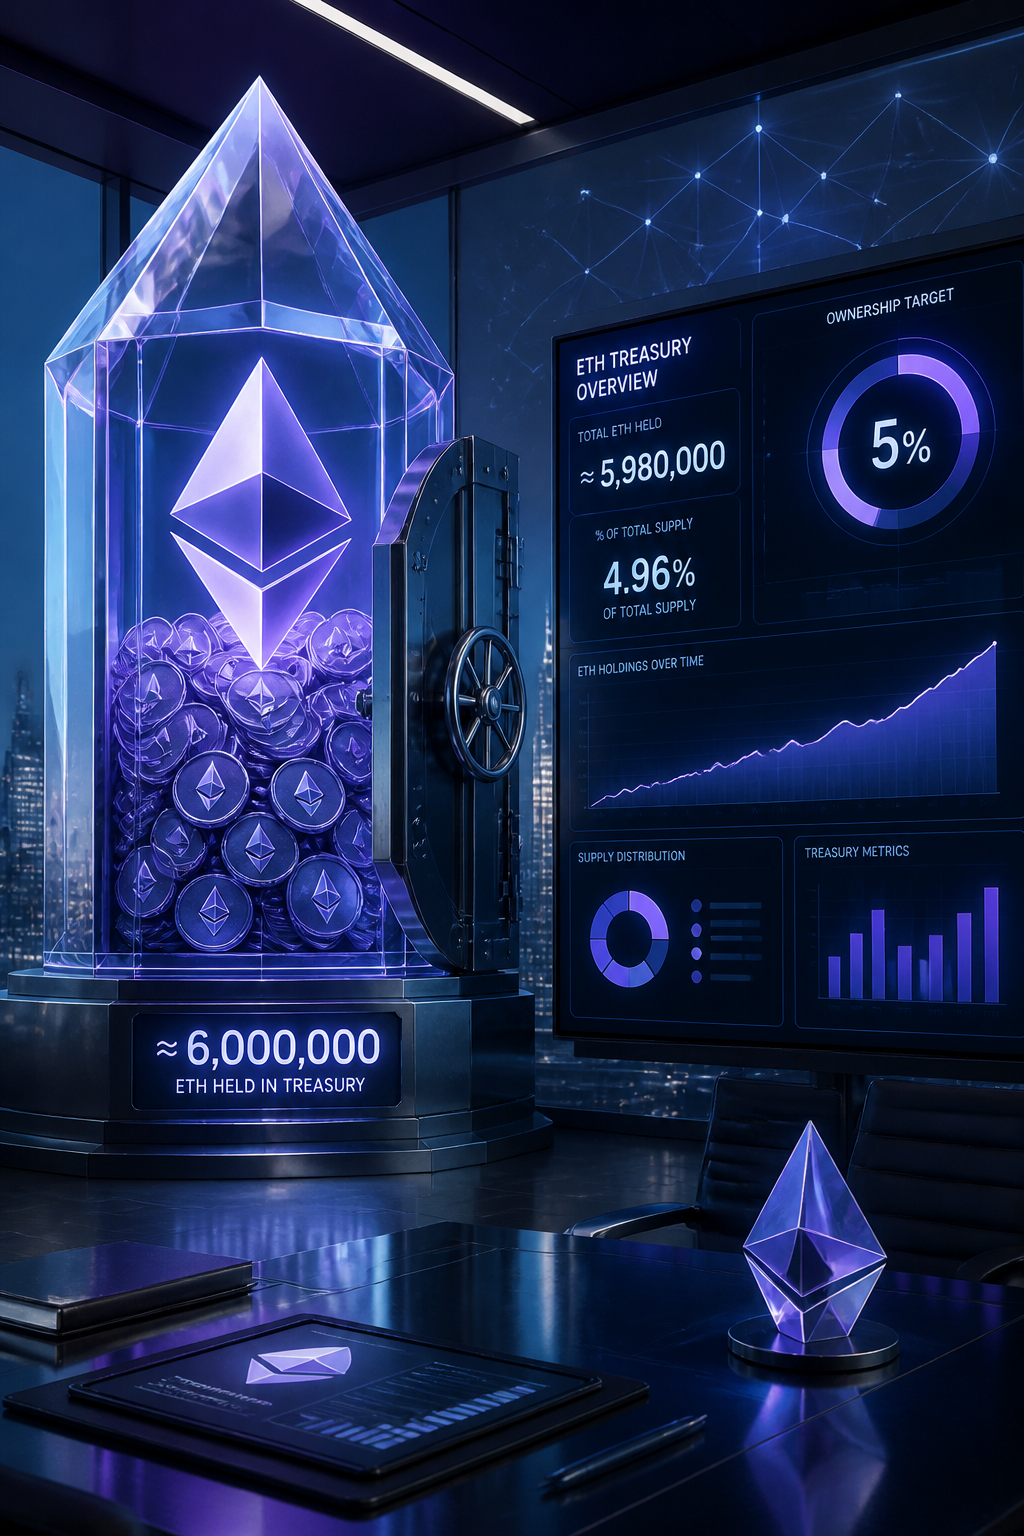
BitMine Accumulates Nearly 6 Million ETH, Approaching 5% Ownership Target

BitMine Immersion Technologies has accumulated nearly 6 million ether, giving the publicly traded company control of approximately 4.9% of the cryptocurrency’s circulating supply. The company’s holdings are valued at about $16.1 billion based on the reported figures.

Company Nears “Alchemy of 5%” Goal

BitMine is now roughly 121,000 ETH short of Chairman Tom Lee’s stated “Alchemy of 5%” target. Reaching that level would give the company exposure to approximately one-twentieth of all ether in circulation.

The latest reported purchase involved 53,501 ETH. The acquisition adds to a buying strategy that has seen BitMine purchase ether every week since June 30, according to records cited in the report.

Ether Accumulation Strategy

BitMine’s approach places ether at the center of its corporate treasury strategy. The company’s growing holdings make it one of the largest publicly disclosed corporate holders of the asset and could increase its sensitivity to movements in ether’s market price.

Ether has recently traded near the $2,500 level, with market participants monitoring whether the cryptocurrency can establish sustained support above that threshold. BitMine’s continued purchases come as the broader market evaluates demand for ether from corporate treasuries and other institutional investors.

Third Circuit Rules Against Coinbase, Won’t Force SEC to Write Crypto Rules

Wellermen Image Court Slams Coinbase’s SEC Challenge in One Sentence
The Third Circuit Court of Appeals today refused to force the SEC to answer Coinbase’s petition for crypto-specific trading rules, effectively telling the exchange that courts cannot order regulators to write new policy. In one terse sentence the panel dismissed the case for lack of jurisdiction, signaling that Coinbase must wait for the SEC to act—or sue later when actual enforcement lands.

The dispute began last year when Coinbase asked the SEC to propose clear-cut regulations for digital-asset platforms instead of policing the industry through enforcement actions. The agency sat on the request for months; Coinbase then petitioned the Third Circuit to compel a response under the Securities Exchange Act’s “failure-to-act” provision. The three-judge panel heard argument in September and, in a brief order issued today, ruled that the statute does not give courts power to dictate the SEC’s rulemaking agenda.

Coinbase loses the procedural round and must now decide whether to renew its rulemaking petition, pivot to a direct constitutional challenge, or prepare for individual enforcement proceedings. The SEC wins breathing room: it can continue its case-by-case approach without judicial deadlines. Industry players who hoped for a fast-track to formal rules lose momentum and clarity.

In plain terms, the ruling means the SEC does not have to negotiate policy in court; it can keep crypto firms in a gray zone where enforcement risk, not regulation, sets the boundaries. Without a statutory duty to respond, the agency’s silence is not reviewable—yet.

For crypto markets the decision tilts the field toward regulators and away from exchanges. Expect the SEC to keep its enforcement-first posture, raising compliance costs for listed tokens and pressuring DeFi protocols that rely on secondary-market liquidity. Traders should price in prolonged uncertainty: stablecoin issuers and exchange tokens may see sharper swings on any hint of new enforcement waves, while platforms weigh delistings to shrink their legal perimeter.

The message is simple—until Congress or the Supreme Court changes the rules, the SEC writes its own timeline, and the market trades the risk.

Google, Apple Seek Crypto Talent for Stablecoin and Tokenization Push

Tech Giants’ Job Listings Point to Potential Digital Payments Research

Recent job listings from major technology companies may indicate separate efforts to hire specialists in stablecoins and tokenized deposits, potentially supporting future digital payments or blockchain-related projects.

Focus on Stablecoins and Tokenized Deposits

Stablecoins are digital assets designed to maintain a relatively stable value, often by referencing fiat currencies or other assets. Tokenized deposits represent traditional bank deposits on blockchain networks while remaining linked to the issuing financial institution.

The recruitment activity does not confirm that any specific company is preparing to launch a stablecoin or tokenized deposit product. However, hiring employees with expertise in these areas could signal that the companies are evaluating potential applications for digital assets and blockchain-based payment infrastructure.

Kasplex KRC-20 Signature Bypass Drains Two Token Pools

Kasplex KRC-20 Indexer Exploit Drains Two Token Pools

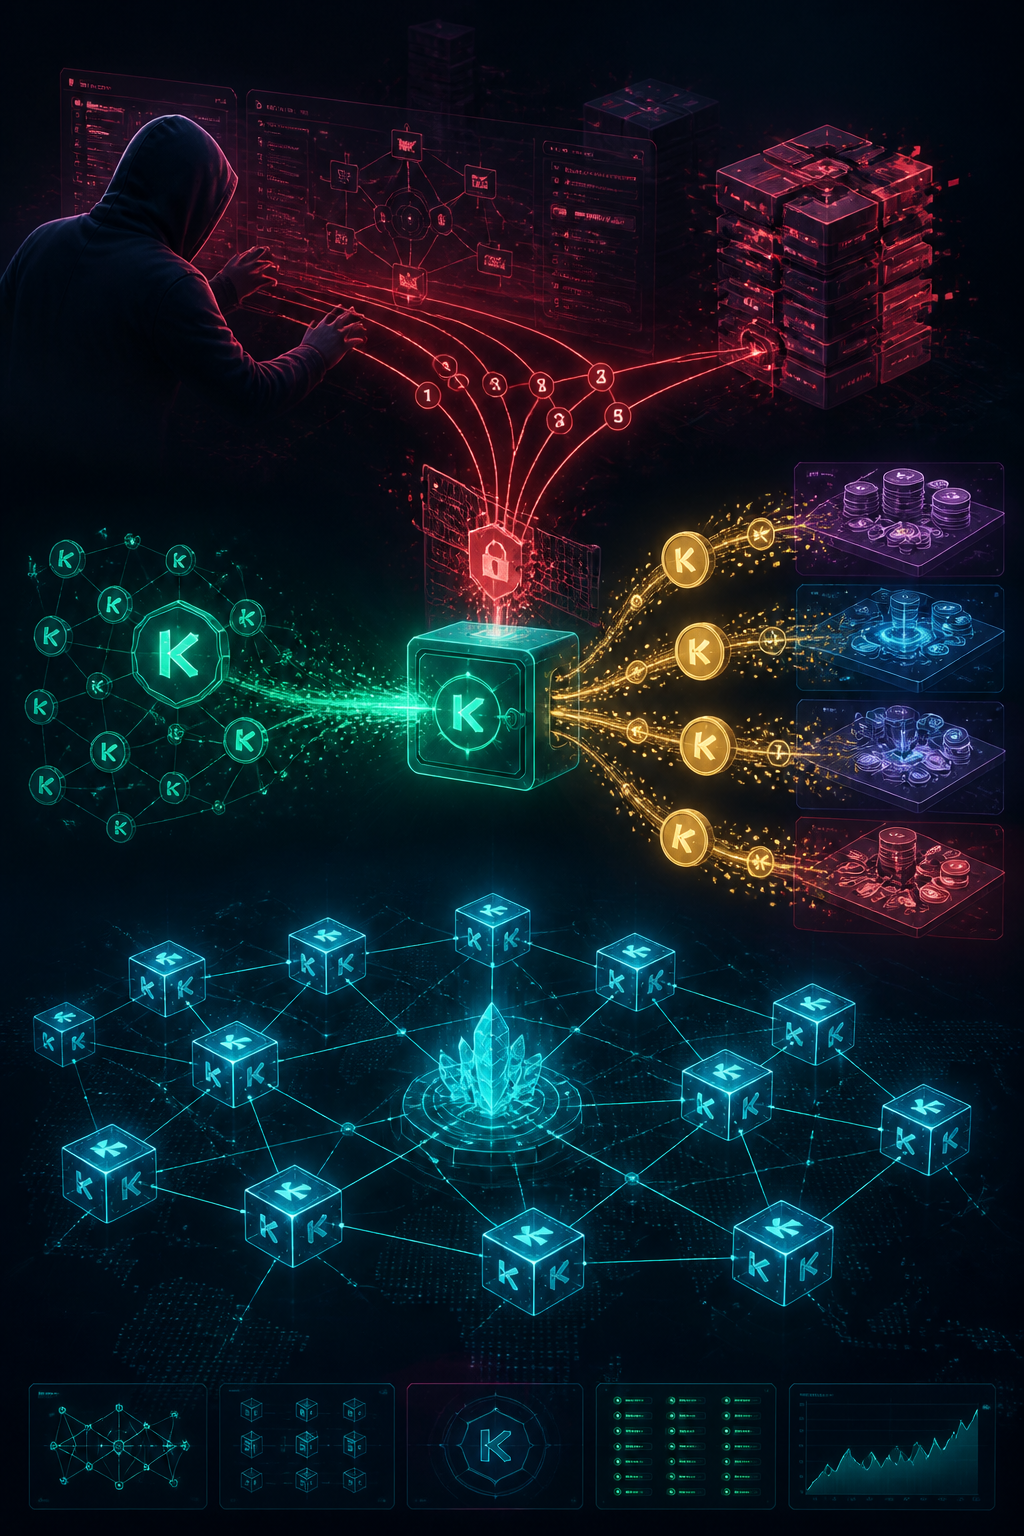
An attacker withdrew 186.4 million ZEAL and 54.4 billion NACHO from a Kaspa KRC-20 bridge wallet without possessing its private key, according to a security alert. The tokens were subsequently routed through layer-2 networks and sold into liquidity pools.

Off-Chain Indexer Exploited

The incident did not involve a compromise of the Kaspa blockchain itself. Instead, the attacker reportedly used five valid transactions to deceive an off-chain indexer responsible for processing and verifying activity related to the Kasplex KRC-20 bridge.

By bypassing the indexer’s signature checks, the attacker was able to make unauthorized withdrawals from the bridge wallet. The flaw appears to have affected the indexer’s interpretation of valid on-chain transactions rather than Kaspa’s underlying consensus or cryptographic security.

Tokens Moved Through Layer-2 Networks

After withdrawing the assets, the attacker recycled the ZEAL and NACHO tokens through layer-2 networks before selling them into liquidity pools. This activity placed pressure on the affected markets and reduced the assets held by the associated pools.

KRC-20 is a token standard used on the Kaspa network. Bridges and indexers supporting such assets typically track transactions off-chain and use that information to coordinate deposits, withdrawals and token movements across networks.

Security Implications

The incident highlights the risks associated with off-chain infrastructure, even when the underlying blockchain remains operational and uncompromised. A vulnerability in an indexer or bridge verification system can enable unauthorized asset transfers if transaction validation is not handled correctly.

The affected wallets, pools and total financial impact were not specified in the available information.

×