ECB to Invest Directly in Tokenized Securities Through Pontes

ECB Prepares to Invest in Tokenized Euro-Denominated Securities

The European Central Bank has begun preparations to invest a small portion of its own-funds portfolio in tokenized euro-denominated securities, marking a potential shift from developing tokenized-settlement infrastructure to using it directly.

Initial Investment Focus

The planned investments are separate from the ECB’s monetary-policy operations. They would be made through the central bank’s own-funds portfolio, a non-monetary-policy pool.

The initial eligible assets are expected to include securities issued by:

  • Euro-area central governments;
  • Regional governments and agencies; and
  • European supranational institutions.

Tokenized securities are digital representations of financial assets recorded and transferred using distributed-ledger or similar technology.

Settlement Planned Through Pontes

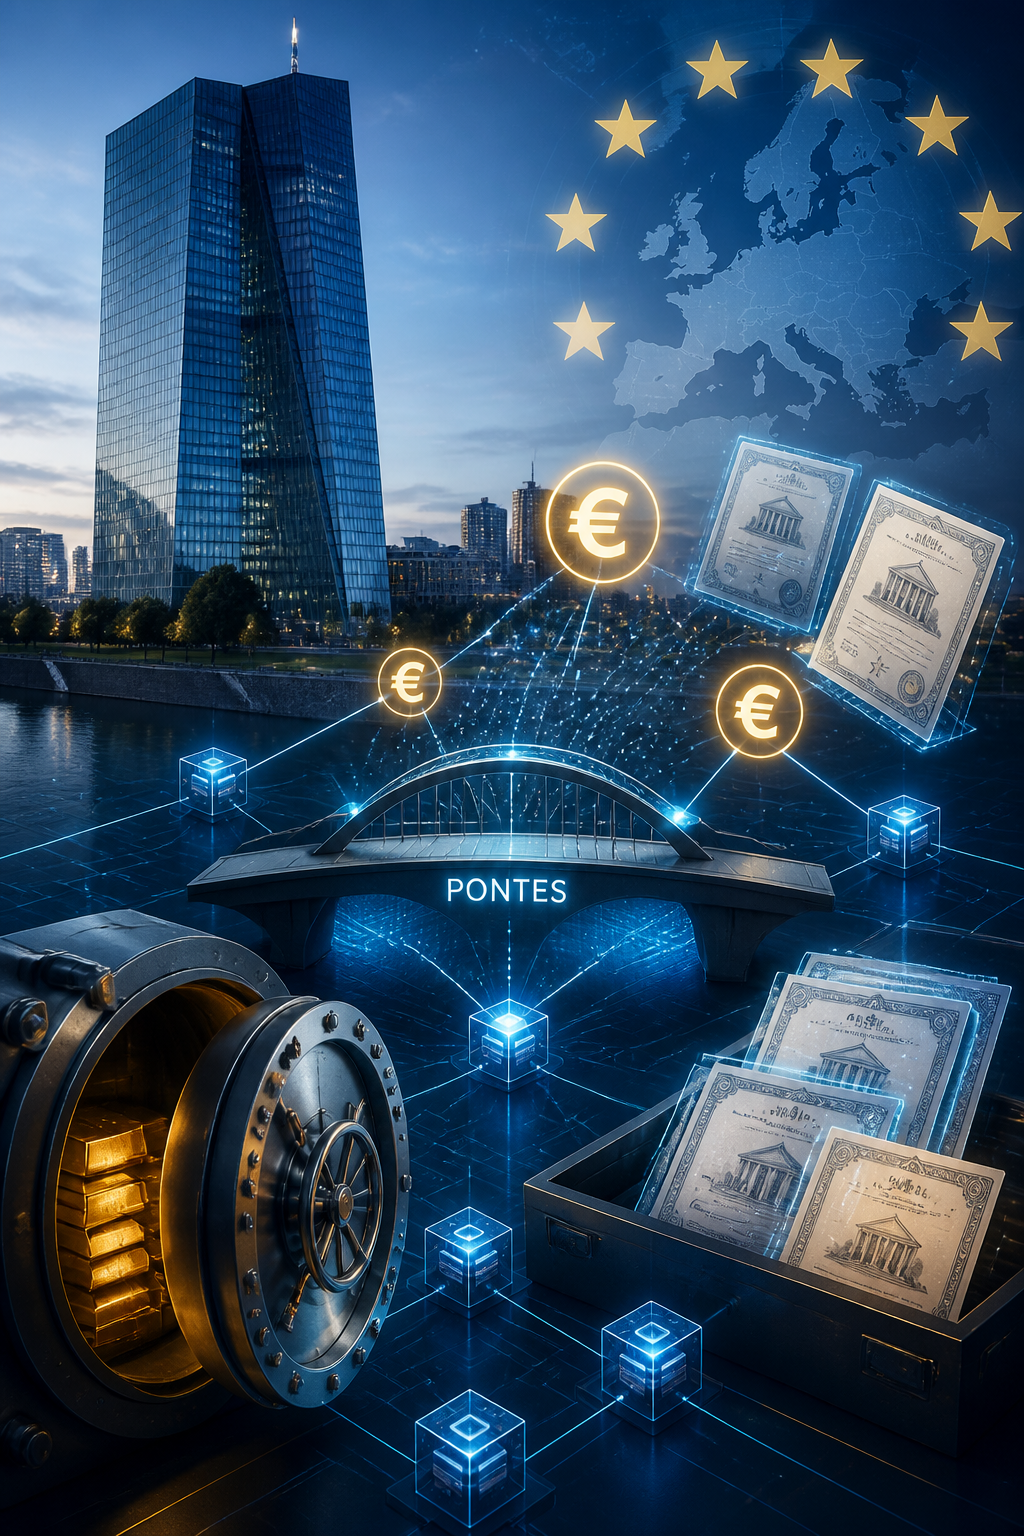
The ECB intends for the purchases to settle in central-bank money through Pontes, the Eurosystem’s infrastructure for settling tokenized financial assets.

The plan would make the ECB not only a provider of tokenized-settlement infrastructure for market participants but also a potential user of that infrastructure for its own portfolio transactions.

No Purchases Have Been Completed

The ECB’s announcement concerns preparatory work. It has not stated that any tokenized securities have already been purchased for the own-funds portfolio.

Operational timing and execution details will be determined after the preparation phase and a subsequent review by the ECB’s Executive Board.

If implemented, the initiative could move tokenization beyond pilot programs and into the routine management of an institutional investment portfolio. For now, however, the development represents a planned use case for Pontes rather than completed trades.
Kalshi Wins Again as Court Slams CFTC Overreach on Election Contracts

Wellermen Image KALSHI WINS AGAIN AS COURT SLAMS CFTC’S OVERREACH
A federal appeals court has refused to block KalshiEX from offering election contracts, effectively slapping the CFTC for trying to stretch its power beyond what Congress granted. The decision keeps the trading venue open for now and signals that federal regulators cannot simply declare something off-limits without clear statutory authority.

The fight started when Kalshi sought CFTC approval to list contracts tied to U.S. election outcomes. The agency said no, arguing that letting people bet on elections would be “contrary to the public interest.” Kalshi sued, claiming the CFTC lacked the legal power to block contracts based solely on its own view of morality or politics. A district judge agreed and ordered the agency to let the contracts trade; the CFTC immediately asked the D.C. Circuit to freeze that order while it appealed. On October 2, the appeals court denied the stay, letting the lower-court ruling stand for now.

Judges on the three-member panel focused on whether the CFTC had shown a likelihood of success on the merits and whether halting trading would cause irreparable harm. They found the agency’s public-interest argument too vague to override the Commodities Exchange Act’s presumption that exchanges can list contracts unless they violate specific statutory bans. The court also noted that Kalshi had already invested heavily in compliance systems, so the balance of equities tilted toward letting trading begin. In short, the CFTC lost this round and must now either prove its case on a full appeal or watch the contracts go live.

The ruling narrows the CFTC’s discretion to veto products on broad policy grounds. The agency still regulates fraud and manipulation, but it cannot simply brand an instrument “bad for society” and shut it down without pointing to concrete statutory language.

For crypto traders and DeFi builders, the decision is a green light: prediction markets, event contracts, and other novel instruments now face a lower regulatory hurdle. Expect more election-related tokens, on-chain betting protocols, and exchange listings that sidestep traditional gatekeepers. Stablecoin issuers and decentralized platforms that offer similar exposure should still watch for fraud rules, but the threat of a blanket CFTC veto just shrank.

Regulators will keep testing their reach, yet today’s order shows that judges can—and will—push back when agencies stretch beyond the text of the law.

Court Denies Envy Blockchain’s Last-Ditch Bid to Skip Trial

Wellermen Image COURT KILLS BLOCKCHAIN COMPANY’S LAST-DITCH BID TO SKIP TRIAL
Envy Blockchain, NV Landco 1, and CEO Stephen DeCani just lost their emergency bid to halt a Texas district-court case mid-stream. The El Paso Court of Appeals refused to issue a writ of mandamus that would have frozen discovery, sanctions motions, and a looming trial date, effectively telling the company that litigation pain cannot be sidestepped by appellate shortcut. The ruling lands at a moment when crypto firms already feel the squeeze of both civil suits and regulatory scrutiny.

The fight began when a Texas investor accused the three parties of misusing funds raised for a planned Bitcoin-mining facility. After the district judge allowed broad discovery and sanctioned the defendants for discovery abuse, Envy and its co-defendants raced to the appellate court, arguing the lower court had no jurisdiction because the mining project never left the idea stage and the claims sounded in securities fraud—an area they claimed was preempted by federal law. The panel cut through the argument in a single paragraph: mandamus is an extraordinary remedy, and Envy had failed to show the district court was “clearly and indisputably” out of bounds.

In plain terms, Texas courts will keep jurisdiction, evidence will be exchanged, and the case heads toward either settlement or a jury verdict. That means more documents, more depositions, and more potential headlines about missing investor money. For crypto projects still structured as Texas LLCs or still courting Lone-Star capital, the decision is a reminder that state-court dockets move faster than federal crypto rule-making.

From a market perspective, the ruling quietly tilts power toward plaintiffs and state attorneys general while the SEC and CFTC continue to spar over digital-asset turf. Every new document unsealed in discovery could feed enforcement theories on unregistered securities or commodities, raising due-diligence costs for exchanges listing tokens tied to mining ventures. Traders pricing governance tokens or mining-related equities will now bake in a higher Texas-litigation premium.

Bottom line: if your tokenomics live in Texas courts, plan for discovery, not just disclosure.

Privilege Wins as Seventh Circuit Blocks CFTC’s Fast-Track for Internal Memos in Wheat-Futures Case

Wellermen Image COURT TELLS CFTC: HANDS OFF INTERNAL DOCUMENTS
The Seventh Circuit just blocked the CFTC’s attempt to force Kraft and Mondelēz to hand over privileged materials in a wheat-futures manipulation probe. By denying the agency’s petition for a writ of mandamus, the court told regulators they cannot shortcut normal discovery rules—even when the stakes involve futures markets. That single procedural ruling could slow CFTC enforcement and give exchanges and traders breathing room.

The dispute began when the agency accused the two food giants of rigging the wheat market. Rather than wait for ordinary document requests, the CFTC asked the district court to compel production of internal memos that the companies claimed were protected by attorney-client privilege. The district judge refused, and the agency ran straight to the appeals court for an extraordinary writ—an order that would have forced disclosure immediately. Three Seventh Circuit judges heard the petition and, in a short opinion, said the CFTC had not shown the “clear and indisputable” right needed for mandamus.

What the judges actually ruled is simple: privilege fights belong in the trial court first, and regulators get no special fast-pass. Kraft and Mondelēz keep their documents under seal for now. The CFTC can still fight the privilege claims line-by-line, but it cannot leapfrog the process. The companies win a tactical victory; the agency loses momentum and precedent that would have made future fishing expeditions easier.

In plain English, the court reminded the CFTC that administrative muscle does not erase centuries-old protections for lawyer-client communications. The ruling narrows the agency’s toolkit at the very moment it is expanding oversight into crypto-linked commodity products. If the same logic applies to digital-asset subpoenas, exchanges and DeFi protocols gain a new shield against broad document grabs.

For crypto markets, the decision tilts the balance toward due process over speed. Traders and platforms now have slightly stronger grounds to push back when the CFTC—or the SEC citing similar theories—demands privileged strategy memos. That does not stop enforcement, but it raises the cost and calendar time of every case. Decentralized projects that never kept traditional legal memos may dodge the issue altogether, while listed exchanges face higher compliance spend.

The takeaway: regulators just learned they cannot treat privilege as an after-thought; expect slower, more expensive enforcement—and a short-term lift in risk appetite among exchanges and traders who were bracing for wide-ranging document sweeps.

BitMine’s ETH Treasury Nears 6 Million Tokens, Reaching $17.1B

BitMine Reports Nearly 6 Million ETH in Treasury Holdings

BitMine Immersion Technologies reported 5,983,940 ETH in its treasury, putting the company just below the 6 million-token mark. The company said its combined holdings, including cryptocurrency, cash, securities and strategic investments, were valued at $17.1 billion.

Ethereum Holdings Approach 6 Million Tokens

In a filing dated September 21, BitMine disclosed that it held 5,983,940 ETH. The company said the position represented approximately 4.9% of the circulating Ethereum supply figure cited in the filing.

The disclosure does not indicate that BitMine has crossed the 6 million ETH threshold. It also does not provide details about future purchases or specify when the company might reach that level.

Broader Treasury Portfolio

Beyond its Ethereum holdings, BitMine reported 212 BTC and $714 million in cash and marketable securities. The company also disclosed a $180 million stake in Beast Industries and a $105 million stake in Eightco.

Combined, the disclosed assets were valued at $17.1 billion. While ETH represents the dominant component of BitMine’s treasury, the filing shows that the company maintains a broader portfolio of digital assets, liquid investments and strategic equity positions.

Growing Role of Ethereum Treasury Companies

Corporate cryptocurrency treasury strategies have historically focused primarily on Bitcoin. BitMine’s holdings highlight the expansion of the model into Ethereum, giving the company exposure to ETH’s market price as well as developments involving staking, network activity and institutional demand for Ethereum-based assets.

The scale of BitMine’s position means changes to its treasury could attract increased attention from the broader Ethereum market. For now, the filing confirms that BitMine holds 5,983,940 ETH and values its total disclosed treasury assets at $17.1 billion.

Old Court Order, Fresh Crypto Scrutiny: SEC Keeps Bilzerian Injunction Alive

Wellermen Image Court Reopens 1989 Bilzerian Case, Warns Crypto Mimics
SEC wins round in 34-year-old Bilzerian saga, signals fresh appetite for old grudges and new targets. The ruling keeps decades-old injunctions alive and warns anyone using complex structures to dodge disclosure rules that time is no shield.

The fight started in 1989 when the SEC accused Bilzerian of secretly amassing stock in several public companies through undisclosed offshore entities and false filings. After a 1993 civil judgment and 2001 injunction barring him from “commencing or causing the commencement of any legal proceeding” without first giving the SEC notice, Bilzerian’s estate and related parties asked the court to end the restrictions, arguing the passage of time and changed circumstances made them obsolete. Judge Royce Lamberth refused. The court held that the original injunction remains necessary because the defendants never demonstrated full compliance or an end to the risk of future violations. The SEC keeps its enforcement tool; defendants stay tethered to prior restraints.

In plain terms, the judge said an old order is still an order. Once a court bars someone from using legal maneuvers to hide ownership or evade disclosure, that bar does not expire simply because years pass. The ruling keeps the 2001 language intact, meaning any future attempt to litigate without SEC notice can trigger contempt findings and fresh penalties.

The decision widens the SEC’s practical reach. While the case itself is not about crypto, the precedent matters because many token projects today rely on layered entities, offshore vehicles, and ambiguous disclosures—the same toolkit Bilzerian used. Exchanges and DeFi protocols that structure tokens to skirt securities classification face the reminder that regulators can dust off decades-old injunctions if similar patterns appear. Stablecoin issuers and liquidity providers who obscure beneficial ownership should expect heightened scrutiny; traders betting on regulatory gray zones just saw one shrink.

Old grudges do not die; they just wait for the next cycle.

Appeals Court Narrows SEC’s Crypto Securities Power, Shifts Control to CFTC

Wellermen Image **SEC Suffers Major Blow as Court Narrows Crypto Oversight Powers**
A federal appeals court just handed the crypto industry a significant legal victory, sharply limiting the SEC’s ability to treat most digital assets as securities. The ruling could reshape how tokens are classified, how exchanges operate, and how the SEC pursues enforcement cases going forward.

The case began when the SEC sued a major crypto exchange for allegedly selling unregistered securities. The agency argued that nearly all tokens on the platform met the Howey test because buyers expected profits from the issuer’s efforts. The exchange fought back, claiming the tokens were commodities or utility assets with no profit-sharing contract. After months of litigation, the appeals court agreed the SEC had overreached, ruling that most tokens do not automatically qualify as securities simply because they are listed on a trading platform.

The judges found that the SEC failed to prove buyers were investing money in a common enterprise with the expectation of profits derived solely from the efforts of others. Instead, the court emphasized that many tokens function more like commodities or consumer goods, especially when their value is driven by market forces rather than any single promoter. The decision also criticized the SEC for failing to provide clear guidance, calling its enforcement approach “arbitrary and inconsistent.”

This ruling significantly weakens the SEC’s position in ongoing and future crypto cases. It signals that courts may require more specific evidence of investment contracts rather than blanket classifications. The decision could force the agency to rethink its enforcement strategy and may embolden exchanges and DeFi projects to resist broad regulatory demands.

The ruling shifts power toward the CFTC for commodity-like tokens and reduces legal uncertainty for exchanges that list non-security assets. It also puts pressure on lawmakers to create clearer rules, as courts are now less willing to let the SEC define the entire market through enforcement alone. Stablecoin issuers and DeFi protocols may face lower legal risk, while the SEC will likely face higher hurdles in proving violations.

For traders and platforms, the message is clear: regulatory risk has not vanished, but the balance has tilted. This decision opens the door for innovation while reminding everyone that the fight over who controls crypto’s future is far from over.

Offshore Crypto Funds Escape CFTC Jurisdiction, Court Rules

Wellermen Image CFTC Stung as Appeals Court Snaps Leash on Its Power
Judges just told the CFTC it can’t stretch its reach across oceans to punish traders who never set foot in the U.S., a ruling that immediately weakens the agency’s long-running claim to global authority over crypto and derivatives markets. The Seventh Circuit’s decision hands the Conway Family Trust a win and sends a clear message that geography still matters in regulation.

The trust had parked money with a Cayman Islands fund that later blew up. When the CFTC tried to fine the trust for failing to register as a commodity pool operator, the trustees fought back, arguing the trades happened offshore and the CFTC had no jurisdiction. The agency countered that the fund used U.S. clearing firms, giving it a hook. The panel rejected that theory, holding that merely routing orders through American infrastructure does not turn a foreign pool into a domestic one.

The court zeroed in on the statute’s language: registration rules apply only to pools “operated” inside the United States. Because the trust’s decisions were made in the Caymans, and the CFTC offered no evidence that the trust itself controlled U.S.-based trading, the agency lacked authority. The ruling slams the door on the CFTC’s attempt to bootstrap jurisdiction from downstream clearing activity.

In plain terms, the decision blocks the CFTC from hauling offshore crypto funds and DeFi protocols into U.S. court just because they clear trades on American exchanges or touch U.S. liquidity. Offshore entities now have a stronger shield against registration demands, and U.S. platforms that serve them face less pressure to police foreign counterparties.

Traders and exchanges gain breathing room to structure offshore vehicles without automatic U.S. oversight, but stablecoins and tokens that clear significant volume through domestic rails remain exposed if any U.S. entity exercises actual control. Expect more Cayman and Singapore vehicles, tighter structuring around order routing, and a cautious uptick in offshore DeFi activity until regulators find a new hook.

The message is blunt: location still shapes liability, and the CFTC’s extraterritorial reach just got shorter.

Strategy Buys 950 More Bitcoin, Pushing Holdings to 846,000 BTC

Strategy Adds 950 Bitcoin for $75.7 Million, Bringing Holdings to 846,000 BTC

Strategy purchased 950 Bitcoin between September 14 and September 20 for approximately $75.7 million, according to a filing submitted to the U.S. Securities and Exchange Commission on September 21. The company paid an average of $79,670 per Bitcoin in the latest acquisition.

Bitcoin Holdings Reach 846,000 BTC

Following the purchase, Strategy reported total Bitcoin holdings of 846,000 BTC. The company said it acquired the holdings for an aggregate cost of approximately $63.80 billion, including related fees and expenses, resulting in an average acquisition price of $75,416 per Bitcoin.

The September 21 filing covers purchases made during the preceding week and does not indicate that all 950 BTC were acquired on the filing date. Strategy has regularly disclosed multiple purchases in periodic treasury updates.

Bitcoin Remains Central to Strategy’s Treasury Policy

The latest acquisition extends Strategy’s Bitcoin-focused corporate treasury strategy. With 846,000 BTC on its balance sheet, Bitcoin represents a substantial component of the company’s assets and remains closely tied to how investors assess its financial position and capital-raising activity.

Because the latest purchase price was above Strategy’s existing average cost basis, the acquisition increased the company’s blended average purchase price.

STRC Share Repurchase

The same filing also reported that Strategy repurchased 1,771,238 shares of its STRC preferred stock for approximately $174 million.

Fifth Circuit Showdown Could Narrow SEC Power Over Crypto Exchanges

Wellermen Image SEC Ruling on Crypto Exchanges Faces Fifth Circuit Showdown
The U.S. Court of Appeals for the Fifth Circuit will hear arguments in a pivotal appeal that could redefine the SEC’s authority to regulate crypto exchanges. The case, filed as No. 23-11237, has drawn intense attention from traders, DeFi builders, and exchange operators who view the outcome as a potential turning point in how digital assets are classified and policed.

The dispute traces back to SEC enforcement actions against several major exchanges, alleging unregistered offerings of digital tokens. Exchanges pushed back, arguing the SEC lacked jurisdiction because the tokens in question do not qualify as securities. Lower courts split on the issue, prompting the Fifth Circuit to consolidate the appeals and decide whether the SEC can treat crypto trading platforms as traditional securities exchanges under existing law.

Judges will examine whether digital assets sold on secondary markets carry the same legal characteristics as investment contracts. The outcome hinges on the Howey test, a decades-old standard used to determine if an asset qualifies as a security. If the court narrows the test’s application, the SEC’s ability to pursue enforcement against exchanges could be curtailed, shifting power toward the CFTC and state regulators.

The legal impact is straightforward: a ruling against the SEC would limit its reach over crypto platforms, forcing the agency to rely on narrower statutory authority. A win would embolden further enforcement, possibly triggering registration mandates that exchanges have resisted for years. Either way, the decision sets precedent for how courts interpret token sales in decentralized environments.

For markets, the stakes are immediate. A pro-SEC ruling could accelerate delistings, increase compliance costs, and chill liquidity in tokens viewed as securities. A narrower ruling might embolden exchanges to relist tokens previously removed under regulatory pressure, boosting volumes but inviting new litigation. Stablecoins face indirect risk if courts begin treating reserves or yields as investment contracts.

Traders should brace for volatility as the Fifth Circuit’s decision lands—this is not just a legal footnote, but a potential catalyst for the next regulatory cycle.

NY Appeals Court Lets Off-Exchange Crypto Fraud Claims Stand

Wellermen Image Regal Ruling Sends Shockwave Through Crypto Exchanges
A New York appeals court just handed a major victory to a commodity trading firm by reversing a lower court’s dismissal of its fraud claims against a former trader who allegedly hid massive losses through off-exchange crypto deals. The decision signals that courts are willing to treat certain digital assets as commodities subject to fraud liability, even when traded outside traditional exchanges.

The lawsuit began when Regal Commodities accused trader Michael Tauber of executing unauthorized cryptocurrency trades on decentralized platforms, then masking millions in losses by misrepresenting account balances and executing fictitious “offset” trades. The trial court had thrown out the claims, reasoning that the crypto transactions fell outside the scope of traditional commodity fraud statutes. But the Appellate Division, Second Department, reversed that ruling on March 27, 2024, holding that Regal’s allegations—particularly the use of deceptive statements to conceal trading losses—were sufficient to state a claim under New York common law fraud and breach of fiduciary duty, regardless of where the trades occurred.

The judges found that the location of the trades on decentralized platforms did not immunize Tauber from liability if he used misrepresentations to cover his tracks. They emphasized that the core of Regal’s case was not the trading venue itself, but the allegedly false statements Tauber made to his employer about the status of the trades. This shifts the legal question from “where were the trades executed?” to “were material facts misrepresented?”

In plain terms, the court said fraud is fraud—even if it happens on a blockchain. The ruling removes a potential safe harbor for traders who might otherwise claim that off-exchange crypto activity is too novel or unregulated to be subject to traditional legal standards. It also opens the door for more employers and trading firms to pursue claims against individuals who engage in hidden or unauthorized crypto trading.

This decision could embolden the SEC and CFTC to argue for broader enforcement jurisdiction over decentralized platforms, especially where fraud or misrepresentation is involved. It also increases the legal risk for crypto-native exchanges and DeFi protocols that might be used to conceal trading losses or evade compliance obligations. Traders and firms will likely respond by tightening internal controls and demanding clearer documentation of off-exchange crypto activity.

Exchanges and DeFi protocols should expect more aggressive scrutiny—and possibly more lawsuits—now that courts have made clear that hiding behind decentralization won’t shield fraudulent conduct.

CFTC Wins Rare Mandamus, Signals Tougher Crackdown on Spoofing and Crypto

Wellermen Image CFTC Wins Rare Mandamus Order, Signals New Aggression in Commodity Enforcement
Federal appeals court orders Chicago judge to stop blocking CFTC from raiding Kraft’s old trading files, reopening a six-year-old spoofing case. The ruling hands regulators a procedural weapon they rarely win and signals the agency is ready to push harder against suspected manipulation in futures markets that now overlap heavily with crypto.

The case began in 2015 when the CFTC accused Kraft and its sister firm Mondelēz of spoofing wheat futures on the CME, allegedly placing fake orders to move prices before canceling them. A district judge later ruled the agency’s evidence request too broad and barred it from reviewing thousands of internal documents. The CFTC asked the Seventh Circuit for an extraordinary writ of mandamus—an order telling the lower court to get out of the way. Three judges agreed, holding that the district court had “clearly and indisputably” overstepped its authority by rewriting discovery rules in the middle of an enforcement action.

The appellate panel said the judge’s order violated the separation of powers and undermined the CFTC’s statutory right to gather evidence. Kraft and Mondelēz can still fight the substance of the spoofing charges, but they must hand over the documents first. The decision restores the agency’s leverage and removes a procedural shield that targets have tried to use in other manipulation probes.

In plain terms, the court told a federal judge that once the CFTC opens an investigation, it gets wide latitude to collect records; trial courts cannot unilaterally narrow that scope. The ruling does not decide whether Kraft spoofed markets, but it keeps the agency’s evidence-gathering engine running at full speed.

For crypto markets, the message is simple: the same agency watching CME wheat is watching CME bitcoin futures, perpetual swaps, and large stablecoin flows. If the CFTC can force disclosure of internal communications in a legacy commodity case, it can do the same when it suspects wash trading or artificial price moves in tokenized assets. Exchanges and DeFi protocols that custody customer orders or maintain detailed logs now face higher odds that those records will end up in a subpoena.

The decision also strengthens the CFTC’s hand against arguments that DeFi protocols are too decentralized to regulate; the agency can still demand data from any entity that touches U.S. markets or U.S. persons. Expect more document fights, more protective-order litigation, and higher compliance costs for trading desks and protocol teams alike.

Traders and exchanges that treat CFTC document requests as routine discovery rather than last-ditch resistance just gained a costly lesson in how federal courts view that stance.

Crypto Class Actions Remain Split as MDL Panel Denies Consolidation

Wellermen Image Judge Vance’s Panel Rejects Crypto Class Action Consolidation
A three-judge federal panel just denied a bid to merge three separate lawsuits against crypto platforms into one Illinois mega-case. The decision leaves each suit to run on its own track, raising the stakes for every exchange and DeFi protocol named in the filings.

Plaintiff Anthony Motto asked the Judicial Panel on Multidistrict Litigation to bundle his Northern District of Illinois suit with two others in California and Pennsylvania, arguing that common questions about unregistered securities and misleading token marketing justified a single courtroom. The defendants—unnamed in the order but widely understood to include major exchanges and token issuers—fought the move, claiming divergent facts and legal theories made consolidation inefficient. Judges Sarah Vance, acting as Chair, and her colleagues agreed, ruling that the differences in products, disclosures, and investor bases outweighed any efficiencies.

Without consolidation, each district keeps its own discovery schedule, motion practice, and settlement pressure. Plaintiffs now face three separate judges, three juries, and three possible verdicts instead of one coordinated front. For the defense bar, the ruling keeps litigation costs fragmented but also prevents a single adverse finding from rippling across the entire industry. Regulators will watch closely: an early plaintiffs’ win in any of the three districts could embolden the SEC or CFTC to treat similar tokens as securities nationwide, while a defense victory might slow enforcement momentum.

The Panel’s refusal to centralize keeps crypto litigation splintered, meaning enforcement risk stays local and unpredictable rather than uniform and sweeping.

**Bitcoin News: Fairshake PAC Targets Sherrod Brown With $30M War Chest**

Fairshake Reportedly Plans $30 Million Campaign Targeting Sherrod Brown

Fairshake, the cryptocurrency industry’s largest political action committee, is reportedly preparing to spend $30 million to oppose former Ohio Sen. Sherrod Brown’s efforts to return to the U.S. Senate. The reported campaign comes after Senate Democrats blocked the CLARITY Act, a broader cryptocurrency market-structure bill.

Crypto PAC Targets Brown

The planned spending would make Brown a major target for Fairshake and its affiliated political groups. The committee has become one of the most prominent forces in U.S. cryptocurrency politics, directing significant resources toward congressional races and candidates viewed as supportive of digital-asset legislation.

Details about the proposed advertising campaign, including its timing and specific messages, were not provided in the available report. The spending is expected to focus on influencing voter perceptions of Brown and his record on cryptocurrency policy.

Senate Dispute Over the CLARITY Act

The reported effort follows a setback for the cryptocurrency industry in the Senate, where Democrats blocked the CLARITY Act. The legislation was intended to establish a regulatory framework for digital-asset markets and clarify the roles of federal financial regulators.

The bill’s failure has intensified tensions between the crypto industry and lawmakers who oppose or have not supported the industry’s legislative priorities. Fairshake’s reported investment against Brown is being viewed as a political response to that conflict.

Fairshake’s Role in Crypto Politics

Fairshake has raised and spent substantial sums to support candidates who favor clearer cryptocurrency regulations and to oppose lawmakers considered unfavorable to the industry. Its activity reflects the growing role of digital-asset companies and investors in U.S. elections.

Political spending by cryptocurrency-focused groups is expected to remain a significant factor as lawmakers debate market-structure rules, consumer protections and oversight of digital assets.

Fifth Circuit Halts SEC’s Surprise Token Securities Push, Demands Clear Rules

Wellermen Image Court Slams SEC, Hands Crypto Major Legal Win

The Fifth Circuit just ruled the SEC cannot retroactively declare a crypto token a security after years of silence and market reliance. The decision guts the agency’s “we’ll know it when we see it” enforcement style and hands the industry a rare moment of breathing room. For traders and exchanges still reeling from years of regulatory whiplash, the opinion is the clearest signal yet that courts will no longer rubber-stamp the SEC’s expanding definition of “investment contract.”

The fight began when the SEC charged a crypto project with selling unregistered securities, arguing its token met the Howey test. The company fought back, claiming the agency had never warned the industry that such tokens were securities and had in fact green-lit similar products through inaction. On appeal, the Fifth Circuit focused on fair notice: whether the SEC’s sudden enforcement violated due process when the same agency had stayed silent for years. The judges ruled that the SEC’s enforcement-by-surprise crossed a constitutional line and that the agency must give market participants clear rules before punishing them.

The SEC loses the case and the power to spring enforcement actions on long-standing market practices. The crypto project wins, but more importantly, every token issuer and exchange that relied on the agency’s past inaction gains a shield. Going forward, the SEC will have to issue explicit guidance or rulemaking before it can label tokens securities and bring enforcement actions. The ruling does not erase the Howey test, but it forces the agency to use it prospectively, not as an after-the-fact trap.

In plain English, the court told the SEC it cannot change the rules of the game mid-match. If the agency wants to treat tokens as securities, it must say so clearly and in advance. Vague speeches and enforcement-first tactics no longer pass constitutional muster in the Fifth Circuit.

The decision shifts power away from the SEC and toward exchanges and DeFi protocols that can now argue lack of fair notice when facing enforcement. Stablecoin issuers and token projects gain leverage in settlement talks, while traders may see reduced delisting pressure on tokens previously deemed “at risk.” CFTC authority over commodities remains untouched, but the ruling sharpens the line between what the SEC can police and what it must leave alone until it writes new rules. Decentralized projects that never registered or sought guidance are the biggest immediate winners.

Exchanges operating in the Fifth Circuit now have precedent to push back against enforcement letters that feel like regulation by ambush, while traders should watch for a wave of projects testing the limits of this new fair-notice defense.

×