Bastion Secures Conditional OCC Approval for National Trust Bank Charter

Bastion Receives Conditional OCC Approval for National Trust Bank Charter

Bastion has received conditional approval from the U.S. Office of the Comptroller of the Currency (OCC) for a national trust bank charter, marking a regulatory milestone for the company.

Approval Remains Conditional

The OCC’s decision does not represent final authorization to begin operating as a national trust bank. Bastion must satisfy the conditions outlined by the regulator before receiving full approval and commencing chartered activities.

What the Charter Could Mean

A national trust bank charter can allow an institution to provide certain fiduciary and custody services under federal oversight. The scope of Bastion’s permitted activities will depend on the terms of the OCC’s approval and the company’s ability to meet applicable regulatory requirements.

The development highlights the continued use of regulated banking structures by companies operating in or serving the digital-asset sector. Further details about Bastion’s planned services and the conditions attached to the approval were not provided in the available update.

SEC Drops Fifth Circuit Appeal, Leaves Crypto Token Classification Unsettled

Wellermen Image SEC Drops Appeal in Major Crypto Suit: Court Leaves Classification Question Unresolved

The Fifth Circuit quietly ended the SEC’s appeal in a high-stakes crypto case on April 17, leaving the core legal question—whether certain tokens are securities—untouched. The agency simply withdrew, signaling it may prefer to fight elsewhere rather than risk an adverse precedent in Texas. For markets, the retreat keeps uncertainty alive, but it also buys exchanges and DeFi projects time to keep operating without new restraints from this circuit.

The litigation began when the SEC sued a crypto exchange and several token issuers, claiming unregistered securities sales. After a lower-court judge narrowed the agency’s case and questioned its reach over secondary-market trading, the SEC filed an interlocutory appeal. By the time the Fifth Circuit heard argument, the broader regulatory climate had shifted, with Congress eyeing stablecoin legislation and the Commission itself under new leadership pressure. Rather than push for a sweeping Fifth Circuit opinion that could bind future panels, the SEC moved to dismiss its own appeal.

Judges granted the request without comment, so no new rule emerged on Howey-test application, commodity-versus-security distinctions, or the scope of broker-dealer registration. The underlying district-court rulings remain in force inside the circuit, yet they lack the appellate stamp that would have made them persuasive authority nationwide. Plaintiffs in the original suit can still pursue their claims, but the SEC’s withdrawal effectively freezes the status quo for everyone else.

In plain terms, the Fifth Circuit never decided whether the tokens at issue were securities, leaving judges and market participants to guess how similar cases might turn out. The SEC retains its nationwide enforcement toolkit, but it has lost a chance to lock in favorable precedent here. Exchanges and protocols gain breathing room, while traders face the same fog they had before the appeal was filed.

Market participants read the move as the agency conserving resources for friendlier venues and perhaps for expected legislation that could redefine crypto jurisdiction. A win in the Fifth Circuit would have emboldened private plaintiffs and state regulators; its absence tilts leverage back toward platforms that can argue, plausibly, that secondary sales sit outside the securities laws. Stablecoin issuers, meanwhile, continue to watch Congress rather than the courts for clearer guardrails.

For traders, the lesson is unchanged: classification fights remain unsettled, and enforcement risk migrates with every new headline rather than every new precedent.

New York Court Makes Risk-Disclosures a Gatekeeper for Commodity Claims

Wellermen Image Regal Commodities v Tauber: New York Court Hands Commodity Traders a New Shield

New York’s Appellate Division just told commodity brokers they can’t collect on oral promises when the customer never signed the risk-disclosure forms the law requires. The decision hands retail traders a new defense and puts brokerages on notice that handshake deals will not stick in court.

The dispute started when Regal Commodities sued trader Michael Tauber for roughly $1.4 million in alleged trading losses after a string of unauthorized or badly executed futures trades. Tauber argued the firm never delivered the required risk-disclosure statements under New York’s General Obligations Law § 5-1501, so the account agreement—and any debt—was void from day one. The trial court sided with Regal; the Appellate Division reversed, holding that strict compliance with the statute is a condition precedent to enforcement.

Judges ruled that a brokerage cannot sue on an unsigned or incompletely documented commodity account, even if the trader placed orders and watched markets move. Because Regal skipped the formal disclosures, the entire claim collapsed. Tauber walks away debt-free; Regal eats the loss and must now rewrite onboarding procedures or risk similar wipe-outs.

In plain English, New York just made paper compliance a gatekeeper for broker collections. Miss the forms, lose the lawsuit—regardless of how much a customer traded or how loudly the broker cries foul.

For crypto markets the ripple is immediate. If U.S. exchanges or DeFi protocols ever fall under similar state commodity rules, unsigned wallet agreements or missing risk pop-ups could become litigation landmines. Stablecoin issuers and futures desks already wrestling with SEC versus CFTC turf will now add state disclosure statutes to their checklist. Traders gain leverage; platforms gain paperwork.

Brokers that treat compliance as optional just learned the hard way that courts can hand the bill back to them.

CFTC Wins Rare Mandamus Against Kraft, Forcing Release of Internal Wheat-Trading Docs

Wellermen Image CFTC WINS RARE MANDAMUS WIN AGAINST KRAFT

The Seventh Circuit has ordered a district judge to hand over internal Kraft documents that the CFTC claims show the company manipulated wheat futures in 2011. The ruling strips away a long-standing shield that let corporations bury evidence under broad attorney-client claims, and it signals that regulators probing commodities markets now have a stronger hand when they demand internal records.

The fight started when the CFTC tried to prove Kraft used non-public information to squeeze the wheat market. Kraft refused to turn over hundreds of pages of emails and memos, arguing they were protected by privilege. A lower-court judge agreed and blocked the CFTC’s subpoena. The agency then asked the appeals court for an extraordinary writ of mandamus—an order usually reserved for clear legal errors. The three-judge panel sided with the CFTC, finding that the district court’s privilege rulings were so broad they risked shielding ordinary business advice rather than genuine legal counsel.

Writing for the court, Judge Michael Scudder said the documents at issue were mostly commercial strategy discussions, not confidential lawyer-client exchanges. The panel ordered the district court to re-examine the records under a stricter test that separates routine business talk from actual legal advice. Kraft can still claim privilege on a document-by-document basis, but the blanket protection it enjoyed is gone.

In plain terms, companies can no longer wave a “lawyer copied on the email” flag and expect regulators to back off. The decision narrows the attorney-client privilege in regulatory investigations, making it harder for firms to keep internal market-strategy chatter away from watchdogs.

For crypto markets the ruling carries a quiet warning. If commodity regulators can pierce broad privilege claims in wheat trading, they can do the same when they investigate stablecoin issuers, decentralized-exchange operators, or token-project teams. Documents once shielded because a lawyer was copied—tokenomics memos, treasury-allocation chats, or yield-farming strategy threads—could now land on CFTC desks. Exchanges and DeFi protocols that treat every internal note as privileged may find themselves exposed once an enforcement action begins.

The decision does not expand the CFTC’s legal reach overnight, but it lowers the cost of discovery for the agency and raises the cost of non-compliance for market participants. Traders and issuers who assumed their lawyer-forwarded emails were safe should recalibrate that assumption quickly.

MDL Push Blocked: Crypto Securities Suits Go Separate Dockets

Wellermen Image Court Halts MDL Push in Crypto Class Actions

Three federal lawsuits accusing a major digital-asset exchange of selling unregistered securities have been denied a single-judge consolidation, leaving each case on its own docket for now. The panel’s refusal to centralize the suits signals that courts still view crypto disputes as too fact-specific for blanket handling, a stance that could slow any coordinated regulatory assault on exchanges.

Plaintiff Anthony Motto asked the Judicial Panel on Multidistrict Litigation to merge his Illinois action with two parallel cases—one in California and one in Pennsylvania—arguing that all three turn on the same legal question: whether the exchange’s token sales violated the Securities Act. Defendants opposed centralization, claiming the complaints rest on different marketing statements, investor communications, and state-law overlays. After a single hearing, the panel sided with the exchange, finding that common questions did not outweigh the procedural drag and potential confusion of forcing three dockets together.

The judges ruled that each case can proceed independently without creating duplicative discovery or conflicting rulings, a win for defendants who now face three separate plaintiffs’ teams rather than one unified front. Plaintiffs lose the efficiency of shared depositions and document production, but gain the ability to tailor arguments to local judges and juries. Practically, nothing about the underlying securities claims has changed; the exchange simply avoids the spotlight of a nationally coordinated proceeding.

In plain English, the decision keeps the legal risk fragmented. The exchange dodges the narrative that a single judge could set precedent for the entire industry, while plaintiffs retain flexibility to press their strongest facts in friendlier venues.

For crypto markets, the ruling underscores that SEC enforcement still travels through ordinary courts rather than specialized panels, reducing the chance of a sweeping liability finding that could chill token listings or force mass delistings. Decentralized protocols and offshore exchanges gain breathing room because plaintiffs must fight state-by-state, raising costs and timelines. Traders will watch whether this fragmented approach emboldens the Commission to pursue individual enforcement actions instead of broad class actions, a scenario that historically moves prices on rumor rather than judgment.

The takeaway: until a higher court or Congress forces consolidation, expect crypto litigation to remain a slow, jurisdiction-by-jurisdiction grind that favors those who can outlast multiple dockets.

Bitcoin Weekly Recap: CLARITY Stalls as Kraken Eyes On-Chain Perps

Crypto Week in Review: CLARITY Act Talks Continue as Kraken Plans On-Chain Perpetuals

Regulatory negotiations, institutional adoption and trading infrastructure dominated this week’s cryptocurrency news. Seven Democratic senators said they would continue negotiations on the CLARITY Act, while market strategist Tom Lee offered a bullish outlook for the sector. Elsewhere, attackers targeting Revolut demanded a ransom in Monero, Kalshi strengthened its position in U.S. prediction markets, and Kraken’s parent company outlined plans for on-chain perpetual contracts.

Senators Continue CLARITY Act Negotiations

Seven Democratic senators pledged to keep negotiating on the CLARITY Act, a proposed framework addressing the regulatory treatment of digital assets in the United States.

The legislation is part of broader efforts in Congress to establish clearer rules for cryptocurrency markets, including oversight responsibilities and the classification of digital assets. Continued negotiations suggest that lawmakers have not reached a final agreement on the bill.

Tom Lee Forecasts a Bullish Year for Crypto

Tom Lee, a prominent market strategist, projected a bullish 12-month outlook for the cryptocurrency sector. His forecast comes as investors continue to assess institutional participation, regulatory developments and the broader adoption of blockchain-based financial products.

Market forecasts remain subject to significant uncertainty, particularly as digital assets continue to respond to changes in monetary policy, regulation and investor risk appetite.

Revolut Attackers Demand Monero Ransom

Attackers who allegedly obtained customer data from financial technology company Revolut demanded 6,000 Monero, also known by its ticker symbol XMR.

Monero is a privacy-focused cryptocurrency designed to obscure transaction details. Its privacy features have made it a recurring payment option in ransomware and extortion demands, although the use of privacy coins does not establish whether a ransom will be paid or whether the attackers can access the requested funds.

Kalshi and Kraken Expand Crypto Market Infrastructure

Kalshi accounted for approximately 80% of U.S. prediction-market trading volume during the period covered, underscoring the company’s leading position in a rapidly expanding market. Prediction markets allow participants to trade contracts tied to the outcomes of future events.

Meanwhile, Payward, the parent company of cryptocurrency exchange Kraken, unveiled plans to prepare for on-chain perpetual contracts. Perpetuals are derivatives that allow traders to take leveraged long or short positions without a fixed expiration date. Moving such products on-chain could connect trading activity more directly to blockchain-based settlement and infrastructure.
Fifth Circuit Slams SEC Overreach, Crypto Gets Breathing Room

Wellermen Image Court Slams SEC Overreach—Crypto Gets Breathing Room
The Fifth Circuit just clipped the SEC’s wings in a ruling that could reshape how digital assets are policed. By vacating the agency’s attempt to expand its reach without clear statutory authority, the court handed crypto markets a rare moment of legal clarity. The decision signals that regulators cannot simply declare new powers; they must point to actual law.

The case began when the SEC pursued enforcement against a crypto platform, arguing that certain tokens qualified as securities and therefore fell under its jurisdiction. The platform pushed back, claiming the agency had stretched definitions beyond what Congress intended. On appeal, the Fifth Circuit zeroed in on one core question: whether the SEC could unilaterally broaden its mandate to cover emerging digital assets without fresh legislative backing. The judges answered with a firm no, ruling that the agency’s expansive interpretation lacked sufficient grounding in existing statutes. In practical terms, the court sided with the industry, forcing the SEC to narrow its claims and potentially rethink its enforcement playbook.

The legal impact is straightforward: regulators must now demonstrate that a token or platform meets the traditional “investment contract” test rather than assuming authority over anything labeled crypto. This raises the bar for enforcement actions and gives exchanges and DeFi projects more room to operate until Congress clarifies the rules.

For markets, the ruling tilts power away from the SEC and toward the CFTC’s commodity-based framework, at least for now. Stablecoins and utility tokens face lower immediate classification risk, though projects that promise profits tied to managerial efforts remain vulnerable. Exchanges gain negotiating leverage in settlement talks, while DeFi protocols may accelerate product launches knowing courts are scrutinizing agency overreach. Traders should expect short-term relief in sentiment, but volatility will persist as long as legislative boundaries stay fuzzy.

The message is clear: enforcement by interpretation is on notice—build accordingly.

Monex Win: Ninth Circuit Narrows CFTC’s Commodity Exemption

Wellermen Image COURT SLAMS CFTC IN MONEX CASE, UPHOLDS KEY COMMODITY EXEMPTION
The Ninth Circuit just handed the CFTC a stinging defeat in its seven-year campaign against Monex Credit, ruling that the agency lacks authority to police leveraged metals trades that never touch actual futures contracts. In a 2-1 decision, the court slammed the brakes on an enforcement theory that would have let the CFTC reach deep into spot-commodity markets whenever leverage is present. The ruling immediately narrows the agency’s reach and hands crypto exchanges, DeFi platforms, and any token project promising “margin” a powerful new shield.

The case began in 2017 when the CFTC sued Monex for allegedly running an illegal off-exchange retail commodity transaction business. Monex let customers buy and sell gold, silver, and other metals on 5-to-1 leverage with no intention of taking physical delivery. The agency argued the trades were functionally identical to futures and therefore fell under its jurisdiction. Monex countered that the transactions were spot sales of actual commodities, explicitly exempted by Congress in the 2010 Dodd-Frank Act so long as the metals were “actually delivered” within 28 days. The district court agreed with Monex and tossed the suit; the CFTC appealed.

Writing for the majority, Judge Kenneth Lee held that “actual delivery” means precisely what it says: the customer must gain possession or control of the metal, even if only momentarily. Because Monex’s customers never received the physical commodity, the trades did not qualify for the exemption—but the panel still ruled that the CFTC cannot police the transactions unless they are executed on a designated contract market or resemble regulated futures. In short, the court rejected the agency’s attempt to stretch “commodity” jurisdiction over every leveraged metals deal, leaving Monex and similar dealers outside CFTC oversight. Judge John Owens dissented, arguing the majority’s reading guts the statute’s consumer-protection purpose.

In plain English, the decision tells the CFTC it cannot invent new authority simply because a product is leveraged or volatile. If the commodity changes hands in a genuine sale—even a leveraged one—the agency’s writ stops. The ruling does not bless fraud; it simply says the CFTC must prove the trades are futures-like, not merely risky.

For crypto markets the implications are immediate. Exchanges and DeFi protocols offering leveraged spot trading in tokens or stablecoins now have a ready-made defense against CFTC enforcement, at least in the Ninth Circuit. The decision pushes the agency toward a narrower lane: policing only those products that mimic traditional futures or trade on regulated venues. Stablecoin issuers and token projects can argue their leveraged offerings are “actual delivery” spot sales, complicating the Commission’s attempts to label every margin product a de-facto future. Centralized exchanges lose a layer of regulatory moat; offshore or DeFi competitors gain ground.

Traders should read the opinion as a yellow light, not a green one. Leverage remains risky, enforcement theories can still evolve, and the CFTC retains anti-fraud powers. But the structural threat of an ever-expanding regulatory perimeter has receded—for now.

DC Circuit Upholds CFTC Authority Over Crypto Derivatives

Wellermen Image COURT HANDS KITCHEN A DEFEAT — AND CFTC A WIN
The D.C. Circuit just told former crypto trader Trevor Kitchen that the Commodity Futures Trading Commission can punish him for trading unregistered Bitcoin swaps, even though Kitchen claimed the agency lacked jurisdiction. In a crisp, 14-page opinion, the three-judge panel upheld a $450,000 civil penalty and a permanent trading ban, signaling that the CFTC’s reach over crypto derivatives remains intact.

Kitchen had argued that his contracts were not “swaps” under the Commodity Exchange Act because they settled in Bitcoin rather than dollars. The CFTC countered that any agreement whose value derives from a commodity—including digital assets—falls under its watch. Writing for the court, Judge Wilkins rejected Kitchen’s reading, holding that Bitcoin itself is a commodity and that the settlement mechanism does not change the economic reality of the trade. The panel also found Kitchen’s due-process claim unpersuasive, noting he had ample notice that his activity could trigger enforcement.

The ruling tightens the noose around unregistered crypto-derivative platforms. Exchanges that still offer Bitcoin swaps or perpetuals without CFTC registration now face clearer liability, and traders who rely on jurisdictional gray areas may find courts less sympathetic. Meanwhile, the decision hands the agency momentum as it pushes Congress for explicit digital-asset authority and negotiates turf with the SEC.

For market participants, the opinion lowers the odds that creative settlement tricks will defeat CFTC oversight. Expect tighter compliance budgets at offshore and DeFi-linked venues, plus renewed scrutiny of any product that references Bitcoin or ether prices. Stablecoin issuers and yield-bearing protocols that embed swap-like mechanics should re-examine their regulatory exposure.

The message to traders and builders alike is simple: treat CFTC registration as a cost of doing derivatives business in crypto, not an optional checkbox.

Bitcoin News: Zcash Holds Above $1,440 After Sharp Rally Pullback

Zcash Pulls Back After Reaching Year-to-Date High as Development Fund Debate Intensifies

Zcash (ZEC) retreated after reaching a year-to-date high of $1,590, falling to around $1,429 before finding support above $1,440. The move represented a roughly 5% daily decline, while attention also turned to an ongoing governance debate over the Zcash Development Fund, which is scheduled to expire in 2028.

ZEC Holds Significant Gains Despite Pullback

The pullback followed a sharp rally in ZEC, Zcash’s native cryptocurrency. Although the token gave up part of its recent advance, it remained substantially above earlier levels and continued to trade near the highs reached during the latest move.

Market participants are monitoring whether support around the $1,440 area can hold. A sustained break below that level could signal further short-term weakness, while stabilization near the support zone would indicate that buyers remain active after the rally.

Development Fund Becomes Focus of Governance Debate

Alongside the price action, Zcash stakeholders are debating the future of the project’s Development Fund. The funding arrangement is set to expire in 2028, making its continuation, modification or replacement a significant governance issue for the Zcash ecosystem.

The fund supports development and related ecosystem activities. Decisions about its future could influence how ongoing work is financed and how resources are allocated across the network.

Governance Decisions Could Affect Zcash’s Outlook

The debate comes as Zcash maintains elevated market attention following its latest rally. While short-term trading remains focused on price levels, the outcome of the funding discussion could shape longer-term development priorities and stakeholder participation.

For now, ZEC’s market performance remains tied to whether it can maintain support after the recent pullback and whether the community reaches consensus on the Development Fund before its scheduled expiration.

Ninth Circuit Rules Bitcoin Mining Contracts Are Futures, Expanding CFTC Authority

Wellermen Image CFTC WINS CRYPTO JURISDICTION FIGHT IN NINTH CIRCUIT
The Ninth Circuit just handed the CFTC a sweeping win, ruling that a man who peddled “bitcoin mining contracts” was selling illegal commodity futures without registration. The decision makes clear that the CFTC—not the SEC—now owns the regulatory hammer for most bitcoin-linked investment schemes, and that courts will treat digital asset contracts the same as traditional futures.

James Devlin Crombie ran a website promising investors steady bitcoin payouts in exchange for upfront cash. He never registered with the CFTC, never disclosed the risks, and never actually mined much bitcoin. When the agency sued, a federal judge in Oakland ordered him to repay nearly $1.3 million and banned him from the futures markets. Crombie appealed, arguing the contracts were not futures and that the CFTC lacked authority over digital assets. The Ninth Circuit rejected every claim, saying the contracts were classic futures: they involved deferred delivery, fixed pricing, and speculation on future bitcoin value.

The panel also brushed aside Crombie’s claim that bitcoin is not a commodity, noting the CFTC’s authority covers “all services, rights, and interests in which contracts for future delivery are presently or in the future dealt in.” Because bitcoin can be traded for future delivery, it is a commodity under the law. The court upheld the full judgment, including a permanent trading ban and restitution order, giving the CFTC its clearest appellate victory yet in crypto.

In plain terms, anyone selling contracts tied to future bitcoin delivery now needs CFTC registration and disclosures. Failure to register can trigger massive fines, bans, and forced repayment—even if the promoter never touches actual coins. The ruling also signals that courts will look past marketing labels to the economic reality of the deal, making it harder for crypto promoters to dodge federal oversight by calling their products something other than futures.

The decision tightens CFTC power over crypto derivatives while leaving the SEC’s jurisdiction over token sales untouched, creating a clearer but still divided regulatory map. Exchanges and DeFi protocols offering leveraged or future-settled bitcoin products now face a higher compliance bar, and traders should expect more enforcement actions and KYC demands on any platform promising future crypto payouts.

For crypto traders and builders, the message is simple: if it looks like a futures contract and trades like one, the CFTC will treat it like one—and they now have the precedent to prove it.

Judge Dabney L. Friedrich Allows Seizure of 24 Crypto Wallets in IRS Probe

Wellermen Image U.S. Judge Greenlights Crypto Wallet Seizures in IRS Probe
Federal agents just cleared a legal hurdle to freeze digital wallets. A D.C. district judge ruled the government can keep its hands on twenty-four crypto accounts tied to an IRS tax probe, even though the owners remain unknown. The decision widens the net for investigators hunting unreported crypto gains and signals that anonymous wallets are no longer safe havens.

The case started when IRS agents traced millions in Bitcoin and other tokens to accounts that appeared to be used for tax evasion. Because the owners never stepped forward to claim the funds, the government filed an in-rem civil forfeiture action against the wallets themselves. The court had to decide a narrow but critical question: can the United States seize cryptocurrency by suing the digital addresses instead of identifiable people?

Judge Dabney L. Friedrich answered yes. She held that the government met the probable-cause standard under the Civil Asset Forfeiture Reform Act and that service by email, blockchain publication, and other electronic means satisfied due process. The ruling keeps the twenty-four accounts frozen and lets forfeiture proceedings move forward, effectively treating blockchain data as sufficient proof of ownership.

In plain English, the decision tells agents and prosecutors that they no longer need a flesh-and-blood defendant to lock down crypto. If an address shows probable cause of tax fraud or money laundering, the coins can be seized now and argued over later.

For markets, the precedent tilts power toward regulators and away from privacy maximalists. Exchanges and DeFi protocols may see a spike in subpoenas and compliance requests, since on-chain tracing just proved good enough for a federal judge. Traders holding large, unexplained stacks should expect heightened audit risk and possible forced disclosures to avoid the same fate.

The takeaway: treat every wallet like it could be Exhibit A in a forfeiture case, because courts now treat it that way too.

Judge Blocks SEC Data Grab in Binance Case, Keeps Exchange Open

Wellermen Image SEC Swings at Binance Again—Misses the Knockout Punch
A federal judge in Washington just refused to hand the SEC an early win against Binance, ruling that the agency cannot yet force the crypto giant to hand over its customer data. The decision keeps Binance in business while the broader fight over whether its tokens qualify as securities drags on—signaling that the Commission’s aggressive enforcement campaign can hit speed bumps when judges demand proof, not just power.

The SEC filed suit last summer, accusing Binance and its U.S. affiliate of running an unregistered securities exchange and commingling customer funds. When the agency asked the court for an emergency order compelling Binance to turn over user records and block U.S. traders from its global platform, Judge Amy Berman Jackson instead demanded more evidence. She found the SEC had not shown an immediate risk of irreparable harm that justified a preliminary injunction, and she questioned whether the agency could prove its case without first establishing that Binance tokens are securities under the Howey test. The ruling keeps the case alive but stalls the SEC’s attempt to squeeze Binance into a quick settlement.

Binance wins breathing room; the SEC loses momentum. The company can continue onboarding new users and processing trades while its lawyers probe the Commission’s theory that secondary sales of BNB and other tokens on its exchange count as unregistered securities offerings. Traders who feared a sudden freeze of Binance assets now see a slower legal grind ahead, but they also see that judges will not rubber-stamp broad enforcement requests without a clear legal hook.

In plain English, the court told the SEC it cannot treat every crypto platform like an obvious lawbreaker; it must still prove its legal theories in court. That raises the bar for future enforcement actions, making it harder for the agency to extract emergency concessions from exchanges or DeFi protocols before facts are fully litigated.

For markets, the decision hints that the SEC’s authority over crypto exchanges is not unlimited and that commodity-based arguments—where CFTC jurisdiction might apply—could gain traction. Stablecoins and governance tokens now carry slightly less regulatory overhang, while traders may shift volume back to offshore platforms that appear safer from sudden U.S. intervention. Exchanges could feel less pressure to delist tokens preemptively, though they still face the risk that a later ruling reclassifies those assets as securities.

The message to both regulators and traders is clear: enforcement power still matters, but judges will insist on legal proof before they let the SEC pull the trigger.

Bitcoin News: Ethereum Price Falls From $2,668 as Momentum Fades

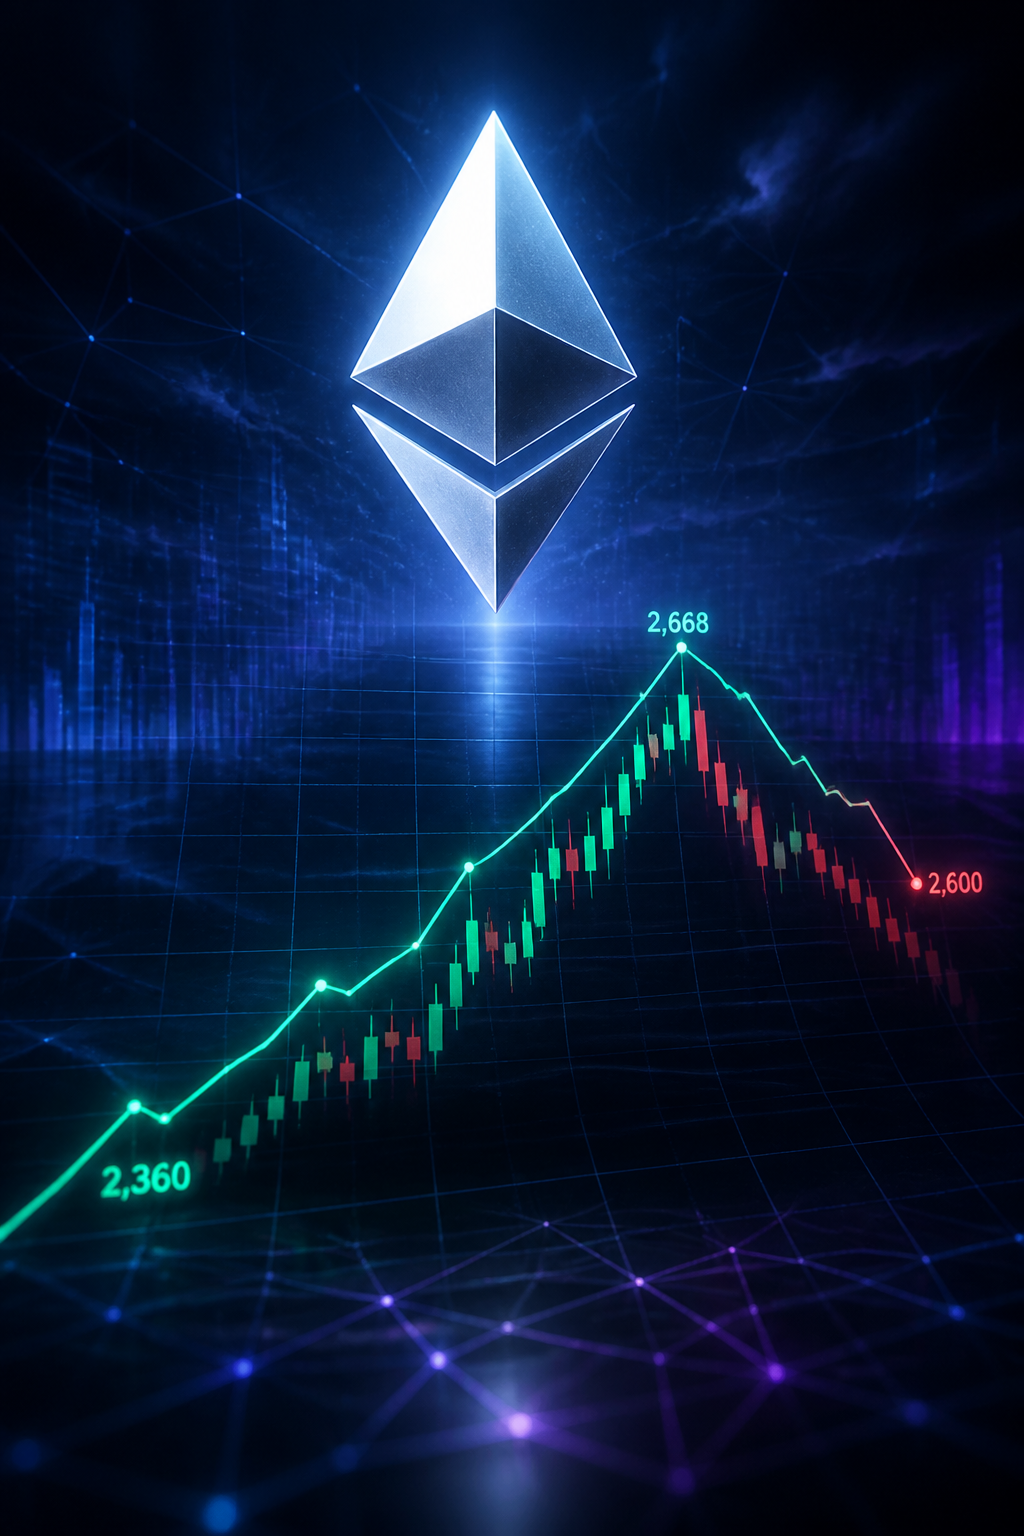
Ethereum has retreated toward $2,600 after rallying from approximately $2,360 to nearly $2,668 within a matter of days. Despite the rebound, the second-largest cryptocurrency by market capitalization remains well below its October 2025 peak, while market forecasts continue to span a wide range for the rest of the year.

Ethereum Pulls Back After Sharp Rally

Ether’s recent advance carried its price close to $2,668 before momentum began to weaken. The asset has since moved back toward the $2,600 level, marking a pause after a rapid climb of more than 13% from the $2,360 area.

The pullback highlights the volatility that continues to characterize the Ethereum market. Short-term gains have not yet reversed the broader decline from the asset’s October 2025 peak near $4,946.

ETH Remains Below October Peak

At prices near $2,600, Ethereum is roughly 47% below its previous peak. The gap underscores the scale of the recovery required for ether to return to its former high, even after its latest rally.

Market participants are also assessing whether the recent move represents the start of a sustained recovery or a temporary rebound within a broader period of weakness. Price momentum can shift quickly in cryptocurrency markets, particularly after sharp short-term advances.

Forecasts Point to Wide Range of Outcomes

Forecasts for Ethereum’s price through the end of the year vary significantly. Some projections place ether near $4,000, while more aggressive estimates extend as high as $10,000.

Reaching those levels would require Ethereum to build on its recent gains and overcome the distance from its October high. The asset’s next direction is likely to depend on whether buying pressure returns after the latest retreat and whether the broader cryptocurrency market remains supportive.

Delaware Court Slams Token Sale, Expands Fiduciary Duties for Crypto Offerings

Wellermen Image Court Slams Delaware Company Over Crypto Token Sale

Delaware Superior Court just handed down a verdict that could reshape how token issuers and investors approach crypto fundraising in the state. The ruling finds that Diamond Fortress Technologies Inc. and its founder Charles Hatcher II breached their fiduciary duties when they sold crypto tokens to a group of investors, and it sets a new standard for how courts may scrutinize token sales that blend corporate governance with digital asset distribution.

The case began when investors accused Diamond Fortress of misleading them about the nature of the token offering and the company’s governance structure. Plaintiffs alleged that Hatcher, acting through the company, sold tokens that promised future utility and value appreciation but failed to disclose critical information about the token’s liquidity, lock-up terms, and the company’s financial health. The dispute escalated into a lawsuit claiming breach of fiduciary duty, fraud, and violations of Delaware corporate law. After a bench trial, the court ruled that the token sale was conducted in a manner that prioritized the insiders’ interests over those of outside investors, and that Hatcher had not acted with the required care or loyalty.

The judges determined that Diamond Fortress and Hatcher were liable for damages stemming from the token sale, holding that the transaction constituted a self-dealing act that violated Delaware’s strict standards for corporate fiduciaries. The court rejected arguments that the tokens were mere commodities outside the scope of fiduciary oversight, instead finding that the sale was inextricably linked to the company’s governance and that the defendants had a duty to disclose material facts. This decision marks a significant win for the plaintiffs and a warning to other Delaware companies that token offerings tied to corporate actions will be treated like traditional securities transactions under state law.

In plain English, the court said that selling tokens is not a loophole around fiduciary responsibility. If a Delaware company raises money by issuing digital assets, its directors and officers still owe the same duties they would in a stock offering. The ruling collapses the notion that crypto structures can sidestep Delaware corporate law simply by calling the investment a “token” rather than a “share.”

For crypto markets, this decision tightens the screws on token issuers incorporated in Delaware and signals that the SEC and state regulators may find a receptive audience in Delaware courts when pursuing enforcement actions. The case underscores the decentralization-versus-regulation tension, as founders who believed they could operate outside traditional governance norms now face real legal exposure. Exchanges and DeFi protocols that list tokens from Delaware entities may see increased diligence requirements, and traders should expect more volatility as issuers scramble to re-evaluate their structures and disclosures.

Delaware’s message to the industry is clear: if you raise money through tokens, you’re playing by corporate law’s rules—ignore them at your peril.

×