Delaware Court Slams Token Sale, Expands Fiduciary Duties for Crypto Offerings

Wellermen Image Court Slams Delaware Company Over Crypto Token Sale

Delaware Superior Court just handed down a verdict that could reshape how token issuers and investors approach crypto fundraising in the state. The ruling finds that Diamond Fortress Technologies Inc. and its founder Charles Hatcher II breached their fiduciary duties when they sold crypto tokens to a group of investors, and it sets a new standard for how courts may scrutinize token sales that blend corporate governance with digital asset distribution.

The case began when investors accused Diamond Fortress of misleading them about the nature of the token offering and the company’s governance structure. Plaintiffs alleged that Hatcher, acting through the company, sold tokens that promised future utility and value appreciation but failed to disclose critical information about the token’s liquidity, lock-up terms, and the company’s financial health. The dispute escalated into a lawsuit claiming breach of fiduciary duty, fraud, and violations of Delaware corporate law. After a bench trial, the court ruled that the token sale was conducted in a manner that prioritized the insiders’ interests over those of outside investors, and that Hatcher had not acted with the required care or loyalty.

The judges determined that Diamond Fortress and Hatcher were liable for damages stemming from the token sale, holding that the transaction constituted a self-dealing act that violated Delaware’s strict standards for corporate fiduciaries. The court rejected arguments that the tokens were mere commodities outside the scope of fiduciary oversight, instead finding that the sale was inextricably linked to the company’s governance and that the defendants had a duty to disclose material facts. This decision marks a significant win for the plaintiffs and a warning to other Delaware companies that token offerings tied to corporate actions will be treated like traditional securities transactions under state law.

In plain English, the court said that selling tokens is not a loophole around fiduciary responsibility. If a Delaware company raises money by issuing digital assets, its directors and officers still owe the same duties they would in a stock offering. The ruling collapses the notion that crypto structures can sidestep Delaware corporate law simply by calling the investment a “token” rather than a “share.”

For crypto markets, this decision tightens the screws on token issuers incorporated in Delaware and signals that the SEC and state regulators may find a receptive audience in Delaware courts when pursuing enforcement actions. The case underscores the decentralization-versus-regulation tension, as founders who believed they could operate outside traditional governance norms now face real legal exposure. Exchanges and DeFi protocols that list tokens from Delaware entities may see increased diligence requirements, and traders should expect more volatility as issuers scramble to re-evaluate their structures and disclosures.

Delaware’s message to the industry is clear: if you raise money through tokens, you’re playing by corporate law’s rules—ignore them at your peril.
Grayscale Wins Court Ruling, Forcing SEC to Revisit Spot Bitcoin ETF Denial

Wellermen Image SEC Suffers Fresh Courtroom Loss on Bitcoin ETF Denial
Grayscale Investments just handed the SEC a stinging defeat in federal court, forcing the agency to revisit its blanket rejection of spot Bitcoin ETFs. The D.C. Circuit ruled that the Commission failed to explain why it approved Bitcoin futures ETFs while rejecting Grayscale’s spot product, exposing a possible double standard that markets have long suspected.

The case began when Grayscale asked the SEC to convert its Bitcoin investment trust into an exchange-traded fund. The Commission turned it down in June 2022, claiming the spot fund would be vulnerable to fraud and manipulation. Grayscale sued, arguing that futures-based ETFs already exposed the same underlying Bitcoin market to the same risks, so the SEC’s refusal was arbitrary. The three-judge panel agreed. Writing for the court, Judge Rao said the agency never offered a “reasoned explanation” for treating economically identical products differently.

The ruling means the SEC must either approve the Grayscale ETF or provide a coherent justification for keeping it off exchanges. That puts the agency on a tight clock; markets expect a fresh decision within weeks. Grayscale wins breathing room and renewed investor confidence, while the Commission loses the luxury of reflexive denials and faces pressure to articulate a consistent policy.

In plain English, the court told the SEC it cannot treat Bitcoin futures and Bitcoin spot products as different animals when they ultimately trade the same asset. Regulators must now either square their logic or drop the inconsistency. The decision does not force an automatic approval, but it strips away the SEC’s most common excuse for delay.

The immediate market read is that spot Bitcoin ETFs move from “unlikely” to “probable,” lifting sentiment for exchanges and custody providers. A win here would also blunt the SEC’s broader campaign to label most tokens as unregistered securities, because an approved spot product signals the agency is willing to tolerate direct Bitcoin exposure. DeFi protocols that rely on Bitcoin collateral may see indirect relief, while traders price in lower regulatory risk and potential inflows once shares start trading.

The SEC still holds cards on timing and conditions, but the days of easy vetoes appear numbered.

Seventh Circuit Rules Paid Crypto Signal Groups Are CTAs, Forcing Registration

Wellermen Image CFTC’s “Trading Advisor” Win Slams Unregistered Crypto Shops
The Seventh Circuit just handed the CFTC its first appellate ruling on whether unregistered crypto operators can be treated as commodity trading advisors, and the answer is yes. James Donelson’s unregistered Telegram signals group—where he charged clients for Bitcoin and Ether trade calls—now counts as a CTA, meaning he needed to register with the agency and accept its rules. The decision widens the regulatory net for every social-media guru promising alpha.

Donelson ran a paid channel that flashed real-time buy-sell signals on crypto futures, collecting monthly fees from more than 300 followers. When prices moved against him and clients lost money, the CFTC sued, arguing that Donelson acted as an unregistered CTA and failed to disclose his dismal track record. Donelson countered that he merely gave informal tips, not “advice tailored to individual accounts,” and that crypto lies outside the CFTC’s lane anyway. The district court sided with the agency; Donelson appealed.

Writing for a three-judge panel, the Seventh Circuit held that “routine advice about commodity futures—even delivered en masse over social media—qualifies as CTA activity if the advisor receives compensation.” The judges rejected Donelson’s “impersonal tips” defense, noting that he urged followers to mirror his positions and charged for the privilege. They also brushed aside the argument that Bitcoin and Ether futures are beyond CFTC reach; the agency’s jurisdiction over futures contracts is explicit, regardless of the underlying asset. Because Donelson never registered, never delivered required disclosures, and never kept books, the court affirmed a permanent injunction and ordered restitution plus civil penalties.

The ruling collapses the gray zone between casual crypto influencers and regulated advisors. Anyone who sells trading signals tied to CFTC-supervised futures must now register, open their performance history, and submit to audits. Failure to do so converts ordinary compliance oversights into fraud charges, exposing operators to asset freezes and treble damages. The decision also telegraphs that platforms hosting paid signal rooms—Telegram, Discord, even Twitter Spaces—may face secondary liability if they know the rooms are unregistered.

For traders, the immediate effect is a shrinking menu of paid alpha channels and a flight toward either fully registered advisors or fully anonymous, free communities. Exchanges listing crypto futures will see compliance teams tighten KYC on signal providers who direct volume to their platforms. Meanwhile, the SEC watches: if a futures-based signal service counts as a CTA, token-based copy-trading apps that promise leveraged returns could soon face parallel investment-adviser rules. Decentralized autonomy just collided with registration reality, and registration won.

Bottom line: unregistered signal sellers betting that crypto’s borderless nature would shield them from U.S. oversight just learned the border moved.

Bitcoin News: Saylor Signals a Fresh Bitcoin Buying Strategy

Michael Saylor Renews Speculation About New Strategy Bitcoin Purchase

Michael Saylor has revived speculation that Strategy Inc. may resume buying bitcoin after sharing an “orange” market signal and an updated holdings chart. The post came after the company paused bitcoin purchases for roughly two weeks.

Saylor Shares New Bitcoin Signal

Saylor, Strategy’s executive chairman, posted the chart on social media without confirming that the company had completed another bitcoin purchase. His recurring “orange” posts have previously drawn attention from investors monitoring Strategy’s bitcoin accumulation strategy.

The latest signal has prompted renewed discussion over whether the company could announce another acquisition in the near term. However, the post itself does not establish that a purchase has taken place or provide details about any potential transaction.

Strategy Maintains 845,050 BTC

Strategy’s reported bitcoin holdings remain at 845,050 BTC following the recent buying pause. The company has built its corporate treasury around bitcoin and regularly discloses purchases through regulatory filings and public announcements.

In addition to its bitcoin holdings, Strategy has retained billions of dollars in cash and other liquidity. That financial position could provide the company with flexibility to pursue additional acquisitions, although any future purchase would depend on management decisions, available funding and market conditions.

Investors Await Official Disclosure

Strategy’s bitcoin purchases have become a closely watched market event because of the company’s size and its influence on corporate cryptocurrency adoption. An official announcement or regulatory filing would be required to confirm any new acquisition, including the amount of bitcoin purchased and the average price paid.

Third Circuit Blocks Coinbase Bid to Compel SEC Rulemaking

Wellermen Image Court Slaps Coinbase in SEC Showdown
The Third Circuit just shut down Coinbase’s bid to force the SEC into court over crypto rules. Judges ruled that the agency’s refusal to launch a formal rulemaking process on digital assets is not something Coinbase can challenge right now. The decision keeps the agency’s hands free and leaves exchanges guessing.

The fight started when Coinbase asked the SEC to write clear rules for crypto trading and custody. The agency said no, and Coinbase sued, arguing that years of enforcement-by-lawsuit created unfair uncertainty. The Third Circuit didn’t buy it. It held that an agency’s choice not to regulate is generally immune from judicial second-guessing unless Congress explicitly says otherwise. Coinbase’s petition was tossed for lack of jurisdiction.

What changes now is leverage. The SEC keeps its preferred weapon—case-by-case enforcement—while Coinbase and other platforms lose a potential shield of regulatory clarity. Traders still face the same fog: tokens could be labeled securities tomorrow, or not, depending on which case the agency brings next.

In plain English, the court told Coinbase it can’t drag the SEC to the rulemaking table just because the current game feels rigged. The agency decides when and how to draw lines; courts won’t force its hand.

That ruling tightens the SEC’s grip and loosens pressure on exchanges to prove tokens aren’t securities. Stablecoin issuers and DeFi protocols stay in the crosshairs, because nothing in this decision limits how aggressively the agency can pursue individual actions. Centralized exchanges may slow new listings and lean harder on legal opinions, while decentralized venues keep betting that code is harder to sue than a company.

For traders, the message is simple: regulatory whiplash isn’t going away anytime soon, so price in the risk that today’s altcoin could be tomorrow’s enforcement target.

Trump Plans US ‘AI Force’ and AI Czar Appointment: Reports

Trump Reportedly Plans ‘AI Force’ and AI Czar to Oversee Industry

President Donald Trump reportedly plans to create an “AI Force” and appoint an artificial intelligence czar to oversee the rapidly expanding sector, according to reports.

Proposed AI Initiative

Trump said in a post on Truth Social that the new project would manage the fast-growing artificial intelligence industry. The proposal would place greater focus on coordinating the sector at the federal level.

Emphasis on Innovation

Trump indicated that the initiative would seek to support continued development without introducing regulations that could slow innovation. Further details about the proposed structure, responsibilities and timeline were not immediately available.

Crypto’s 10 Biggest Mysteries: Vanished Founders, Lost Fortunes and Unsolved Deaths

Wellermen Image

Crypto’s Biggest Mysteries Still Defy Clear Answers

Crypto’s history is filled with missing founders, unexplained deaths, vanished fortunes, and allegations that remain unresolved. These cases matter because they expose the industry’s recurring weaknesses: anonymous operators, weak oversight, opaque finances, and investors left with little protection when trust collapses.

The latest roundup revisits 10 of the sector’s most enduring mysteries, including the whereabouts of the so-called CryptoQueen and the strange death of a DeFi builder who reportedly feared a powerful “pedo elite.” The stories span fraud, crime, technology, and conspiracy—but the common thread is that key facts remain missing.

The CryptoQueen case is among the most notorious. Ruja Ignatova helped promote OneCoin as a revolutionary digital currency before disappearing as the project unraveled and investors were left facing billions in alleged losses. Her disappearance turned a financial scandal into one of crypto’s most persistent manhunts.

Other cases involve deceased or missing developers, disputed identities, lost wallets, and projects whose inner workings were never fully explained. In several instances, speculation has filled the gap left by incomplete investigations, making it difficult to separate credible evidence from internet mythology.

What This Means for Crypto

In plain English, these mysteries show why crypto users cannot treat decentralization as a substitute for accountability. A blockchain may preserve transactions, but it cannot guarantee that founders are honest, treasury funds are safe, or investigators will recover assets after a collapse.

Traders face the immediate risk of buying into projects controlled by anonymous or unverified teams. Long-term investors should scrutinize governance, custody arrangements, audited finances, and the identities of decision-makers before treating a token as a serious investment.

Market Impact and Next Moves

The short-term market effect is likely mixed rather than directly bullish or bearish. Mystery-driven stories can attract attention and reinforce crypto’s rebellious image, but they also remind institutions and cautious investors why regulation, disclosure, and stronger enforcement remain central to mainstream adoption.

The biggest risks are fraud, exchange and custody failures, legal uncertainty, and the leverage that can turn an opaque project into a fast-moving disaster. The opportunity lies with networks and companies that do the opposite: publish verifiable data, use transparent governance, and build products that can survive scrutiny.

In crypto, unanswered questions are not harmless intrigue—they are often the first warning that risk has been hidden in plain sight.

Crypto Groups Take Illinois to Court Over 0.2% Tax Before January Launch

Wellermen Image

Crypto Groups Move to Stop Illinois Tax Before January

The Crypto Council for Innovation and Blockchain Association are seeking to block Illinois’ planned 0.2% tax on crypto activity. The groups argue the levy is unconstitutional and could create expensive compliance demands for businesses and investors.

The challenge follows an earlier lawsuit targeting the Illinois measure, which is scheduled to take effect in January. By returning to court before the deadline, the trade groups are trying to prevent companies from having to build tax systems around a rule they believe may ultimately be overturned.

The dispute puts Illinois at the center of a broader fight over how governments should tax digital assets. A 0.2% charge may appear small, but crypto markets can involve frequent transactions, transfers, and settlement activity, meaning compliance costs could quickly outweigh the headline rate for exchanges, custodians, and other firms.

What This Means for Crypto

In plain English, the groups are arguing that Illinois cannot impose the tax in its current form and that enforcing it would burden the industry with costly tracking and reporting requirements. The case could affect more than the tax bill itself if the court questions how states regulate and collect revenue from crypto markets.

Traders may see little immediate change, but businesses operating in Illinois face greater uncertainty over pricing, reporting, and expansion plans. A court victory for the industry could limit similar state-level taxes, while a defeat could encourage other jurisdictions to pursue comparable measures.

Market Impact and Next Moves

The short-term market reaction is likely mixed rather than dramatic. This is primarily a legal and compliance battle, not a direct threat to a major token, but uncertainty can still push crypto companies to delay investment or consider moving activity to friendlier jurisdictions.

The key risks are regulatory fragmentation, unexpected compliance costs, and a patchwork of state rules that makes operating in the United States harder. The opportunity lies in clearer legal boundaries: if the court rejects the tax, the decision could provide important support for crypto businesses facing aggressive state-level taxation.

Illinois’ crypto tax fight is a warning that the next major industry battle may be decided in courtrooms, not on exchanges.

Fake USDT Scams Target Venezuelan Merchants: Bitcoin Users Need to Know

Scammers Target Venezuelan Merchants With Fake USDT Payments

Scammers are reportedly exploiting the widespread use of Tether’s USDT stablecoin in Venezuela by sending counterfeit tokens as payment. The tokens appear to resemble USDT but have no monetary value, potentially causing losses for merchants who accept cryptocurrency through self-custody wallets.

Counterfeit Tokens Mimic USDT

According to reports, threat actors are creating or transferring tokens designed to look like legitimate USDT. These assets may use similar names, symbols, or branding, making them difficult to distinguish from the genuine stablecoin during a transaction.

Unlike authentic USDT, counterfeit tokens are not issued by Tether and are not redeemable for U.S. dollars. Their presence in a wallet does not confirm that a valid payment has been made.

Self-Custody Wallets Require Additional Verification

The reported scams primarily target merchants who accept payments directly through self-custody wallets. In these transactions, users are responsible for checking the asset, blockchain network, contract address, and transaction details.

A payment may appear in a wallet while still having no practical value if it involves an unrelated or fraudulent token. Merchants can reduce the risk of accepting counterfeit assets by verifying that the token contract matches the official contract for USDT on the relevant network and by confirming the transaction through a trusted blockchain explorer.

USDT’s Role in Venezuela

USDT is widely used in Venezuela for payments, savings, and transfers because it is designed to track the value of the U.S. dollar. Its adoption has also made the stablecoin a target for fraudsters seeking to exploit gaps in payment verification.

Users and merchants should treat the appearance of a token in a wallet as only one step in confirming a payment. Verifying the asset’s authenticity and the transaction’s status before releasing goods or services is essential.

Consensys Splits MetaMask From Institutional Blockchain Business

Wellermen Image

Consensys Splits MetaMask From Institutional Blockchain Operations

Consensys is restructuring to separate MetaMask’s consumer wallet business from its Ethereum protocols and institutional blockchain infrastructure operations. The move could give each division a sharper strategy as crypto adoption expands beyond retail trading.

The split places MetaMask on one side of the business and Consensys’ infrastructure and Ethereum-focused operations on the other. MetaMask serves everyday users accessing wallets, decentralized applications, and on-chain finance, while the institutional unit targets organizations building or using blockchain systems.

No financial terms or detailed timeline were provided, but the restructuring signals a push for clearer focus. Consumer wallet products and institutional blockchain infrastructure face different customers, regulations, revenue models, and competitive pressures; combining them can create strategic drag.

MetaMask could benefit from greater independence if it can move faster on wallet features, user growth, and monetization. Consensys’ institutional business, meanwhile, may gain a more focused mandate to work with enterprises and Ethereum-based infrastructure. The risk is that separating the divisions could reduce shared resources or create uncertainty around product development and governance.

What This Means for Crypto

In plain English, Consensys is dividing a broad crypto company into more specialized businesses. MetaMask is the consumer-facing gateway, while the institutional operation is closer to the plumbing that helps companies build and run blockchain applications.

For users, the immediate impact may be limited, but traders and long-term investors will watch for changes in fees, wallet features, security, and support for decentralized applications. Builders may pay closer attention to whether Consensys’ infrastructure products become more enterprise-focused and easier to integrate.

Market Impact and Next Moves

The short-term market reaction is likely mixed rather than automatically bullish. A cleaner corporate structure can unlock faster decisions and sharper investment, but the lack of detail leaves investors guessing about leadership, funding, timelines, and whether either business will eventually pursue outside capital or a separate listing.

The biggest risks are execution problems, weaker coordination, and regulatory pressure on consumer wallets and institutional blockchain services. The opportunity is equally clear: if MetaMask strengthens its position as a leading wallet while Consensys scales Ethereum infrastructure for large organizations, the restructuring could align each business with a much larger adoption trend.

Consensys is betting that focused businesses can move faster—but the split will matter only if it produces better products, stronger adoption, and clearer value for users and investors.

Raoul Pal: Bitcoin Could Outrun the Nasdaq as Interest Rates Rise

Raoul Pal Says Bitcoin Could Outperform the Nasdaq 100 as Interest Rates Rise

Real Vision founder Raoul Pal believes bitcoin could outperform the Nasdaq 100 from current levels, arguing that higher interest rates may ultimately lead governments to increase liquidity and support risk assets such as cryptocurrencies.

Pal Outlines Macro Case for Bitcoin

Pal presented his view in a six-post thread on X on Friday. The macro investor said rising rates could place greater pressure on governments and financial systems, potentially prompting policymakers to introduce measures that expand liquidity.

According to Pal’s thesis, bitcoin is positioned to benefit from increased liquidity because the cryptocurrency has historically attracted capital during periods of monetary expansion and heightened demand for alternative assets.

Bitcoin and the Nasdaq 100

Pal compared bitcoin’s prospective performance with that of the Nasdaq 100, an index heavily weighted toward large technology companies. He suggested that bitcoin could gain an advantage if liquidity growth accelerates and investors seek assets with higher potential returns.

However, both bitcoin and technology stocks remain sensitive to interest-rate expectations, monetary policy and broader market risk. Higher rates can increase borrowing costs and reduce demand for riskier assets, while any shift toward easier financial conditions may have the opposite effect.

Liquidity Remains Central to Pal’s Outlook

Pal’s argument is based on the relationship between global liquidity and asset prices. His broader market analysis has frequently focused on how government spending, central-bank policy and credit conditions influence cryptocurrencies and other risk assets.

His latest comments represent a market view rather than a guarantee of future performance. Bitcoin’s price remains subject to significant volatility, and its relationship with traditional markets can change as economic conditions evolve.

Fake IT Interviews: How North Korea Stole Millions in Crypto

Fake Tech Interviews Linked to North Korean Crypto Theft Campaign

A North Korean state-backed hacking group infected more than 30,000 computers in at least 100 countries as part of a campaign that stole millions of dollars in cryptocurrency between late 2025 and July 2026.

Attackers Posed as Technology Recruiters

The campaign reportedly used fake job interviews to target technology professionals. Attackers presented the recruitment process as legitimate before directing candidates to download files or run software that contained malware.

Once installed, the malicious software could provide attackers with access to victims’ computers and potentially expose sensitive information, including credentials, private keys and other data linked to cryptocurrency accounts.

Global Reach

More than 30,000 computers across at least 100 countries were reportedly affected. The broad geographic scope reflects the use of online recruitment platforms and remote interview processes to reach potential victims in the technology sector.

The campaign operated from late 2025 through July 2026, according to the available information. The attackers allegedly used the stolen access and information to take millions of dollars in cryptocurrency.

Security Risks for Crypto Users

Cryptocurrency holders and technology workers remain frequent targets of malware campaigns because compromised devices can expose exchange accounts, digital wallets and authentication credentials. Fake employment opportunities can be especially effective because they often involve requests to install software, open documents or access unfamiliar websites.

Security specialists generally advise job candidates to verify recruiters and employers independently, avoid installing untrusted software during an interview process and use dedicated devices or accounts when handling sensitive cryptocurrency assets.

Factory-Sealed 1986 NES Set Sells for $120,000: Retro Games Boom

Factory-Sealed 1986 NES Deluxe Set Sells for $120,000

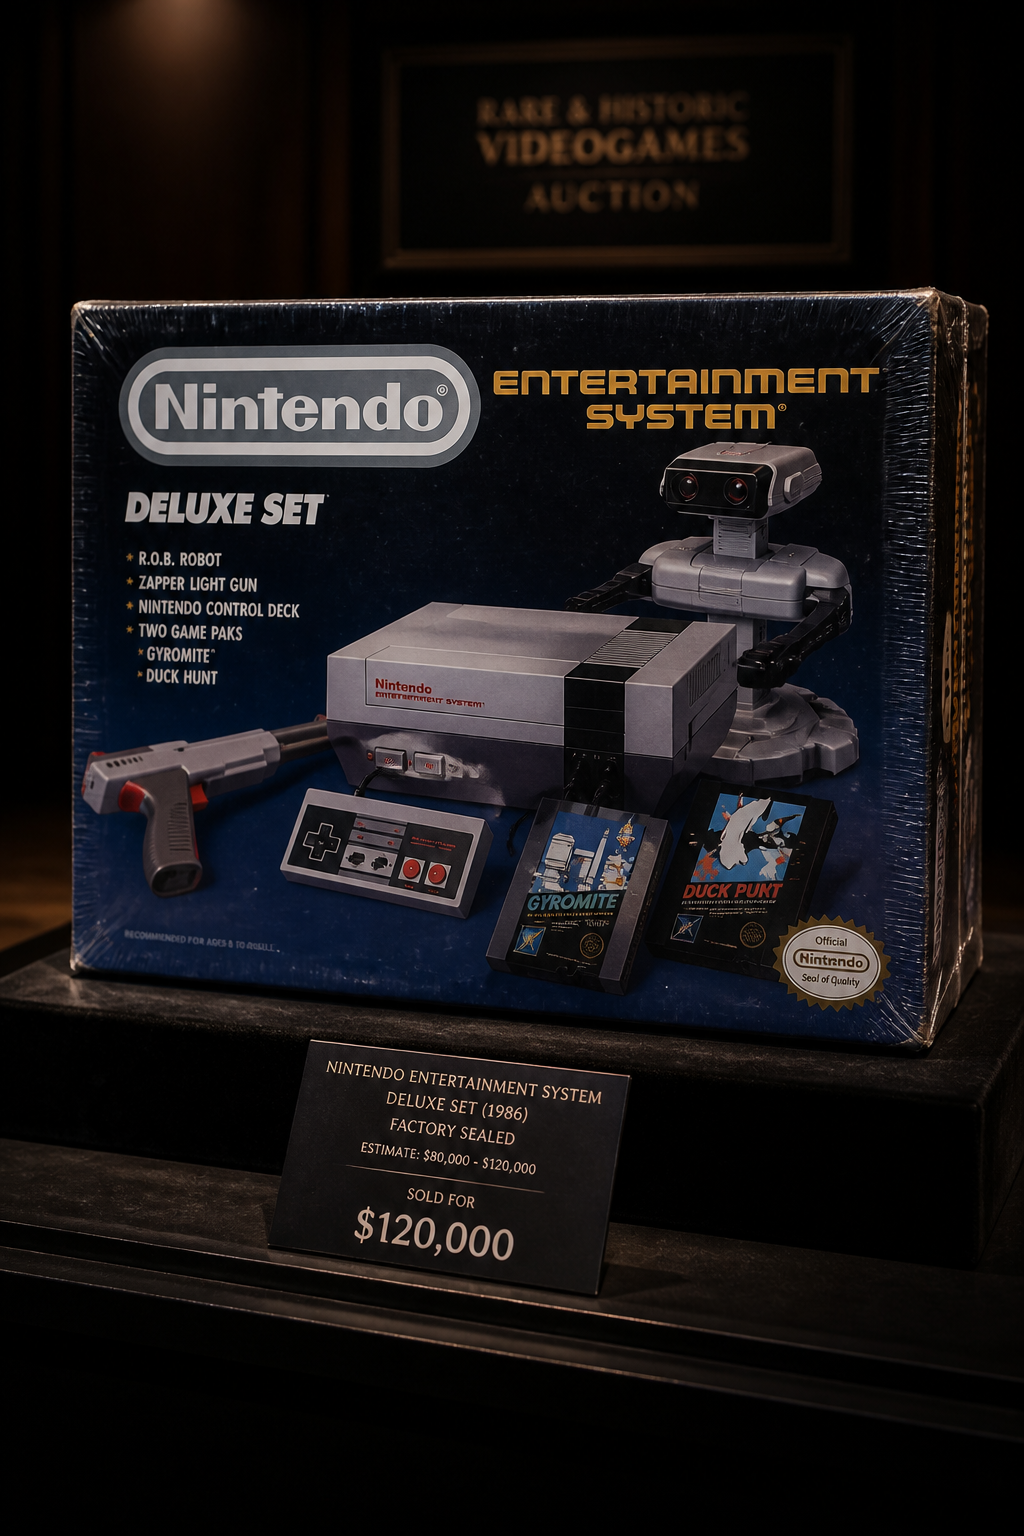
A factory-sealed Nintendo Entertainment System Deluxe Set from 1986 sold for $120,000 at Heritage Auctions in November 2023, setting a record for the highest auction price paid for a commercially released video game console, according to the auction house.

Rare NES Package Draws Record Bid

The unopened set included the original Nintendo Entertainment System console, the R.O.B. robotic accessory, a Zapper light gun, and boxed copies of Gyromite and Duck Hunt.

Its factory-sealed condition was a major factor in the sale. Most NES systems from the 1980s were opened and used, leaving few complete examples with their original packaging and contents intact.

Condition Drives Collectible Value

Collectors typically place a premium on video game hardware that retains its original seal, packaging, and accessories. Complete sets can be especially valuable when they contain launch-era hardware or promotional bundles that were distributed for a limited period.

The 1986 Deluxe Set is also historically significant because it reflects Nintendo’s early efforts to establish the NES in the North American market. The package combined the console with accessories and games designed to demonstrate the system’s capabilities.

Retro Gaming Market Expands

The sale highlights the growing market for vintage video game collectibles, where rarity, provenance, condition, and cultural significance can strongly influence prices. High-value transactions have increasingly included sealed games, prototype hardware, limited-edition releases, and complete console bundles.

Although individual auction results vary, the $120,000 sale demonstrates the premium collectors may place on exceptionally preserved examples of commercially released gaming hardware.

Bitcoin News: Michael Saylor Spots Bigger Crypto Opportunity Beyond CLARITY

Michael Saylor Says Crypto Adoption Matters More Than Legislative Certainty

Michael Saylor, executive chairman of Strategy, said the cryptocurrency industry’s larger opportunity lies in building financial products that achieve broad public use rather than seeking certainty through restrictive legislation.

Adoption as a Growth Strategy

Saylor argued that widespread adoption could deliver practical benefits, including cheaper payments and broader access to financial markets. In his view, products used by millions of people would demonstrate the value of digital-asset technology more effectively than regulatory assurances alone.

His comments reflect a broader debate within the cryptocurrency industry over whether companies should prioritize regulatory clarity or focus on developing services that address existing financial needs.

Economic and Political Impact

Saylor also suggested that broad usage could generate significant economic value and create a durable political constituency for digital innovation. A larger user base, he argued, could increase public and institutional support for policies that encourage the development of cryptocurrency and blockchain technology.

The approach places emphasis on practical utility, including payments and market access, rather than relying primarily on legislative protections or favorable rules.

Regulation Versus Utility

Regulatory uncertainty remains a central issue for cryptocurrency businesses and investors. However, Saylor’s position is that sustained adoption may ultimately provide a stronger foundation for the industry than restrictive frameworks designed to offer certainty.

For digital-asset companies, the challenge is to develop products that are accessible, useful and compliant while demonstrating clear benefits to consumers and businesses.

Court Allows Kalshi to List Election-Outcome Contracts; CFTC Loses Bid

Wellermen Image KALSHI WINS — CFTC LOSES ON ELECTION BETS

A federal appeals court has refused to pause a lower-court ruling that lets KalshiEx offer prediction-market contracts on U.S. elections. The decision keeps the CFTC’s emergency request on hold and signals that, for now, the agency cannot treat these contracts as illegal off-exchange “event contracts.”

The fight began when Kalshi filed for CFTC approval of contracts that pay out based on which party controls Congress. The agency rejected the filing, citing an obscure Dodd-Frank carve-out that bars contracts tied to gaming or “unlawful activity.” Kalshi sued, arguing the language is too vague to cover straightforward political-event bets. District Judge Jia Cobb agreed, issued a preliminary injunction, and ordered the CFTC to let the contracts trade. The agency rushed to the D.C. Circuit seeking an emergency stay that would block trading while the appeal proceeds.

The three-judge panel denied the stay in a two-page order, finding the CFTC failed to show “likelihood of success on the merits” or that it would suffer irreparable harm. That leaves Kalshi free to list the contracts starting this week, pending the full appeal. The CFTC can still argue its case in regular briefing, but it must do so while the contracts are already live.

In plain English, a federal court has told the CFTC it cannot simply wave the “gaming” flag to shut down a licensed exchange. Unless the agency wins on appeal or persuades Congress to change the statute, event contracts on elections—and potentially other hot-button political outcomes—are now legal to trade on CFTC-regulated platforms.

For crypto markets the ruling is a narrow but telling precedent. It shows courts willing to limit the CFTC’s reach over novel contracts, which could embolden DeFi protocols that frame prediction markets as “event derivatives.” At the same time, the decision does not touch the SEC’s jurisdiction, so tokens that mirror these contracts could still face securities-law scrutiny. Exchanges now have a green light to list political contracts, but they also carry new headline and regulatory risk if election volatility triggers accusations of market manipulation.

The CFTC’s loss hands traders a short-term win and a long-term warning: political-event markets are open for business, but the agency is already rewriting its rulebook to close the gap.

×