Court: Perpetual Crypto Swaps Are Futures, Expands CFTC Jurisdiction

Wellermen Image CFTC WINS KEY CASE ON CRYPTO FUTURES JURISDICTION

Trevor Kitchen lost his appeal against the Commodity Futures Trading Commission in a decision that strengthens the agency’s grip on crypto derivatives. The D.C. Circuit ruled that Kitchen’s novel argument—that certain perpetual-swap products fall outside CFTC oversight—fails under current law, leaving the Commission with broader enforcement power.

The dispute began when the CFTC fined Kitchen for operating an unregistered trading platform that offered crypto perpetual contracts. Kitchen contended that because his contracts never expired, they were not “futures” and therefore not subject to the Commodity Exchange Act. The three-judge panel rejected that view, holding that the economic function—not the label—determines regulatory reach, and Kitchen’s products performed the same risk-transfer role as traditional futures.

Judges also found that Kitchen’s platform matched buyers and sellers, held customer funds, and used leverage, satisfying the statutory definition of a futures commission merchant. The court affirmed the CFTC’s $1.2 million penalty and permanent trading ban, signaling that creative contract engineering will not shield operators from registration requirements.

In plain terms, the ruling tells crypto entrepreneurs that calling something “perpetual” does not create a regulatory free zone. Courts will look past marketing language to the substance of trading mechanics, and platforms that clear or custody client assets remain squarely inside CFTC territory.

The decision tightens CFTC authority at the exact moment when both agencies and exchanges are debating whether many crypto tokens are commodities or securities. By confirming that perpetual swaps are futures, the court reduces ambiguity for exchanges seeking CFTC registration, but it also raises compliance costs for DeFi protocols that mirror the same trading functions. Traders may see tighter leverage limits and fewer offshore venues as U.S. platforms face renewed enforcement pressure.

Expect more platforms to weigh CFTC registration against overseas relocation, with enforcement actions likely to focus on any product that lets users take leveraged directional bets on crypto prices.
DeFi Development Corp Adds 101,381 SOL to Its Corporate Treasury

DeFi Development Corp Adds 101,381 SOL to Corporate Treasury

DeFi Development Corp has purchased an additional 101,381 SOL, increasing its total Solana holdings by 4.24%. The transaction expands the company’s exposure to Solana and reinforces its strategy of using the cryptocurrency as a core corporate treasury asset.

Solana Holdings Increase

The latest acquisition adds 101,381 SOL to DeFi Development Corp’s balance sheet. The company is among the public firms pursuing a significant digital-asset treasury strategy centered on Solana, the blockchain’s native cryptocurrency.

SOL is used to pay transaction fees and support activity across the Solana network, including decentralized finance applications and other blockchain-based services.

Solana-Focused Treasury Strategy

DeFi Development Corp’s approach differs from the Bitcoin-focused reserve strategies adopted by some other public companies. Rather than primarily holding Bitcoin as a treasury asset, the company is building its reserves around SOL and its broader role within the Solana ecosystem.

The purchase extends one of the more substantial public-company commitments to Solana and increases the company’s direct exposure to movements in the SOL market.

Ninth Circuit Rules Bitcoin Derivatives Fall Under CFTC Jurisdiction

Wellermen Image CFTC WINS—CRYPTO TRADER LOSES IN NINTH CIRCUIT
The Ninth Circuit just handed the CFTC a clear win and crypto traders a warning shot. In U.S. Commodity Futures Trading Commission v. Crombie, the appeals court ruled that Bitcoin futures and options fall squarely under CFTC jurisdiction—even when those contracts never touch a registered exchange. The decision slams the door on the “it’s just crypto, so it’s unregulated” defense and sets precedent across the western United States.

James Devlin Crombie ran an unregistered Bitcoin options platform that let customers bet on price swings. The CFTC sued, arguing he was offering illegal commodity options. Crombie fought back, claiming Bitcoin wasn’t a commodity and that the CFTC had no authority. A district judge agreed with the agency; Crombie appealed. The Ninth Circuit panel didn’t buy his arguments. It held that the Commodity Exchange Act’s broad definition of “commodity” covers digital currencies when they’re used as the underlying asset for futures or options. Because Crombie’s platform involved off-exchange options on Bitcoin price movements, he needed to register—and he didn’t. The court affirmed the lower court’s injunction and penalties.

Crombie loses his platform and faces monetary sanctions. The CFTC gains an on-point appellate ruling that strengthens its hand against any unregistered crypto-derivatives shop operating in the Ninth Circuit’s footprint—California, Washington, Arizona, and beyond. Exchanges that list Bitcoin options or futures now have clearer guidance: follow CFTC rules or expect enforcement. Traders who use offshore or DeFi options platforms get a fresh reminder that “decentralized” doesn’t equal “unregulated” if U.S. customers can click in.

In plain terms, the ruling treats Bitcoin like any other commodity—oil, gold, wheat—when derivatives are involved. That means the same registration, anti-fraud, and disclosure rules apply. Platforms can’t hide behind the code; if U.S. users trade Bitcoin options without CFTC oversight, they’re breaking the law. The decision also signals that future tokens could face the same test: look at the economic function, not the branding.

For exchanges and DeFi protocols, the ruling raises the compliance bar and litigation risk. Market makers running options vaults or prediction markets on-chain will need legal opinions or CFTC registration to court U.S. liquidity. Traders may see tighter KYC gates, fewer offshore platforms willing to serve Americans, and a slow shift of volume onto regulated venues—where spreads can be wider but recourse exists. Stablecoin issuers aren’t directly touched, yet any yield-bearing or options-linked products built on their rails could trigger scrutiny.

The takeaway: treat every options or futures contract on a digital asset as a regulated instrument until the CFTC says otherwise—because the Ninth Circuit just did.

Court Forfeits 24 Crypto Wallets in IRS Tax Probe

Wellermen Image Court Orders Crypto Accounts Forfeited in IRS Tax Probe
A federal judge in Washington has ordered the forfeiture of twenty-four cryptocurrency accounts after the U.S. government proved the wallets held proceeds from tax evasion and money laundering. The ruling shows that anonymous digital wallets are no longer safe havens once investigators link them to tax crimes.

The case started when IRS agents traced Bitcoin and other tokens back to an individual who failed to report trading income and used multiple wallets to hide assets. Prosecutors filed a civil forfeiture complaint against the accounts, arguing the coins were either proceeds of tax fraud or tools used to conceal income. The account holder never appeared to contest the seizure, leaving the government’s evidence unchallenged. Judge Dabney L. Friedrich reviewed affidavits showing wallet addresses, blockchain records, and tax returns, then concluded the assets were forfeitable under federal law.

Because no one stepped forward to claim the coins, the court treated the accounts as abandoned and granted summary judgment for the United States. The decision wipes out any ownership interest the original holder might have asserted and transfers the tokens to government custody for liquidation. It also sets a precedent: when blockchain evidence is clear and an owner stays silent, courts will not hesitate to seize digital assets.

In plain terms, the ruling reminds holders that civil forfeiture can snatch crypto without a criminal conviction if the coins are tied to unpaid taxes or suspicious layering. The burden shifts to the owner to prove legitimate source of funds, and ignoring a forfeiture complaint is effectively a surrender.

For markets, the case signals that the IRS can reach anonymous wallets once fiat on-ramps or exchange records create a paper trail. Traders may feel added pressure to keep meticulous records, while decentralized exchanges and mixers could see fresh scrutiny as users weigh privacy against seizure risk. Stablecoin issuers and custodians should expect more subpoenas if tax investigators link their platforms to hidden income.

The message is blunt: if you cannot explain the origin of your coins to the IRS, the blockchain itself may become the evidence locker that empties your wallet.

SEC Wins Key Round as Binance Case Survives Dismissal, Tightens Grip on Crypto Exchanges

Wellermen Image SEC’s Binance Case Survives Key Dismissal Motion
The Securities and Exchange Commission just won the first round of a legal fight that could reshape how crypto exchanges operate in the United States. A federal judge refused to throw out most of the SEC’s claims against Binance and its U.S. platform, keeping the agency’s authority over unregistered trading platforms very much alive. The decision signals that crypto firms cannot simply structure their way around federal oversight by parking assets offshore.

The lawsuit began in June 2023 when the SEC accused Binance, its founder Changpeng Zhao, and the U.S.-facing Binance.US of selling unregistered securities, running an unlicensed exchange, and mishandling customer funds. Binance fought back with a motion to dismiss, arguing that the tokens it listed were not securities, that the SEC lacked jurisdiction over foreign activity, and that staking products were outside the agency’s reach. Judge Amy Berman Jackson spent months sifting through hundreds of pages of briefs before issuing a 91-page opinion that largely sided with the regulator.

On the central legal question—whether tokens and staking programs meet the Howey test for investment contracts—the court found the SEC had plausibly alleged facts to move forward. The judge agreed that several high-profile tokens could be considered securities when sold to U.S. investors, and she let stand claims that Binance.US operated without proper registration. She dismissed a handful of narrower counts tied to the foreign Binance.com platform’s direct dealings with American users, but the core allegations remain intact. The ruling hands the SEC a procedural victory while leaving the door open for Binance to contest the facts at trial.

In plain terms, the court is telling crypto exchanges that if they solicit U.S. customers—directly or through backdoors—they play by SEC rules. The decision does not declare every token a security, but it keeps the question alive and forces platforms to defend their listings one asset at a time. That uncertainty translates into compliance costs, legal risk, and a powerful incentive for exchanges to either register or restrict U.S. access.

For markets, the ruling strengthens the SEC’s hand in ongoing enforcement actions and weakens arguments that foreign exchanges can ignore American regulators. It also raises fresh doubts about staking programs and the legal status of major altcoins, keeping selling pressure on tokens named in the complaint. Traders now face a binary choice: price in more regulatory friction or rotate into assets and venues with clearer compliance postures.

The case is far from over, but the early scoreboard shows regulators still hold home-field advantage when U.S. investors are involved.

Bitwise Launches First Lighter ETP as Hyperliquid Rivalry Heats Up

Bitwise Launches First Lighter ETP as Competition Among Decentralized Derivatives Platforms Grows

Bitwise has launched its first exchange-traded product (ETP) linked to Lighter’s native LIT token, giving European investors brokerage access to the digital asset through a regulated investment product.

Product Expands Bitwise’s Decentralized Finance Offering

The new product adds exposure to Lighter, a decentralized derivatives platform, as Bitwise broadens its lineup of investment products tied to blockchain-based trading infrastructure.

By packaging exposure to LIT in an ETP, the product is designed to allow eligible European investors to gain access through traditional brokerage accounts rather than holding the token directly in a cryptocurrency wallet.

Lighter Enters Competitive Derivatives Market

Lighter operates in the decentralized derivatives sector, a market that also includes platforms such as Hyperliquid. These protocols seek to provide blockchain-based trading for leveraged financial products while reducing reliance on centralized intermediaries.

The launch comes as competition increases among decentralized exchanges offering derivatives and as asset managers develop new ways for investors to access tokens associated with emerging crypto platforms.

Delaware Court Dismisses $15M Crypto Startup Suit for Concealing Key Deal Details

Wellermen Image Court Slams Delaware Startup for Hiding Crypto Deal
Delaware’s Superior Court just threw out a $15 million lawsuit brought by a crypto startup and its founder against a venture partner, ruling that the plaintiffs concealed key financial details and ignored basic corporate rules. The decision sends a clear warning: in Delaware courts, crypto founders who play fast and loose with disclosure will not get a second chance at recovery.

The case began when Diamond Fortress Technologies and its CEO Charles Hatcher sued their former partner after a planned token sale and technology licensing deal collapsed. The plaintiffs claimed breach of contract, fraud, and tortious interference, alleging the partner had sabotaged the transaction and stolen their intellectual property. But the evidence showed the startup never properly authorized the deal under Delaware corporate law, failed to disclose material financial information during discovery, and tried to hide the fact that its founder had personally received undisclosed payments from the same partner.

After months of missed deadlines and contradictory statements, the court dismissed the entire action with prejudice. The judge found that Diamond Fortress had willfully violated discovery orders and that its claims were legally defective from the start because the company’s board never formally approved the underlying transaction. The ruling also rejected Hatcher’s attempt to sue in his personal capacity, noting that any alleged harm belonged to the corporation, not its shareholder.

In plain terms, the court told crypto entrepreneurs that Delaware’s legal system will not rescue them when they skip required corporate formalities or withhold documents in litigation. The decision reinforces that token sales, licensing deals, and joint ventures must follow the same corporate governance rules as any other Delaware company.

For the market, the ruling is a quiet but sharp signal: Delaware courts are becoming less tolerant of crypto players who treat disclosure as optional. Exchanges, DeFi projects, and token issuers relying on Delaware entities now face heightened litigation risk if internal approvals are sloppy or financials are obscured. The case also suggests that judges will not bend procedural rules to accommodate crypto’s “move fast” culture.

Traders and founders should treat this as a warning shot—Delaware courts will punish shortcuts, and the next founder who hides the books may not even get to trial.

Grayscale Win Forces SEC to Explain Why Futures Bitcoin ETFs Are Approved but Spot ETFs Are Blocked

Wellermen Image Court Slams SEC for Treating Bitcoin Funds Unequally
The D.C. Circuit just ordered the SEC to explain why it can green-light futures-based Bitcoin ETFs but still slam the door on spot Bitcoin ETFs. Grayscale won its challenge, and the agency must now defend — or reverse — its 2022 denial of the firm’s conversion of its GBTC trust into an exchange-traded product. The ruling lands like a regulatory earthquake because it exposes a glaring inconsistency at the heart of the SEC’s crypto policy.

Grayscale filed to convert its existing Bitcoin trust into an ETF in late 2021. The SEC rejected the application in June 2022, arguing that the spot market for Bitcoin was still vulnerable to fraud and manipulation. Grayscale sued, claiming the agency had already approved nearly identical Bitcoin futures products from other sponsors and could not rationally treat the two structures differently. The three-judge panel agreed, finding that the SEC never offered a “reasoned explanation” for why futures-based products somehow cured the same manipulation risks that it said doomed the spot version.

The court did not order the ETF approved; it simply vacated the denial and sent the matter back to the Commission for a fresh look. That means the agency must either craft a new, defensible rationale for keeping spot products out or treat Grayscale’s proposal the same as the futures ETFs already trading. Either path carries consequences: a new rationale risks fresh lawsuits, while approval would open the floodgates for other spot Bitcoin and possibly Ether products.

In plain English, the decision strips the SEC of its favorite excuse — that spot Bitcoin markets are uniquely dirty — unless it can prove the futures market somehow sanitizes the very same coins. If the Commission cannot draw a credible line between the two, its broader authority to gatekeep crypto listings shrinks.

The ruling tilts power toward exchanges and issuers who can now argue that once one Bitcoin product clears review, similar structures must follow. Traders will read this as higher odds of a spot ETF launch before year-end, boosting short-term sentiment and volumes in GBTC and related names. DeFi protocols that rely on Bitcoin collateral could see indirect liquidity gains if an ETF draws fresh institutional money on-chain.

The SEC still holds the pen, but the court just made it harder to keep writing “no” without a better story.

Seventh Circuit Expands CFTC’s Crypto Fraud Authority Beyond Futures

Wellermen Image COURT SLAMS DONELSON: CFTC WINS ON BROAD FRAUD AUTHORITY
The Seventh Circuit just handed the CFTC a decisive victory in its fraud case against James Donelson, ruling that the agency can police crypto-related schemes even when no futures contracts are involved. The decision expands the agency’s reach far beyond traditional commodity markets, and it sends a clear signal that digital-asset promoters will face the same anti-fraud rules as futures traders.

Donelson stood accused of running an unregistered bitcoin mining operation that promised outsized returns but never delivered. The CFTC sued him for fraud, but Donelson fought back, arguing the agency had no jurisdiction because his scheme did not involve futures or swaps—the CFTC’s classic turf. Lower courts rejected that defense, and last week the appeals panel unanimously agreed. The judges held that the Commodity Exchange Act’s anti-fraud provision, Section 6(c)(1), reaches any scheme that affects the price of a commodity in interstate commerce, regardless of whether futures are traded. In short, the court said the CFTC can police fraud wherever commodity prices are distorted, and bitcoin qualifies.

The ruling hands the CFTC a broader enforcement mandate and narrows the defense that crypto ventures have used to claim the agency has no power over spot-market schemes. Donelson loses his jurisdictional argument and faces the prospect of restitution, civil penalties, and a trading ban. Meanwhile, the agency gains a precedent that will make it easier to target unregistered offerings, misleading yield programs, and any platform that moves commodity prices without CFTC oversight.

In practical terms, the decision imports the same anti-fraud standards that govern futures markets into the broader crypto economy. Any digital token that can influence the price of bitcoin, ether, or other commodities now carries potential CFTC exposure, even if it never trades on a regulated exchange. Stablecoins, wrapped tokens, and liquidity-pool tokens are not automatically shielded simply because they sit outside the futures arena.

For exchanges and DeFi protocols, the ruling raises the compliance bar. Platforms can no longer assume that spot trading or decentralized structures place them outside federal oversight. Traders should expect more enforcement actions that allege price manipulation or false yield claims, and legal costs for token issuers will climb as they weigh registration, disclosures, and possible CFTC jurisdiction.

The message is simple: the CFTC just got a bigger net, and the crypto market is squarely inside it.

Peter Brandt Predicts Ethereum Could Hit $8,600 After Clearing $5,000

Peter Brandt Identifies $5,000 Ethereum Breakout Level in Path Toward $8,600

Veteran trader Peter Brandt has identified $5,000 as a key level for Ethereum (ETH), suggesting that a sustained move above that threshold could open the way toward a longer-term target near $8,600.

Ethereum Faces a Key Technical Threshold

Brandt shared a long-term Ethereum chart outlining a potential price progression. Under the scenario presented, ETH would first need to clear the $5,000 level before the market could support a move toward $8,600.

Ethereum is trading below that threshold, leaving a significant gap between its current level and the first milestone in Brandt’s outlook. The $5,000 mark is therefore likely to remain an important level for traders monitoring whether the projected pattern is developing.

Long-Term Projection Remains Conditional

Brandt’s forecast is based on technical chart analysis and is conditional on Ethereum breaking through the identified resistance. A failure to reclaim $5,000 could delay or invalidate the path toward the higher target.

The projection does not specify a timeline for either milestone. As with all chart-based forecasts, the scenario depends on market conditions, price momentum and Ethereum’s ability to sustain gains above key resistance levels.

Coinbase Win Forces SEC to Open Crypto Rulemaking, Court Says

Wellermen Image COINBASE WINS — COURT STRIPS SEC OF FORCED RULEMAKING POWER
The Third Circuit just handed Coinbase a decisive victory by vacating the SEC’s 2022 order refusing to write crypto-specific rules. The ruling says the Commission cannot simply tell an industry “no” without ever opening the rulemaking process the Administrative Procedure Act demands. For crypto markets, that single procedural decision just became a potential choke-point for the SEC’s entire enforcement-first strategy.

Coinbase petitioned the Commission in July 2022 asking for clarity on how existing securities laws should treat digital assets, staking rewards, and decentralized exchanges. The SEC rejected the petition without public comment or cost-benefit analysis, insisting it already had enough authority and guidance. Coinbase appealed, arguing the denial itself was arbitrary and capricious because the agency had never tested its theories in open rulemaking where the industry could weigh in. The three-judge panel agreed, finding the Commission’s blanket refusal violated the APA’s requirement that agencies give “adequate reasons” when they turn down a petition for rules.

The court did not order the SEC to write new regulations; it simply told the agency that if it wants to keep refusing, it must explain why existing statutes already cover staking and token trading in a manner clear enough for businesses to comply. That shifts the burden back onto the Commission to justify its enforcement-heavy approach rather than letting silence serve as policy.

In plain English, the ruling means the SEC can still sue crypto firms one by one, but it can no longer hide behind a closed door when the industry asks for a transparent rulebook. Regulated entities now have a judicially endorsed lever to force the agency into public debates about token classification and DeFi mechanics.

For markets, the decision injects fresh uncertainty into the SEC’s authority. Traders and exchanges betting on a swift enforcement wave may now price in prolonged procedural fights that could delay cases or blunt penalties. Stablecoin issuers and staking protocols gain negotiating room: if the Commission cannot articulate clear rules, litigation risk becomes two-way. Meanwhile, the CFTC’s lighter-touch lane for digital commodities looks comparatively attractive, potentially accelerating capital rotation into futures and derivatives markets where rulemaking is already underway.

Bottom line: the opinion turns the SEC’s favorite shortcut—enforce first, explain never—into a longer, more expensive road that traders will watch for signs of fatigue.

Binance Launches 24/7 USD/BRL FX Perpetuals for Crypto Traders

Binance Launches 24/7 USD/BRL Perpetual Contract

Binance Futures has launched a perpetual contract linked to the USD/BRL exchange rate, giving traders continuous synthetic exposure to the value of the US dollar against the Brazilian real through a crypto derivatives platform.

USD/BRL Opens Binance’s FX Perpetual Product Line

The USD/BRL contract is the first product in Binance’s new foreign-exchange perpetual offering. The instrument follows the perpetual-futures format widely used in crypto markets and is designed to trade continuously, including during periods when traditional foreign-exchange markets are closed.

Unlike a conventional spot foreign-exchange transaction, the contract does not involve the delivery or settlement of physical US dollars or Brazilian reals. Instead, it provides price exposure to the USD/BRL exchange rate through a derivative. Traders may also use leverage, subject to Binance’s applicable margin requirements and risk controls.

The product allows foreign-exchange exposure to be managed alongside cryptocurrency positions, including Bitcoin and Ether, within the same derivatives and collateral environment.

Additional FX Contracts Expected

Binance has indicated that more foreign-exchange contracts may be introduced in the future. However, the September 21 rollout began with USD/BRL and did not represent the simultaneous launch of a broad range of major currency pairs.

Crypto Platforms Expand Into Traditional Markets

The launch reflects the continued expansion of crypto derivatives venues into traditional financial markets. Exchanges have increasingly introduced products tied to equities, pre-IPO companies and other non-crypto assets through infrastructure that operates around the clock.

These products offer exposure to the price movements of traditional assets without replicating the settlement process of the underlying markets. In that sense, Binance’s USD/BRL contract represents the use of crypto-style perpetual derivatives as a framework for accessing a wider range of financial prices.

OKX Shield Offers Europeans Up to €500K Account-Takeover Protection

OKX Launches Discretionary Account-Takeover Reimbursement Program in Europe

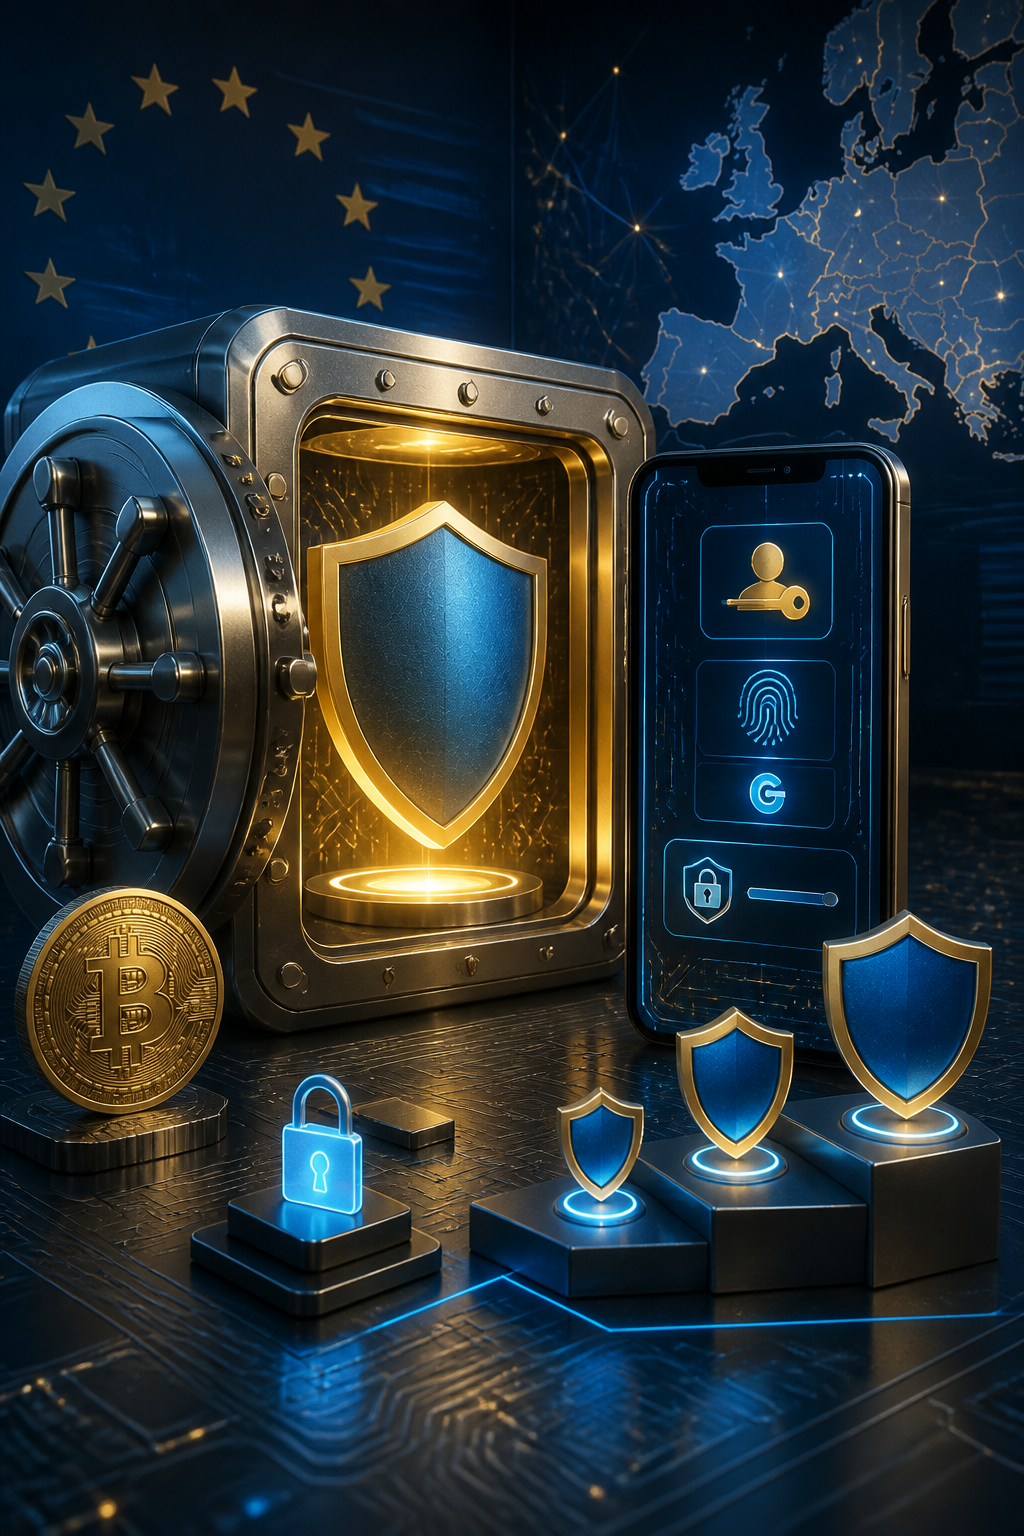
OKX has launched Shield in Europe, a voluntary program that may reimburse eligible users for certain losses resulting from third-party account takeovers. Protection limits range from up to €100,000 for standard users to €500,000 for customers in the VIP 4–6 tiers.

Eligibility Requires a Security Checklist

Users must complete a six-step security process to qualify for consideration under the program. The requirements include account-hardening measures such as passkeys, multi-factor authentication and withdrawal safeguards.

Once the required protections are in place, users may be considered for discretionary reimbursement if a qualifying third party gains control of their account and causes a covered loss. The program does not automatically guarantee compensation, and claims will be assessed under Shield’s terms.

Protection Limits Vary by User Tier

  • Standard users: Up to €100,000
  • VIP 1–3 users: Up to €250,000
  • VIP 4–6 users: Up to €500,000

The tiered structure links potential reimbursement amounts to OKX’s customer classification system. It also provides an additional incentive for users to activate stronger authentication and withdrawal controls.

Shield Is Not Insurance

OKX launched Shield in Europe on September 22 and has emphasized that the program is not an insurance policy, deposit-protection arrangement or statutory investor-compensation scheme.

Instead, Shield is a voluntary goodwill program under which reimbursement remains discretionary. The distinction is significant because the stated limits could otherwise be interpreted as regulated insurance coverage. OKX has not described Shield as a legally guaranteed protection product.

Security Measures Linked to Potential Reimbursement

Cryptocurrency exchanges have increasingly encouraged customers to use passkeys, multi-factor authentication and withdrawal restrictions to reduce the risk of unauthorized access. OKX’s program connects those measures to the possibility of financial reimbursement in qualifying cases.

The practical value of Shield will depend on how OKX evaluates claims and applies the program’s terms in individual account-takeover incidents. For European users, however, the initiative represents a more concrete effort to link account-security practices with a discretionary financial backstop.

**Bitcoin News: How BIX Makes Wallet-to-Wallet Crypto Usable Every Day**

Stablecoin Holders Still Face Friction When Converting Digital Dollars Into Spendable Cash

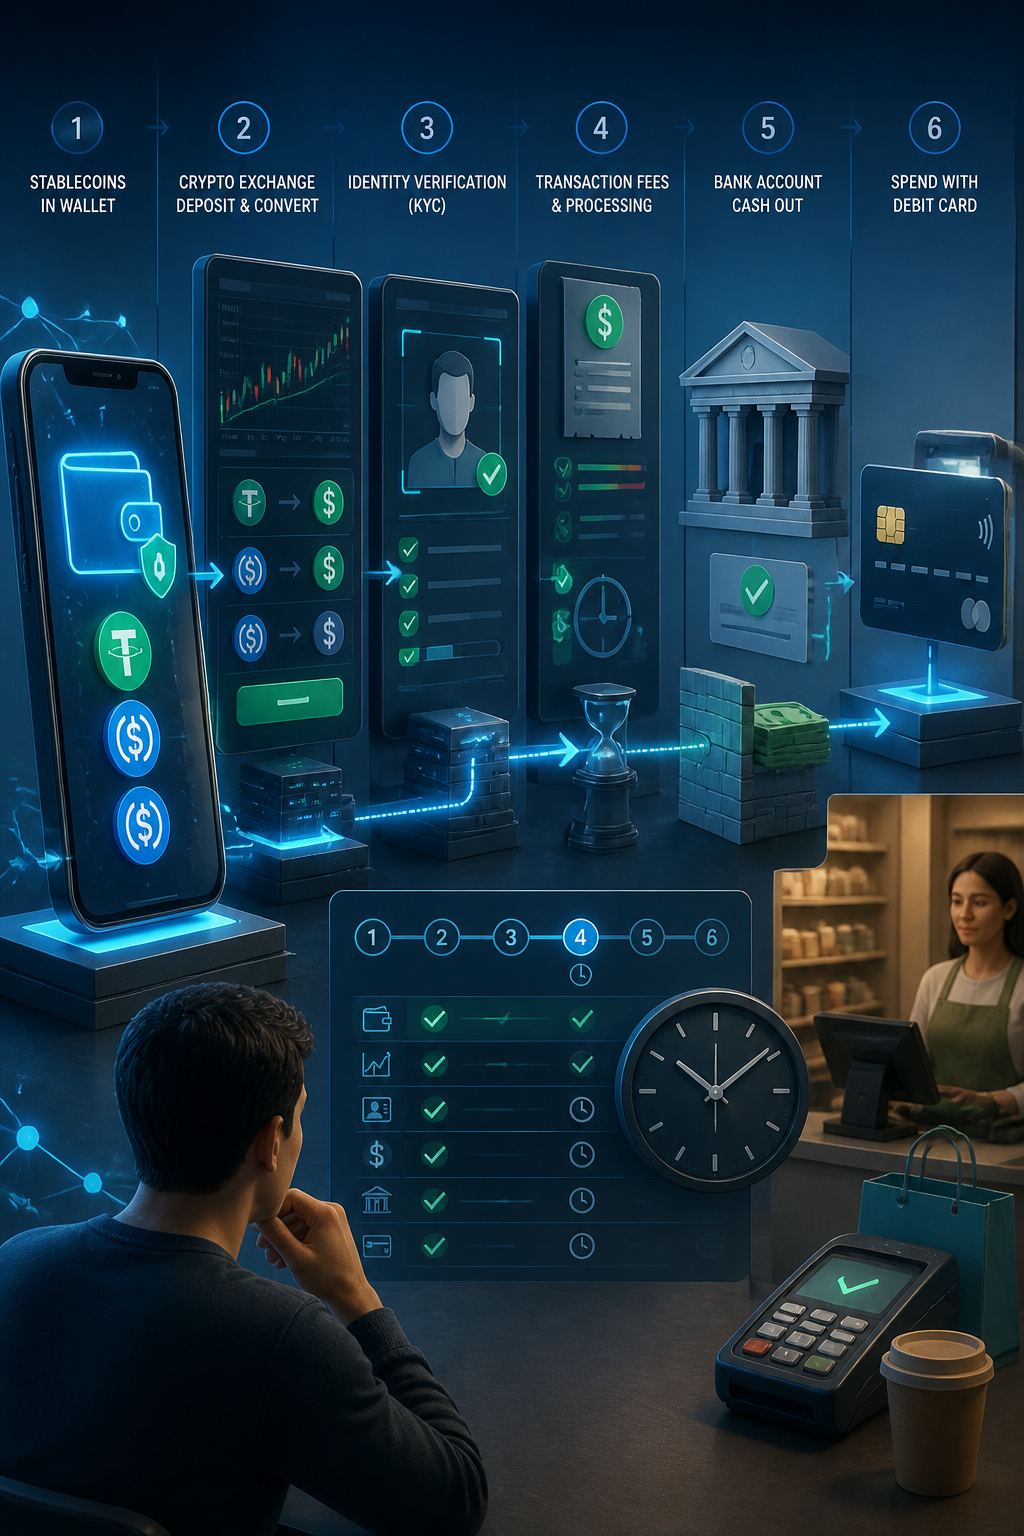
Stablecoins offer liquidity and dollar-based value within cryptocurrency applications, but using those funds for everyday purchases can still require several additional steps. Holders often need to move their tokens to an exchange, convert them into fiat currency, and withdraw the proceeds to a bank account before the money can be spent.

From On-Chain Balance to Bank Account

Although stablecoin balances are generally designed to maintain a value close to a fiat currency, they are not automatically accepted by most merchants. A user holding stablecoins in a wallet or trading application may therefore need to transfer the assets to a platform that supports fiat conversion.

The process can involve exchange transfers, identity checks, trading fees, withdrawal charges and banking delays. These requirements can reduce the convenience of holding digital dollars, particularly for users seeking immediate access to funds.

Payments Remain a Key Challenge

The gap between holding stablecoins and spending them at the point of sale remains one of the broader challenges facing crypto payments. Stablecoins can provide near-instant settlement on blockchain networks, but their practical usefulness depends on whether wallets, payment providers and merchants support direct transactions.

As the stablecoin market develops, access to simpler conversion and payment options will remain important for increasing everyday use. Until those systems become more widely available, many users will continue to rely on traditional exchanges and bank transfers to turn stablecoin balances into spendable money.

**Bitcoin News: PokerStars Opens Player Pool to Rival Brands—Why It Matters**

PokerStars Opens Network to External Operators as It Seeks to Expand Player Pool

PokerStars has launched a dedicated sales website inviting outside operators to join the PokerStars Network, a shared player pool that Flutter Entertainment has so far used primarily to connect its own poker brands.

Network Expansion Strategy

The initiative would allow third-party operators to access the network’s shared liquidity, potentially giving their customers access to a larger pool of players and tournaments. PokerStars is presenting the network as a platform for operators seeking to expand their poker offerings without building an independent player base.

Flutter has previously used the network to combine liquidity among its own brands. Opening it to external companies would represent a broader commercial strategy for the platform and could increase the number of players participating across connected poker rooms.

Competitive Pressure in Online Poker

The pitch comes as PokerStars trails GGPoker in traffic, according to the information accompanying the launch. The competitive gap highlights the pressure on established poker operators to attract new players and improve the scale of their games.

PokerStars’ sales materials cite a sister company as the network’s principal partner success story. The company has not, based on the available information, identified a broad roster of independent operators that have already joined the network.

Potential Impact

Adding external brands could increase player liquidity and support larger games across the PokerStars ecosystem. However, the success of the strategy will depend on whether independent operators are willing to share customers and align with the network’s commercial and operational requirements.

×