NY Appellate Court Narrows Arbitration in Crypto Margin Call Case (Regal Commodities v. Tauber)

Wellermen Image Regal Commodities v Tauber: Court Hands Commodities Trader a Win

New York’s Appellate Division just flipped the script on a commodities-trading dispute, ruling that Regal Commodities can’t be forced into arbitration over a $2 million margin call gone wrong. The decision reins in how far mandatory-arbitration clauses can reach when brokerage agreements are silent on digital-asset disputes, giving traders and exchanges a clearer line in the sand.

The case began when Regal’s customer, David Tauber, refused to meet a margin call after bitcoin-linked futures cratered in May 2022. Regal liquidated Tauber’s positions and sued for the shortfall in New York state court. Tauber moved to compel arbitration under an industry-standard clause buried in the customer agreement. Regal argued the clause only covered “commodities” as defined when the contract was signed—well before bitcoin futures existed—and that crypto margin disputes fell outside its scope. The trial court sided with Tauber and stayed the lawsuit; Regal appealed.

On March 27 the Appellate Division reversed. Writing for a unanimous bench, Justice Dillon held that arbitration clauses must be read strictly against the drafter when new asset classes emerge post-contract. Because the agreement never mentioned digital assets or referenced CFTC jurisdiction over bitcoin, the court found no “clear and unmistakable” intent to arbitrate crypto-related margin calls. The lawsuit can now proceed in open court, exposing brokerage houses to greater litigation risk and discovery.

In plain English, New York just told the industry that silence in an old contract won’t be stretched to cover new markets. If your customer agreement doesn’t explicitly list bitcoin, ether, or their derivatives, you may have to litigate rather than arbitrate when margin calls go unpaid.

The ruling narrows the practical reach of mandatory arbitration for crypto margin desks and could push exchanges to redraft onboarding docs before the next volatility spike. It also signals that state courts won’t automatically cede crypto disputes to CFTC-supervised forums unless the paperwork is crystal-clear. Meanwhile, traders gain leverage: the threat of public litigation—and the attendant reputational risk—may make brokers more willing to negotiate shortfalls instead of liquidating first and asking questions later.

Bottom line: expect tighter contract language, louder legal departments, and a fresh round of “crypto isn’t just another commodity” arguments the next time margin meets a court filing.

Seventh Circuit Blocks CFTC From Forcing Crypto Docs Without Subpoena

Wellermen Image COURT HANDS CFTC FIRST MAJOR CRYPTO-ERA SETBACK
The Seventh Circuit just blocked the CFTC from forcing Kraft to hand over documents without a proper subpoena, dealing the agency its first real procedural loss since it began treating crypto as a commodity. The ruling matters because the CFTC’s aggressive enforcement style is suddenly on notice: it cannot shortcut due process even when markets are moving fast.

Kraft and its affiliate Mondelēz asked the appeals court to stop a district judge’s order that would have let the CFTC inspect internal trading records without first issuing a formal subpoena. The companies argued the CFTC was trying to bypass the Commodity Exchange Act’s requirement that traders receive notice and an opportunity to contest the request. The CFTC countered that its broad statutory power to “inspect” should let it move quickly when it suspects manipulation in futures markets. In a rare writ-of-mandamus win, the Seventh Circuit agreed with Kraft: the CFTC must follow statutory procedure or show why an emergency justifies skipping it.

Judges ruled the agency had not demonstrated any urgency that would excuse it from normal process, and therefore the lower court’s order was an abuse of discretion. Kraft and Mondelēz keep their documents for now; the CFTC can still seek them, but only through a subpoena it must defend if challenged. Nothing in the opinion limits the CFTC’s ultimate enforcement reach; it simply insists the agency color inside the lines drawn by Congress.

In plain English, the decision reminds the CFTC that even when policing fast-moving digital-asset markets, it cannot invent shortcuts. Future targets—exchanges, DeFi protocols, or large traders—now have a precedent to slow-walk informal CFTC demands and force the agency into court before surrendering records.

For crypto markets, the ruling tilts the immediate balance toward targets rather than the regulator. The CFTC’s commodity authority over Bitcoin, Ether, and perpetual futures is untouched, but its reputation for swift, low-friction sweeps takes a hit. Exchanges and market makers gain negotiating leverage when the CFTC comes knocking; DeFi projects may cite the case when asked to turn over smart-contract data without formal process. Stablecoin issuers and token sponsors see no change in classification risk, but they do see a slightly higher procedural bar before the agency can rifle through their books.

Expect defense counsel to wave this opinion at the next CFTC investigator who shows up with a document demand and no subpoena; whether the agency adapts or Congress later hands it new powers will shape the next round of crypto enforcement.

Crypto Class Actions Consolidated in Illinois MDL, Signaling Nationwide Shift

Wellermen Image COURT THROWS COLD WATER ON CRYPTO CLASS ACTIONS
Three separate crypto investor suits just got pulled into one courtroom, and the decision could reshape how class actions against digital-asset platforms are litigated across the country. The Judicial Panel on Multidistrict Litigation ruled that all three cases—Greene in Chicago, plus two others in California and Pennsylvania—should move to the Northern District of Illinois. The move signals that courts are tired of piecemeal litigation in a market where every exchange, token, and DeFi protocol touches users nationwide.

The trigger was simple geography and overlapping claims. Each complaint alleged that the same handful of tokens were unregistered securities and that exchanges listing them violated federal law. Plaintiffs wanted their cases handled together to avoid duplicative discovery and conflicting rulings; defendants resisted, arguing that local rules and juries should decide local investors’ fates. The Panel cut through that noise, finding common questions of fact on token classification, exchange conduct, and the reach of SEC authority.

Judges ruled in favor of consolidation, handing the gavel to Chicago. Plaintiffs gain efficiency and leverage; defendants lose the chance to play courts against each other and now face a single discovery dragnet. The Northern District of Illinois has already handled high-profile crypto matters, so institutional knowledge tilts toward plaintiffs who can cite prior orders on staking rewards and token “investment contracts.”

In plain terms, the decision lowers the cost of suing crypto platforms and raises the cost of defending them. If the cases survive motions to dismiss, one precedent could bind exchanges from coast to coast.

Expect plaintiffs’ firms to file tag-along actions and watch the SEC’s enforcement shadow lengthen. Exchanges that list borderline tokens now carry multidistrict discovery risk, not just single-court exposure. Stablecoin issuers and DeFi protocols should read the map: Chicago is now the place where the next wave of “Howey” arguments will be stress-tested.

Traders betting on regulatory clarity just saw the venue map tilt against them.

White House: Crypto Market Structure Awaits Post-Election Clarity Act Surge

White House and Treasury Say Regulatory Agencies Must Now Advance Crypto Bill Work

White House and U.S. Treasury officials have indicated that responsibility for advancing the legislation now rests with federal regulators, despite some expectations that Congress could revisit the measure during its lame-duck session.

Regulators Take Center Stage

The officials’ position suggests that agencies will lead the next phase of work on the bill while lawmakers’ prospects for renewed action remain uncertain. No details were provided on the bill’s timeline or the regulatory steps under consideration.

Fifth Circuit Narrows SEC Authority, Demands Howey Proof Before Targeting Crypto Tokens

Wellermen Image Court Deals Fresh Blow to SEC in Crypto Case
The Fifth Circuit has ruled that the SEC cannot punish crypto platforms for selling digital assets without first proving those assets are securities. The decision hands exchanges and DeFi projects a powerful new shield while clipping the agency’s enforcement reach.

The case began when the SEC sued a trading platform for offering unregistered digital tokens. The agency argued that the mere act of listing tokens on an exchange was enough to trigger liability. The platform fought back, claiming the SEC had skipped the most basic legal step: proving the tokens themselves qualified as securities under federal law. The Fifth Circuit agreed. Judges ruled that the SEC must first establish that each token meets the Howey test before it can demand registration or seek penalties. Without that proof, the agency’s case collapses.

The ruling forces the SEC to do more homework before swinging its enforcement hammer. Platforms no longer face automatic liability just for hosting tokens; regulators must now build a factual record showing each asset is an investment contract. This raises the bar for enforcement actions and gives exchanges breathing room to argue that many tokens are commodities or utilities rather than securities.

For markets, the decision shifts power away from blanket agency authority toward case-by-case proof. It slows the SEC’s ability to label entire exchanges as rogue operations and pushes disputes into longer, fact-intensive trials. Stablecoin issuers and DeFi protocols gain leverage to claim their products fall outside securities law, while traders may see reduced delisting pressure on marginal tokens. CFTC oversight could grow as the SEC’s reach narrows.

The SEC’s once-feared enforcement shortcut now requires real evidence, and platforms that prepare that defense will hold the stronger hand.

Ninth Circuit Finds Monex Leveraged Metal Contracts Are Futures, Expanding CFTC Authority

Wellermen Image Court Hands CFTC Rare Win Over Monex in Ninth Circuit Ruling
The Ninth Circuit reversed a district court and ruled that Monex’s leveraged precious-metals contracts are “commodity contracts for future delivery,” giving the Commodity Futures Trading Commission fresh enforcement muscle over retail crypto and commodity platforms. The decision is the first appellate word on how far the CFTC’s anti-fraud authority reaches when platforms offer leveraged crypto or metals exposure without exchange registration.

The dispute began when the CFTC sued Monex in 2017, accusing the Newport Beach dealer of running an illegal off-exchange retail commodity operation that defrauded customers of more than $290 million through hidden mark-ups and margin calls. A district judge dismissed the case, holding that Monex’s contracts were not futures because customers took “actual delivery” of metal stored in depositories. The CFTC appealed, arguing that Monex’s model—where investors never controlled the metal and could only close out by selling back to Monex—was the functional equivalent of a futures contract.

A three-judge panel agreed. Writing for the court, Judge Jay Bybee held that the phrase “actual delivery” requires more than book-entry credits; the buyer must be able to take possession, remove the commodity, or direct its transfer to a third-party depository within 28 days. Because Monex retained exclusive control of the vaults and never relinquished dominion, the transactions remained within the CFTC’s jurisdiction. The panel reinstated the agency’s claims under CEA Sections 6(c)(1) and 9(a)(2) and remanded for trial.

In plain English, the ruling lowers the bar for the CFTC to police any platform that lets retail customers buy crypto or commodities on margin yet keeps the underlying asset locked in the platform’s system. Exchanges and DeFi protocols that promise leveraged exposure without handing over wallets or warehouse receipts now face the same statutory exposure Monex could not escape.

The decision tilts authority toward the CFTC at the expense of platforms that hoped the “actual delivery” loophole would keep them outside federal oversight. Stablecoin issuers and margin-trading apps that park customer assets in omnibus wallets or cold-storage schemes should expect subpoenas, not safe-harbor arguments. Traders gain a measure of protection against fraud, but they also inherit the compliance costs and potential trading halts that tighter oversight will bring.

Exchanges betting that courts would read “actual delivery” loosely just learned the cost of that wager; the next move belongs to the CFTC.

Court Upholds Broad CFTC Authority to Probe Spot Crypto Manipulation

Wellermen Image CFTC WINS AS COURT UPHOLDS SWEEPING ENFORCEMENT POWER
A federal appeals court just gave the Commodity Futures Trading Commission its sharpest weapon yet: the right to punish crypto traders for “manipulative or deceptive” acts even when no futures contract is involved. Trevor Kitchen, a small-time trader, tried to overturn a $100,000 fine and lifetime trading ban, but the D.C. Circuit ruled that the CFTC can reach beyond exchange-traded instruments into the spot-crypto market whenever it smells fraud. The decision rewrites the battle lines between a regulator that wants more territory and an industry that thought spot trading was off-limits.

Kitchen’s trouble began in 2021 when he allegedly spoofed large orders on the spot Bitcoin market to move prices, then reversed them seconds later. The CFTC fined him under its anti-fraud authority, claiming the 2010 Dodd-Frank Act gave it power over any “contract of sale” of a commodity. Kitchen argued the agency was stretching the statute beyond futures and swaps; he said Congress never gave the CFTC a roving license to police every crypto trade. The three-judge panel disagreed, holding that the plain words “contract of sale” include one-off, over-the-counter deals in digital assets.

Judges Katsas, Rao, and Walker split on how far the ruling reaches. The majority said the CFTC can now target spoofing, wash trading, and pump-and-dump schemes wherever crypto changes hands, whether on Coinbase or an unregulated offshore venue. A concurring opinion warned that this could swallow the entire cash market, but still voted to affirm because Kitchen’s conduct looked like classic fraud. The ruling is final unless Kitchen persuades the Supreme Court to intervene, a long shot.

In plain terms, the CFTC just won the jurisdictional turf war it has waged since 2015. Spot crypto is no longer a regulatory no-man’s-land; the agency can now treat Bitcoin the same way it treats crude oil futures when it smells manipulation. That means every exchange, liquidity provider, and high-frequency trader in digital assets must assume the CFTC is watching.

For markets, the decision tilts the playing field toward compliance and away from gray-area tactics. Offshore platforms lose a key selling point—lack of U.S. oversight—while U.S.-facing exchanges gain a compliance moat that could squeeze smaller competitors. Stablecoins stay in limbo; the court did not touch them, but the same logic could let the CFTC pursue spoofing in USDT pairs. DeFi protocols remain exposed if their front-end code is deemed to facilitate manipulative trades. Traders who rely on rapid order placement and cancellation will either slow down or move offshore, shifting volume and liquidity.

The CFTC now has the legal runway to treat every crypto wallet like a trading desk—act accordingly or prepare for the next subpoena.

Bitcoin Whale Bets $3.17M on Rally—Could Lose Big at $100K

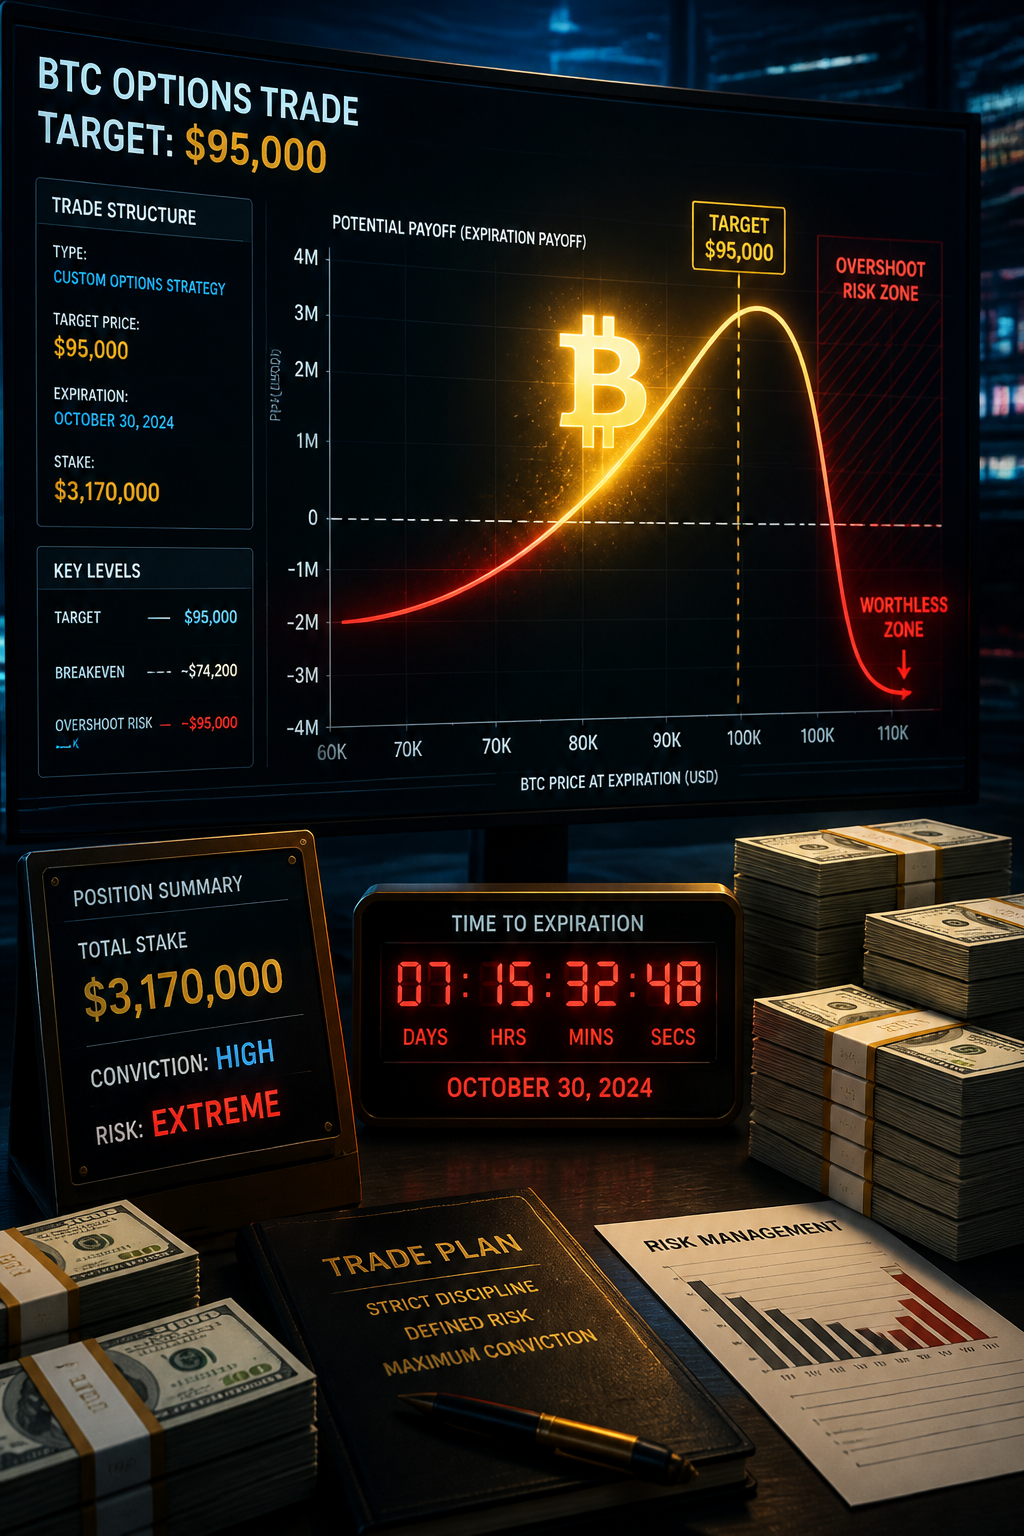
Bitcoin Options Trader Puts $3.17 Million Behind a $95,000 October Target

A bitcoin options trader has committed $3.17 million upfront to a position tied to bitcoin reaching $95,000 by October 30. However, a stronger-than-expected rally could leave the trade with no payout at expiry, creating an unusual risk profile for a position linked to higher prices.

A Multimillion-Dollar Position

The trade is structured around a specific bitcoin price target rather than a broad bullish outlook. The trader is effectively positioning for bitcoin to reach $95,000 by the October 30 expiration date.

The $3.17 million payment represents the upfront cost of the position. Its final value will depend on bitcoin’s price at expiry and the precise terms of the options contract.

Why a Larger Rally Could Hurt the Trade

Although the position is associated with a rise in bitcoin’s price, an advance beyond the targeted level could work against the trader. If bitcoin moves too far above the strike or settlement range, the position could lose its expected payout and potentially expire worthless.

This outcome highlights how options differ from straightforward bitcoin holdings. Options are time-limited contracts whose value depends on factors including the underlying asset’s price, the strike price, volatility and the expiration date. A trader can correctly anticipate a move higher and still lose money if the market overshoots the level built into the strategy.

Bitcoin’s $100,000 Milestone

Bitcoin’s potential move toward $100,000 has become a key focus for derivatives traders. The reported position, however, is centered on a narrower $95,000 target and a fixed expiration date, making the trade’s outcome particularly sensitive to the price at settlement.

Unless bitcoin finishes within the range required by the contract on October 30, the trader could lose some or all of the initial $3.17 million outlay.

Ninth Circuit Rules Bitcoin Derivatives Are Under CFTC Jurisdiction

Wellermen Image CFTC Wins Ninth Circuit Crypto Ponzi Ruling
The Ninth Circuit just slammed the door on James Crombie’s appeal, upholding a $1.1 million CFTC penalty and permanent trading ban for running a bitcoin futures fraud. The unanimous panel ruled that unregistered commodity pool operators who peddle crypto-linked contracts can’t hide behind “decentralized” jargon when their pitch sheets promise guaranteed 15 percent monthly returns. In three brisk pages the court confirmed that the Commodity Exchange Act still reaches virtual currency derivatives—even if the underlying code runs on a blockchain.

Crombie’s scheme began in 2011 when he solicited $600,000 from 60 investors for a “bitcoin trading pool” that never existed. He told clients their money would be held in segregated accounts and hedged with CME bitcoin futures; in reality he spent the cash on rent, car payments, and more bitcoin. After the CFTC sued in 2013, a district judge in Oakland ordered restitution and banned Crombie from futures markets. On appeal he argued the CFTC lacked jurisdiction because bitcoin is not a “commodity.” The Ninth Circuit panel rejected that claim in one sentence, citing the statute’s broad definition that covers “all services, rights, and interests in which contracts for future delivery are presently or in the future dealt in.”

The ruling hands the CFTC a precedent that applies equally to DeFi yield aggregators, options desks, and any platform offering crypto-linked derivatives. Because the court treated bitcoin as just another deliverable commodity, exchanges that list perpetual swaps or tokenized index products now operate under the same registration and anti-fraud rules that govern oil futures. Stablecoin issuers who embed leverage or yield mechanics could face similar exposure if their products are marketed to U.S. persons. Traders who once counted on regulatory gaps around “software” or “protocols” will now price in higher compliance costs and the risk of enforcement actions that can freeze assets held on centralized exchanges.

The decision also tightens the noose around unregistered commodity pool operators who market to retail through Telegram channels or Discord servers; those operators must either register or shut down, or risk personal liability that survives bankruptcy. Meanwhile, well-capitalized trading desks gain a moat: CFTC oversight weeds out fly-by-night competitors and gives institutional allocators clearer custody and audit standards. Volatility may spike in the short term as smaller platforms delist margin products, but long-term the ruling should compress risk premia attached to outright prohibition.

Bottom line: Bitcoin derivatives are now plainly under CFTC jurisdiction, and anyone promising crypto returns without registration is playing against a regulator that finally has the map.

IRS Can Seize 24 Crypto Wallets, DC Court Rules

Wellermen Image IRS STRIKES CRYPTO WALLETS IN NEW SEIZURE RULING
The U.S. District Court for the District of Columbia has ruled that the IRS can seize twenty-four cryptocurrency accounts tied to an alleged tax-evasion scheme, setting a clear precedent that digital assets are fair game for federal forfeiture. The decision matters because it shows how quickly the government can move from investigation to asset capture when wallets are linked to unreported income.

The case began when IRS agents traced Bitcoin and other tokens flowing from dark-web marketplaces into anonymous wallets. Prosecutors claimed the accounts belonged to individuals who never filed returns or paid taxes on trading gains. Rather than chasing individual owners across borders, the government filed an in-rem action against the wallets themselves, treating the cryptocurrency as the defendant. Defense counsel argued that without identifying the real people behind the keys, the court lacked jurisdiction and due-process safeguards. The judges rejected that view, holding that the presence of the digital assets inside U.S.-controlled exchanges or accessible via U.S. internet infrastructure was enough to give the court power over the property.

The ruling hands an immediate win to the IRS and signals a loss for privacy-focused users who assumed non-custodial wallets were beyond reach. Practically, exchanges and on-ramps must now decide whether to freeze or flag similar addresses without waiting for criminal indictments. Judges emphasized that the government only has to show probable cause that the assets are traceable to tax violations; it does not need a conviction first.

In plain terms, the court said digital coins sitting in code are still property that can be forfeited if prosecutors connect the dots to illegal income. That lowers the barrier for future IRS seizures and raises the stakes for anyone parking large, unexplained gains in crypto.

The decision expands IRS and Treasury reach without touching the SEC’s jurisdiction, yet it tightens the net around exchanges that must now treat IRS subpoenas as seriously as they treat CFTC or SEC orders. Decentralized protocols remain harder to touch directly, but any trader who moves coins onto a compliant platform risks retroactive scrutiny. Stablecoin issuers and DeFi front-ends that log IP addresses or KYC data face fresh pressure to build compliance dashboards or risk becoming the government’s easiest collection point.

Traders who treat anonymity as an absolute shield may soon find that the safest legal strategy is documented compliance, not creative wallet shuffling.

Judge Denies SEC’s Fast-Track Injunction in Binance Case

Wellermen Image SEC Suffers Procedural Blow in Binance Case
A federal judge in Washington just refused the SEC’s request to fast-track its lawsuit against Binance, forcing regulators to litigate on a slower timetable while the crypto exchange keeps operating. The decision hands Binance a tactical win and signals that courts are unwilling to let the SEC bulldoze its way through high-stakes enforcement actions without the usual procedural safeguards.

The Commission filed suit last summer alleging that Binance’s U.S. arm and its global parent sold unregistered securities, commingled customer funds, and operated an unlicensed exchange. Binance immediately moved to dismiss, arguing that most tokens on its platform are not securities and that the SEC lacks jurisdiction over its offshore operations. Rather than wait for the motions to be decided, the SEC asked Judge Amy Berman Jackson to issue an “extraordinary” preliminary injunction that would freeze assets, bar trading in 12 tokens, and impose a compliance monitor. The court said no.

Judge Jackson ruled that the SEC had not shown a likelihood of irreparable harm or that the public interest demanded emergency relief. She noted that Binance.US still holds customer assets in bankruptcy-remote accounts, that the exchange voluntarily stopped U.S. dollar trading, and that the SEC waited years before suing. The judge also expressed skepticism that a rushed injunction would serve investors better than a full trial on the merits. With the preliminary-injunction motion denied, the case now proceeds at normal speed, starting with the pending motions to dismiss.

The ruling underscores that the SEC cannot bypass normal civil-procedure rules simply because digital assets are involved. It also puts pressure on the agency to refine its legal theory before the court decides whether tokens like BNB or Solana are investment contracts. The decision does not resolve the underlying securities question, but it does make clear that judges will scrutinize the SEC’s requested remedies as closely as its legal claims.

For crypto markets the message is immediate: exchanges and DeFi protocols gain breathing room to argue their cases without facing sudden asset freezes or trading halts. The ruling raises the bar for emergency relief, lowers the odds of a quick settlement driven by litigation risk, and may embolden other platforms to push back harder against enforcement actions. Stablecoin issuers and token projects now have more time to shore up disclosures and registration plans before any final classification ruling.

Expect more litigation and less capitulation—until the next court decides otherwise.

Russia’s Largest Exchange Lists XRP Perpetuals—Here’s the Catch

Moscow Exchange Lists XRP Perpetual Futures for Qualified Investors

Moscow Exchange began trading perpetual futures linked to XRP on Sept. 22, adding the token to a derivatives lineup that already includes bitcoin, ether, Solana, and Tron. The contracts are available only to qualified investors.

Five Perpetual Contracts Begin Trading

Russia’s largest exchange listed five cash-settled perpetual futures contracts under the following symbols:

  • BTCUSDF — bitcoin
  • ETHUSDF — ether
  • SOLUSDF — Solana
  • XRPUSDF — XRP
  • TRXUSDF — Tron

Unlike traditional futures, perpetual contracts do not have a fixed expiration date. The contracts are settled in cash and track the performance of their respective cryptocurrency indexes, allowing participants to gain price exposure without holding the underlying assets directly.

Access Limited to Qualified Investors

Despite the listing, retail traders cannot access the new contracts. Moscow Exchange has restricted trading to qualified investors, limiting participation to clients who meet applicable experience, asset, or other eligibility requirements.

The restriction means the XRP contract’s availability on the exchange does not represent a broad opening of cryptocurrency derivatives trading to the Russian retail market. Instead, it provides an additional regulated-market instrument for eligible participants seeking exposure to XRP and other digital assets.

XRP Joins Major Crypto Assets on the Exchange

The listing places XRP alongside several of the largest cryptocurrencies by market presence on Moscow Exchange’s derivatives platform. The addition expands the exchange’s range of cash-settled cryptocurrency products while maintaining access controls for the market.

Delaware Court Rules Crypto Deal Must Be Signed—Handshake Agreements Aren’t Enforceable

Wellermen Image COURT SLAMS DELAWARE TECH FIRM IN CRYPTO DEAL GONE WRONG

Delaware’s Superior Court just handed Diamond Fortress Technologies and its founder Charles Hatcher II a crushing defeat in their lawsuit against a crypto exchange partner. The ruling underscores how courts are increasingly unwilling to protect crypto firms from their own sloppy contracts.

The case started when Diamond Fortress, a Delaware company building blockchain-based security tech, sued an exchange operator after a planned token listing and revenue-sharing deal collapsed. Hatcher alleged breach of contract and fraud, claiming the exchange promised to list their token and share trading fees but backed out once market conditions shifted. The exchange countered that no binding agreement ever existed—just preliminary talks.

The court sided with the exchange, ruling that the parties never formed an enforceable contract because key terms like fee splits and token allocation remained unsettled. Judges found the discussions amounted to nothing more than an agreement to agree, which Delaware law does not enforce. The fraud claim also failed because the exchange’s statements were deemed non-actionable business puffery rather than false promises.

In plain English, the decision means crypto entrepreneurs cannot rely on handshake deals or vague emails to lock in exchange partnerships. Courts will demand clear, signed contracts with definite price, quantity, and performance terms before stepping in to enforce crypto business arrangements.

For markets, the ruling tightens the screws on informal exchange listings and DeFi revenue-share pacts. It signals that the SEC and CFTC may gain indirect leverage if exchanges demand iron-clad contracts, reducing the gray-area flexibility that currently lets smaller tokens reach liquidity. Traders should expect exchanges to adopt stricter onboarding standards, raising barriers for new projects and favoring established issuers with polished legal teams.

Bottom line: if your token deal lives in Slack messages instead of signed docs, the courts just told you it’s not real money.

DC Circuit Orders SEC to Reconsider Grayscale’s Spot-Bitcoin ETF Denial

Wellermen Image Court Hands Grayscale a Rare Win Against SEC
The D.C. Circuit just ordered the Securities and Exchange Commission to reconsider its 2022 denial of Grayscale’s spot-Bitcoin ETF application. By ruling that the agency treated identical products inconsistently, the court exposed the SEC’s reasoning as arbitrary and capricious, giving the first credible crack in the agency’s wall against spot-crypto funds.

Grayscale had asked the Commission to convert its long-running Bitcoin Investment Trust into an exchange-traded product that would let retail investors trade actual bitcoin shares on NYSE Arca. The SEC rejected the proposal, arguing that the exchange had failed to demonstrate how it would detect and deter fraud and manipulation. Grayscale appealed, pointing out that the same exchange already lists futures-based bitcoin ETFs that the Commission had approved months earlier. The three-judge panel agreed, holding that the SEC could not demand stricter surveillance standards for spot products while accepting weaker ones for futures without explanation.

The ruling does not force the SEC to approve the ETF; instead, the court remanded the matter so the agency must either provide a coherent reason for treating spot and futures products differently or drop its objection. Grayscale wins a procedural victory that forces regulators back to the drawing board, while the SEC loses the presumption that its prior reasoning will survive judicial scrutiny. Exchanges and issuers now have a template for challenging similar rejections.

In plain English, the court told the SEC it cannot keep moving the goalposts. If futures ETFs are safe enough for retail money, the agency must explain why holding actual bitcoin is riskier, or it must let both structures compete. That single requirement chips away at the Commission’s discretionary power and shifts momentum toward products that give investors direct exposure rather than synthetic futures rolls.

For markets, the decision signals that the SEC’s blanket resistance to spot bitcoin is no longer untouchable. A successful Grayscale relaunch could suck liquidity out of the futures complex, pressure the CME’s dominance, and force competing issuers to file fresh applications. Stablecoin issuers and DeFi protocols should watch closely: if a regulated, on-chain asset can clear the manipulation test, arguments against tokenized Treasuries or other real-world-asset products weaken. Traders will price in higher odds of eventual spot approval, but volatility will remain elevated until the SEC issues a new order.

The window for approval just cracked open—how wide it swings depends on whether the agency doubles down or finally writes rules that treat like products alike.

Seventh Circuit Expands CFTC Authority Over Leveraged Crypto Investments

Wellermen Image Court Hands CFTC Broad Power Over Crypto “Investments”

The Seventh Circuit just told the CFTC it can police almost anything sold as a futures contract—even when the product is a cryptocurrency and no exchange ever lists it. In a 3-0 decision, the court upheld a $1.7 million judgment against James Donelson for running a Ponzi-style scheme that promised customers “off-exchange retail commodity transactions” in digital assets. The ruling matters because it widens the agency’s reach at the exact moment Washington is still fighting over whether the CFTC or the SEC should regulate crypto.

Donelson had pitched investors a platform that let them trade Bitcoin, Ethereum and Litecoin on 100-times leverage without ever taking delivery of the coins. When the CFTC sued, Donelson argued the trades were not “commodity transactions” under the CEA because no actual futures contracts existed on any registered exchange. The district court disagreed, found Donelson had defrauded roughly 600 customers, and ordered restitution plus a lifetime trading ban. On appeal, Donelson claimed the CFTC lacked jurisdiction over spot-crypto markets and that his users were simply buying the tokens outright.

Writing for the panel, Judge Michael Scudder ruled that the CEA’s retail-commodity provision covers any “agreement, contract or transaction” that is margined or leveraged and involves a non-financial commodity, regardless of whether it is called a future. The court held that Donelson’s scheme met that test because customers put up a fraction of the notional value and settled in cash based on price moves—exactly the economic profile of a futures contract. The judges rejected Donelson’s delivery argument, noting that actual delivery never occurred and that the platform’s terms made physical settlement impossible.

The decision tightens the vise on any platform that offers U.S. customers crypto exposure on margin or leverage without CFTC registration. It also signals that courts will look past labels and examine the economic substance of a product—raising compliance costs for offshore exchanges and DeFi protocols that serve American traders. Stablecoins used as margin may now draw extra scrutiny, because the ruling treats any leveraged exposure to a non-security commodity as a regulated instrument.

The opinion does not address spot, unleveraged trading, leaving the SEC-CFTC turf war alive for now. But for traders and platforms operating in the gray zone of “almost futures,” the Seventh Circuit just turned the lights on.

×