DC Circuit Orders SEC to Reconsider Grayscale’s Spot-Bitcoin ETF Denial

Wellermen Image Court Hands Grayscale a Rare Win Against SEC

The D.C. Circuit just ordered the Securities and Exchange Commission to reconsider its 2022 denial of Grayscale’s spot-Bitcoin ETF application. By ruling that the agency treated identical products inconsistently, the court exposed the SEC’s reasoning as arbitrary and capricious, giving the first credible crack in the agency’s wall against spot-crypto funds.

Grayscale had asked the Commission to convert its long-running Bitcoin Investment Trust into an exchange-traded product that would let retail investors trade actual bitcoin shares on NYSE Arca. The SEC rejected the proposal, arguing that the exchange had failed to demonstrate how it would detect and deter fraud and manipulation. Grayscale appealed, pointing out that the same exchange already lists futures-based bitcoin ETFs that the Commission had approved months earlier. The three-judge panel agreed, holding that the SEC could not demand stricter surveillance standards for spot products while accepting weaker ones for futures without explanation.

The ruling does not force the SEC to approve the ETF; instead, the court remanded the matter so the agency must either provide a coherent reason for treating spot and futures products differently or drop its objection. Grayscale wins a procedural victory that forces regulators back to the drawing board, while the SEC loses the presumption that its prior reasoning will survive judicial scrutiny. Exchanges and issuers now have a template for challenging similar rejections.

In plain English, the court told the SEC it cannot keep moving the goalposts. If futures ETFs are safe enough for retail money, the agency must explain why holding actual bitcoin is riskier, or it must let both structures compete. That single requirement chips away at the Commission’s discretionary power and shifts momentum toward products that give investors direct exposure rather than synthetic futures rolls.

For markets, the decision signals that the SEC’s blanket resistance to spot bitcoin is no longer untouchable. A successful Grayscale relaunch could suck liquidity out of the futures complex, pressure the CME’s dominance, and force competing issuers to file fresh applications. Stablecoin issuers and DeFi protocols should watch closely: if a regulated, on-chain asset can clear the manipulation test, arguments against tokenized Treasuries or other real-world-asset products weaken. Traders will price in higher odds of eventual spot approval, but volatility will remain elevated until the SEC issues a new order.

The window for approval just cracked open—how wide it swings depends on whether the agency doubles down or finally writes rules that treat like products alike.
Seventh Circuit Expands CFTC Authority Over Leveraged Crypto Investments

Wellermen Image Court Hands CFTC Broad Power Over Crypto “Investments”
The Seventh Circuit just told the CFTC it can police almost anything sold as a futures contract—even when the product is a cryptocurrency and no exchange ever lists it. In a 3-0 decision, the court upheld a $1.7 million judgment against James Donelson for running a Ponzi-style scheme that promised customers “off-exchange retail commodity transactions” in digital assets. The ruling matters because it widens the agency’s reach at the exact moment Washington is still fighting over whether the CFTC or the SEC should regulate crypto.

Donelson had pitched investors a platform that let them trade Bitcoin, Ethereum and Litecoin on 100-times leverage without ever taking delivery of the coins. When the CFTC sued, Donelson argued the trades were not “commodity transactions” under the CEA because no actual futures contracts existed on any registered exchange. The district court disagreed, found Donelson had defrauded roughly 600 customers, and ordered restitution plus a lifetime trading ban. On appeal, Donelson claimed the CFTC lacked jurisdiction over spot-crypto markets and that his users were simply buying the tokens outright.

Writing for the panel, Judge Michael Scudder ruled that the CEA’s retail-commodity provision covers any “agreement, contract or transaction” that is margined or leveraged and involves a non-financial commodity, regardless of whether it is called a future. The court held that Donelson’s scheme met that test because customers put up a fraction of the notional value and settled in cash based on price moves—exactly the economic profile of a futures contract. The judges rejected Donelson’s delivery argument, noting that actual delivery never occurred and that the platform’s terms made physical settlement impossible.

The decision tightens the vise on any platform that offers U.S. customers crypto exposure on margin or leverage without CFTC registration. It also signals that courts will look past labels and examine the economic substance of a product—raising compliance costs for offshore exchanges and DeFi protocols that serve American traders. Stablecoins used as margin may now draw extra scrutiny, because the ruling treats any leveraged exposure to a non-security commodity as a regulated instrument.

The opinion does not address spot, unleveraged trading, leaving the SEC-CFTC turf war alive for now. But for traders and platforms operating in the gray zone of “almost futures,” the Seventh Circuit just turned the lights on.

European Central Banks Push Crypto Stablecoin Yield Ban on Lending, Staking

Central Bankers Warn of Blurred Distinction Between Payment Tokens and Bank Deposits

Central bankers argue that indirect yield structures for electronic payment tokens could blur the distinction between those assets and commercial bank deposits, potentially affecting competition across the financial system.

Concerns Over Financial Market Competition

According to the central bankers’ view, arrangements that provide token holders with an indirect return may make payment tokens more comparable to interest-bearing bank deposits. This could complicate the competitive relationship between token issuers and traditional financial institutions.

Why the Distinction Matters

Electronic payment tokens are generally designed for transactions, while commercial bank deposits are liabilities of banks and form part of the established deposit-taking system. Any structure that narrows the functional gap between the two may raise broader questions about market incentives and the organization of financial services.

Third Circuit Rules: SEC Keeps Crypto Rulemaking Authority as Coinbase Appeal Fails

Wellermen Image Court Slams Coinbase Appeal: SEC Keeps Full Authority Over Crypto
The Third Circuit has shut down Coinbase’s attempt to force the SEC into a rulemaking process for crypto assets, leaving the agency’s enforcement-first approach untouched. The ruling keeps the current legal fog over tokens, exchanges, and DeFi protocols firmly in place and signals that the SEC’s power to decide what counts as a security remains intact for now.

Coinbase had asked the court to compel the SEC to issue clear rules on how digital assets should be treated under existing securities laws, arguing that years of enforcement actions without guidance violated the Administrative Procedure Act. The SEC countered that it had already exercised its discretion by choosing enforcement over rulemaking and that courts should not second-guess that choice. The three-judge panel agreed, finding that Coinbase lacked a statutory right to force the agency’s hand.

The decision came down to one key legal question: does the SEC have a legal duty to start a rulemaking when asked by an industry player? The court said no. It held that the agency’s refusal to begin a rulemaking is presumptively unreviewable, and Coinbase failed to show the kind of “extreme” facts that would justify overriding that discretion. In practical terms, the judges ruled that the SEC can keep bringing cases one token at a time instead of writing broad rules that would give the whole industry more certainty.

The ruling does not decide whether any specific token is a security. It simply says the SEC does not have to answer that question through rulemaking if it prefers to litigate instead. That leaves the agency free to continue its enforcement campaign without issuing industry-wide guidance, and leaves exchanges, protocols, and traders operating in the same gray zone they have been in for years.

For crypto markets, the decision reinforces the SEC’s current advantage: it can classify tokens as securities case-by-case, keep pressure on exchanges, and avoid the political and legal risks of a broad rulemaking. Stablecoin issuers, DeFi platforms, and U.S.-facing exchanges now face continued litigation risk rather than regulatory clarity, which tends to favor larger, better-capitalized players who can absorb legal costs. Smaller protocols and retail traders are left guessing which tokens might draw the next enforcement action.

The message to the market is simple: until Congress acts or the SEC changes course, expect enforcement to remain the primary form of crypto regulation in the United States.

Unusual Trades Dominate Bitcoin and Ether Perpetual Volumes on Kalshi

Specific Trade Sizes Dominated Sampled Crypto Perpetual Volume

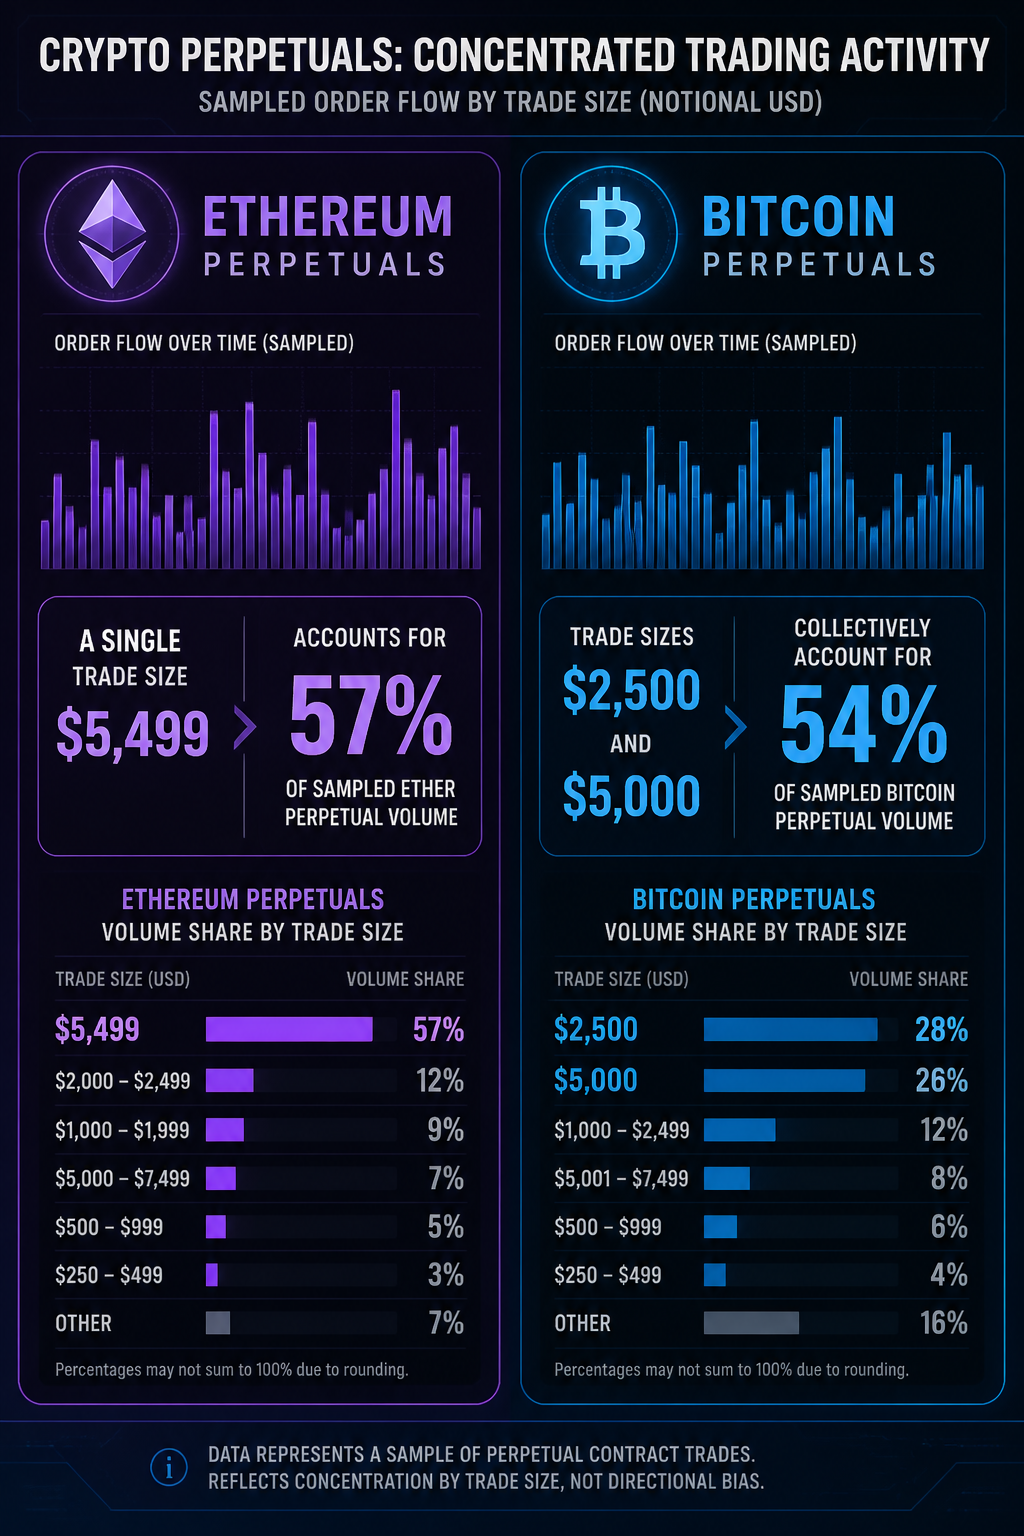
Trading activity in sampled cryptocurrency perpetual contracts was heavily concentrated around a small number of order sizes, according to CoinDesk.

Ether and Bitcoin Perpetuals Show Concentrated Activity

A $5,499 trade size accounted for 57% of the sampled volume in ether perpetual contracts. In bitcoin perpetuals, recurring trade sizes of $2,500 and $5,000 collectively represented 54% of the sampled volume.

Perpetual contracts are derivatives that allow traders to speculate on cryptocurrency prices without an expiration date. The concentration around specific trade sizes highlights the distribution of activity within the sample but does not, by itself, indicate the direction of market prices.

US Bank Tests Proprietary Stablecoin for Cross-Border Payments on Stellar

Wellermen Image

US Bank Tests Proprietary Stablecoin Across Stellar Network

A US bank has tested its proprietary USBDC stablecoin in a cross-border transfer between its North American and European entities. The pilot ran on the public Stellar blockchain, offering a real-world test of whether bank-issued digital dollars can make international payments faster and more efficient.

The transaction matters because it moves stablecoins beyond crypto-native trading and into institutional settlement. By using Stellar’s public network, the bank is testing whether blockchain infrastructure can connect different regions without relying entirely on traditional correspondent banking channels.

USBDC was moved between the bank’s North American and European operations during the pilot. The snippet does not disclose the transaction size, timing, or the bank’s plans for a broader rollout, so the test should be viewed as an early proof of concept rather than a finished payments product.

What This Means for Crypto

In plain English, a proprietary stablecoin is a digital token issued by a bank and designed to maintain a stable value, typically against a national currency. If these tokens can move across borders securely, banks could settle transactions around the clock instead of waiting on slower legacy systems.

For traders and long-term investors, the test strengthens the case for stablecoins as core financial infrastructure. For builders, it highlights continued demand for public blockchains that can support compliant, high-volume payments without being limited to speculative crypto activity.

Market Impact and Next Moves

The immediate market reaction is likely mixed but strategically bullish for stablecoin and payments narratives. One pilot will not transform cross-border finance, yet institutional experiments can attract capital and encourage more banks to test blockchain-based settlement.

The main risks are regulation, liquidity, interoperability, and whether banks ultimately prefer private networks over public chains. The opportunity is clearer: if institutions expand these trials, networks such as Stellar could gain adoption from real payment flows rather than short-lived token speculation.

Stablecoin pilots are becoming more important than crypto hype cycles—but investors should wait for scale, repeat usage, and regulatory clarity before treating this test as a breakthrough.

Crypto Groups Sue to Block Illinois’ 0.2% Tax Before January Rollout

Wellermen Image

Crypto Groups Fight Illinois Tax Before January

Crypto Council for Innovation and the Blockchain Association are seeking to block Illinois’ proposed 0.2% crypto tax before it takes effect in January. The groups argue the levy is unconstitutional and could create expensive, complicated compliance demands for digital-asset businesses.

The challenge follows an earlier lawsuit targeting the Illinois tax, putting the state’s policy directly at odds with major crypto trade groups. Their argument centers on both legality and implementation: even a seemingly small tax could become costly when applied across frequent trades, transfers, and other digital-asset activity.

If the lawsuit succeeds, crypto companies and users in Illinois could avoid the new charge and the reporting burden tied to it. If the state prevails, exchanges, investors, and blockchain businesses may need to build new systems to track taxable activity before the January effective date.

What This Means for Crypto

The proposed 0.2% tax is not simply a fee on profits. Depending on how Illinois applies it, the levy could affect transaction activity and force businesses to collect, calculate, and report additional information. That is why industry groups warn that compliance costs could exceed the headline tax rate.

For traders, the dispute creates uncertainty over future transaction costs. Long-term investors may see limited immediate impact, but builders and crypto companies could reconsider operating in Illinois if the rules are viewed as too expensive or legally vulnerable.

Market Impact and Next Moves

The short-term market mood is likely mixed rather than broadly bullish or bearish. This is a state-level legal battle, not a direct threat to major tokens, but it adds to the regulatory uncertainty that already influences where crypto businesses choose to operate.

The key risk is that other states could adopt similar taxes if Illinois succeeds, raising costs across the industry. The opportunity for investors is less about trading the headline and more about watching the court fight for signals on whether U.S. crypto regulation is becoming clearer—or more fragmented.

Illinois’ crypto tax battle could determine whether digital-asset growth is taxed into compliance or pushed toward friendlier jurisdictions.

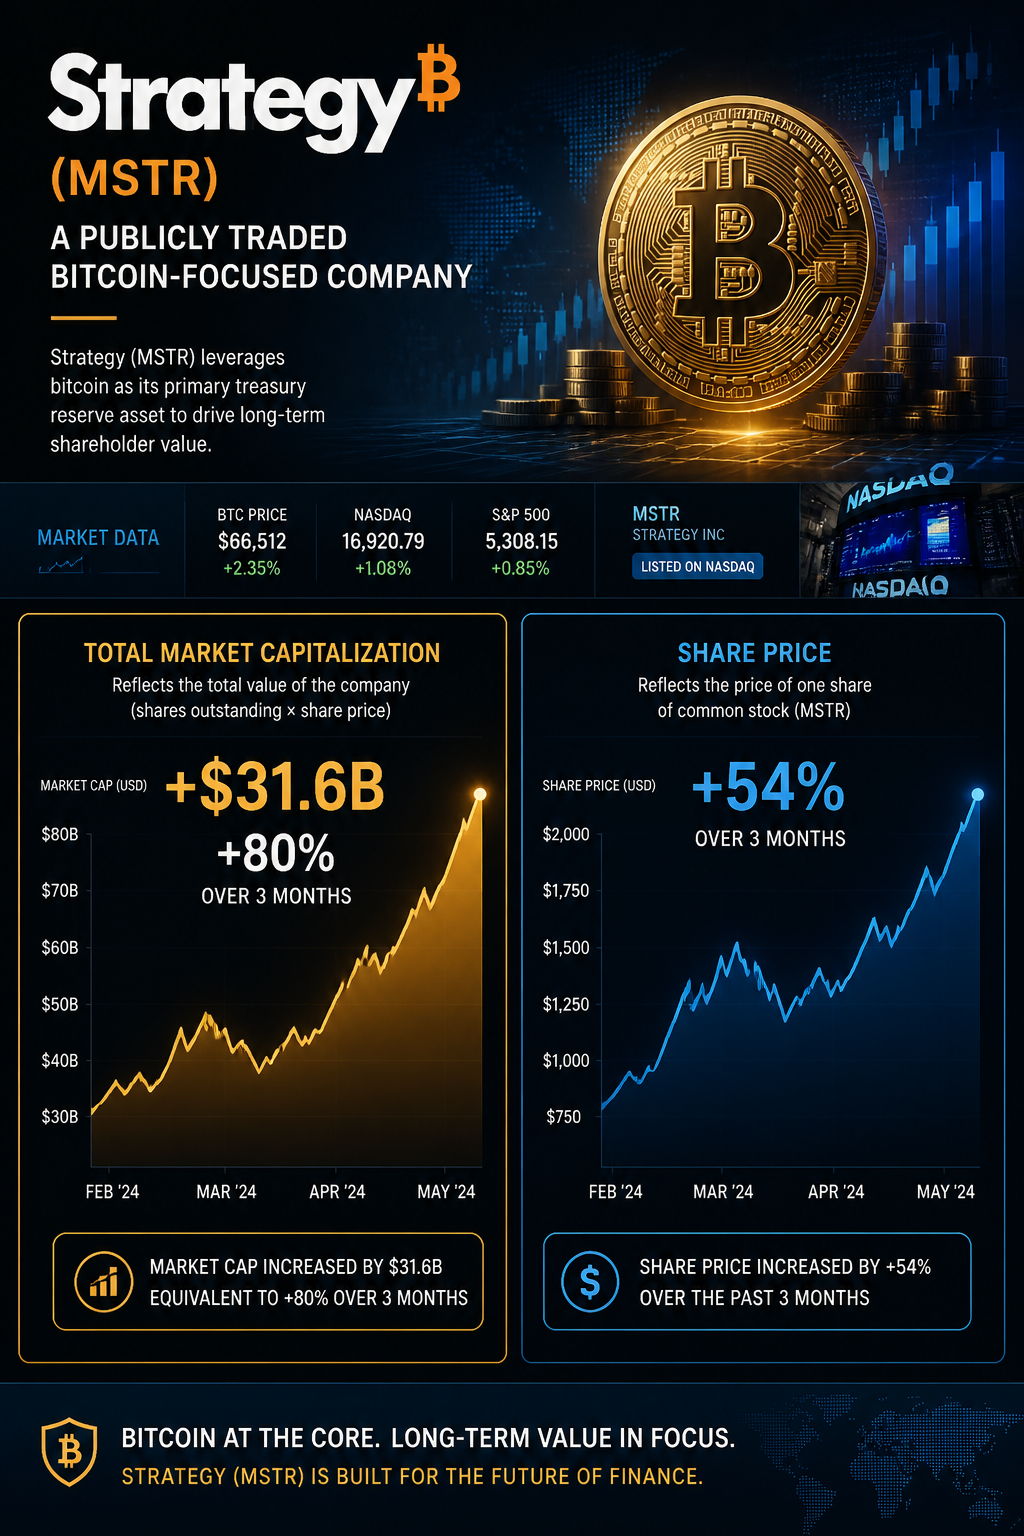
Strategy Market Cap Surges 80% in Three Months, Stock Jumps 54%

Strategy Says Market Value Increased by $31.6 Billion in Three Months

Strategy reported that its market capitalization rose by approximately $31.6 billion, or 80%, over the past three months, while the company’s Class A share price increased by about 54% during the same period.

Strategy Highlights Market Capitalization Growth

The company shared the figures in a post on X on Monday, accompanied by a chart summarizing the performance of its MSTR shares and overall market value.

“Last 3 months for MSTR: +$32B (+80%),” Strategy wrote in the post. The company’s figures indicate that its market capitalization grew at a faster rate than the price of its publicly traded Class A shares.

Market Capitalization and Share Price Measure Different Metrics

Market capitalization reflects the total value of a company’s outstanding shares, while the share price measures the value of an individual share. As a result, the two figures can move by different amounts when the number of shares outstanding changes.

Strategy’s Class A shares rose approximately 54% over the three-month period cited by the company. The market capitalization figure includes the broader value of the company’s outstanding equity.

Strategy’s Market Position

Strategy has become one of the most closely watched publicly traded companies in the cryptocurrency market because of its bitcoin-focused corporate treasury strategy. Its equity performance is often assessed alongside bitcoin prices and broader investor demand for publicly traded vehicles offering exposure to the asset.

LAPTOP Memecoin Turns Hunter Biden Controversy Into a High-Risk Crypto Bet

Wellermen Image

LAPTOP Memecoin Turns Political Controversy Into Speculation

A new memecoin called LAPTOP is using Hunter Biden’s laptop controversy as its core narrative, while openly admitting it has no utility. The project says founder tokens will remain locked for six months and that 2% of the supply is reserved for wallets that lost money on TRUMP, adding a political and retaliatory angle to an already volatile market.

The project appears designed to capitalize on the lingering attention around the laptop controversy and the broader rise of politically themed crypto tokens. Its disclosures are unusually direct: LAPTOP is not presenting a product, protocol, or long-term technical use case, but a tradable meme built around controversy and online momentum.

The token lock may offer some short-term reassurance by limiting immediate founder selling, but it does not remove the risk of a sharp collapse once attention fades or the lock expires. The 2% allocation for TRUMP-related losers is more symbolic than substantive, and investors should verify how eligibility, distribution, and wallet identification will actually work.

What This Means for Crypto

In plain English, LAPTOP is a narrative asset rather than an operating crypto project. Its value will depend heavily on social media attention, political headlines, trading liquidity, and speculation—not on revenue, technology, or network usage.

Traders may see an opportunity if the meme catches fire, but long-term investors face a much weaker foundation. Builders and serious market participants should view the launch as another example of how crypto can turn cultural and political moments into tradable assets almost instantly.

Market Impact and Next Moves

The immediate sentiment is likely mixed: politically themed memecoins can attract fast momentum, but the lack of utility also makes them vulnerable to rapid profit-taking and manipulation. A six-month founder lock reduces one obvious source of selling pressure, yet liquidity, contract controls, and ownership concentration remain critical risks.

The main opportunity is short-term exposure to a fresh narrative; the main danger is mistaking attention for adoption. Traders should avoid leverage, confirm the token’s contract and liquidity conditions, and remember that the unlock date could become a major exit-risk event.

LAPTOP may win the attention game, but without utility or durable demand, investors are ultimately betting on the controversy staying louder than the sell button.

Polymarket Ignored Warnings Before $10M Fraud Attack, Report Says

Polymarket Faces Scrutiny After Alleged $10 Million Debit-Card Fraud Scheme

Prediction-market platform Polymarket is facing scrutiny after bad actors allegedly used stolen debit cards to target its U.S. platform in a fraud scheme estimated at $10 million. The activity reportedly prompted payment processor Checkout.com to reject more than 80% of deposits as potentially fraudulent.

High Fraud-Rejection Rate Raises Compliance Concerns

The incident has fueled accusations that Polymarket prioritized user growth and expansion over safeguards designed to prevent payment fraud. The platform’s U.S. operations reportedly experienced a sharp increase in suspicious deposits linked to compromised debit cards.

Checkout.com, which processes payments for the platform, responded by blocking a significant majority of deposits after identifying patterns associated with fraudulent transactions. The scale of the rejections highlights the challenges facing online prediction markets as they expand their customer bases and payment infrastructure.

Questions Over Risk Controls

The episode has also raised questions about whether Polymarket acted quickly enough on warnings related to suspicious payment activity. Effective controls typically include identity verification, transaction monitoring and measures to detect stolen-card use before funds are accepted.

Fraud involving payment cards can expose platforms to financial losses, chargebacks and increased scrutiny from payment providers. It can also affect legitimate users if processors respond by imposing stricter deposit restrictions.

Broader Implications for Prediction Markets

Prediction markets allow users to trade contracts tied to the outcomes of events, including elections, economic developments and other real-world activities. As these platforms attract more users, their ability to manage fraud, comply with financial regulations and maintain reliable payment systems is becoming increasingly important.

The reported incident underscores the operational risks associated with rapid expansion. Payment processors may impose tighter controls or reject more transactions when fraud rates rise, potentially limiting a platform’s ability to onboard users and process deposits.

DraftKings Shelved Problem-Gambling AI While Targeting High-Risk Bettors

New York Times Reports DraftKings Targeted Gamblers Predicted to Lose the Most

DraftKings developed a machine-learning model to direct promotional offers toward customers it predicted would lose the most money, while internal efforts to identify potential problem gamblers were discontinued, according to a New York Times investigation published Saturday.

Model Focused on Expected Losses

The Times said its reporting was based on interviews with current and former employees familiar with the company’s practices. The investigation described an internal system designed to identify gamblers considered especially valuable because of their projected losses.

The reported strategy raises questions about how online gambling companies use customer data and predictive analytics to personalize promotions. Such systems can analyze betting behavior, spending patterns and engagement to determine which customers receive targeted offers.

Problem-Gambling Detection Efforts Shelved

According to the report, DraftKings also pursued technology intended to predict which customers might develop gambling problems. Those efforts were later shelved, the newspaper reported.

The contrast between attempts to identify likely high-loss customers and the decision to discontinue problem-gambling prediction initiatives has drawn scrutiny from gambling researchers and consumer-protection advocates.

DraftKings Disputes the Characterization

DraftKings rejected the Times’ characterization of its practices. The company has not publicly confirmed the specific details of the reported model or explained why the internal problem-gambling initiative was discontinued.

The report adds to ongoing concerns about the use of artificial intelligence and machine learning in online betting, particularly as operators expand personalized marketing and risk-monitoring systems.

Dogecoin Jumps 15% as Bitcoin Holds Above $85,000 in Market Rebound

Short Squeeze Loses Momentum After $844 Million in Liquidations

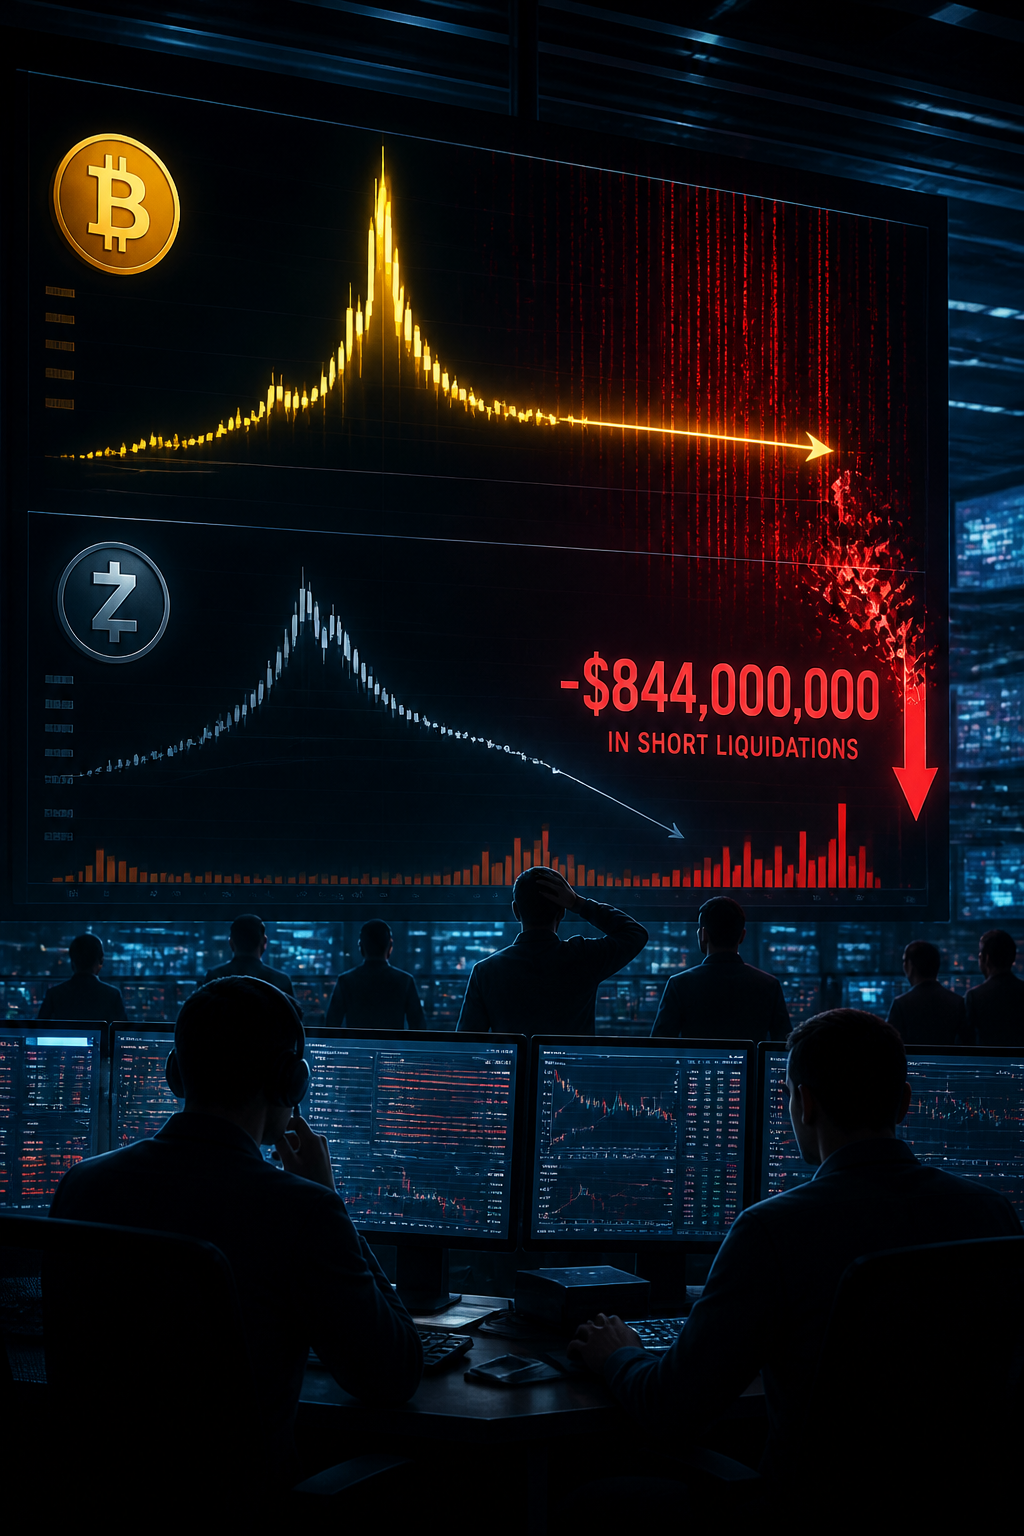
A wave of forced buying that resulted in approximately $844 million in losses for cryptocurrency short sellers has subsided, leaving Bitcoin largely unchanged over the past hour. Zcash (ZEC) was the only major token trading lower during the period.

Short Sellers Absorb Heavy Losses

The forced buying was driven by the liquidation of leveraged short positions. When these positions are closed, exchanges typically buy the underlying assets, adding upward pressure to the market and potentially accelerating price moves.

Bitcoin Holds Steady as ZEC Declines

After the liquidation-driven move, Bitcoin remained broadly flat on a one-hour basis. Among major cryptocurrencies, Zcash was the only token reported to be in negative territory, suggesting that broader market momentum had eased following the short-covering activity.

ECB to Invest Directly in Tokenized Securities Through Pontes

ECB Prepares to Invest in Tokenized Euro-Denominated Securities

The European Central Bank has begun preparations to invest a small portion of its own-funds portfolio in tokenized euro-denominated securities, marking a potential shift from developing tokenized-settlement infrastructure to using it directly.

Initial Investment Focus

The planned investments are separate from the ECB’s monetary-policy operations. They would be made through the central bank’s own-funds portfolio, a non-monetary-policy pool.

The initial eligible assets are expected to include securities issued by:

  • Euro-area central governments;
  • Regional governments and agencies; and
  • European supranational institutions.

Tokenized securities are digital representations of financial assets recorded and transferred using distributed-ledger or similar technology.

Settlement Planned Through Pontes

The ECB intends for the purchases to settle in central-bank money through Pontes, the Eurosystem’s infrastructure for settling tokenized financial assets.

The plan would make the ECB not only a provider of tokenized-settlement infrastructure for market participants but also a potential user of that infrastructure for its own portfolio transactions.

No Purchases Have Been Completed

The ECB’s announcement concerns preparatory work. It has not stated that any tokenized securities have already been purchased for the own-funds portfolio.

Operational timing and execution details will be determined after the preparation phase and a subsequent review by the ECB’s Executive Board.

If implemented, the initiative could move tokenization beyond pilot programs and into the routine management of an institutional investment portfolio. For now, however, the development represents a planned use case for Pontes rather than completed trades.

Kalshi Wins Again as Court Slams CFTC Overreach on Election Contracts

Wellermen Image KALSHI WINS AGAIN AS COURT SLAMS CFTC’S OVERREACH
A federal appeals court has refused to block KalshiEX from offering election contracts, effectively slapping the CFTC for trying to stretch its power beyond what Congress granted. The decision keeps the trading venue open for now and signals that federal regulators cannot simply declare something off-limits without clear statutory authority.

The fight started when Kalshi sought CFTC approval to list contracts tied to U.S. election outcomes. The agency said no, arguing that letting people bet on elections would be “contrary to the public interest.” Kalshi sued, claiming the CFTC lacked the legal power to block contracts based solely on its own view of morality or politics. A district judge agreed and ordered the agency to let the contracts trade; the CFTC immediately asked the D.C. Circuit to freeze that order while it appealed. On October 2, the appeals court denied the stay, letting the lower-court ruling stand for now.

Judges on the three-member panel focused on whether the CFTC had shown a likelihood of success on the merits and whether halting trading would cause irreparable harm. They found the agency’s public-interest argument too vague to override the Commodities Exchange Act’s presumption that exchanges can list contracts unless they violate specific statutory bans. The court also noted that Kalshi had already invested heavily in compliance systems, so the balance of equities tilted toward letting trading begin. In short, the CFTC lost this round and must now either prove its case on a full appeal or watch the contracts go live.

The ruling narrows the CFTC’s discretion to veto products on broad policy grounds. The agency still regulates fraud and manipulation, but it cannot simply brand an instrument “bad for society” and shut it down without pointing to concrete statutory language.

For crypto traders and DeFi builders, the decision is a green light: prediction markets, event contracts, and other novel instruments now face a lower regulatory hurdle. Expect more election-related tokens, on-chain betting protocols, and exchange listings that sidestep traditional gatekeepers. Stablecoin issuers and decentralized platforms that offer similar exposure should still watch for fraud rules, but the threat of a blanket CFTC veto just shrank.

Regulators will keep testing their reach, yet today’s order shows that judges can—and will—push back when agencies stretch beyond the text of the law.

Court Denies Envy Blockchain’s Last-Ditch Bid to Skip Trial

Wellermen Image COURT KILLS BLOCKCHAIN COMPANY’S LAST-DITCH BID TO SKIP TRIAL

Envy Blockchain, NV Landco 1, and CEO Stephen DeCani just lost their emergency bid to halt a Texas district-court case mid-stream. The El Paso Court of Appeals refused to issue a writ of mandamus that would have frozen discovery, sanctions motions, and a looming trial date, effectively telling the company that litigation pain cannot be sidestepped by appellate shortcut. The ruling lands at a moment when crypto firms already feel the squeeze of both civil suits and regulatory scrutiny.

The fight began when a Texas investor accused the three parties of misusing funds raised for a planned Bitcoin-mining facility. After the district judge allowed broad discovery and sanctioned the defendants for discovery abuse, Envy and its co-defendants raced to the appellate court, arguing the lower court had no jurisdiction because the mining project never left the idea stage and the claims sounded in securities fraud—an area they claimed was preempted by federal law. The panel cut through the argument in a single paragraph: mandamus is an extraordinary remedy, and Envy had failed to show the district court was “clearly and indisputably” out of bounds.

In plain terms, Texas courts will keep jurisdiction, evidence will be exchanged, and the case heads toward either settlement or a jury verdict. That means more documents, more depositions, and more potential headlines about missing investor money. For crypto projects still structured as Texas LLCs or still courting Lone-Star capital, the decision is a reminder that state-court dockets move faster than federal crypto rule-making.

From a market perspective, the ruling quietly tilts power toward plaintiffs and state attorneys general while the SEC and CFTC continue to spar over digital-asset turf. Every new document unsealed in discovery could feed enforcement theories on unregistered securities or commodities, raising due-diligence costs for exchanges listing tokens tied to mining ventures. Traders pricing governance tokens or mining-related equities will now bake in a higher Texas-litigation premium.

Bottom line: if your tokenomics live in Texas courts, plan for discovery, not just disclosure.

×